






Pinned Tweet
It’s completely logical that someone old school who doesn’t understand how an API works would think crypto brings nothing new to the financial industry.
Of course NASDAQ could have enabled 24/7 trading a long time ago. Two systems can achieve the same objective. What’s interesting is how, under capitalism, incentives and competition push the world toward resource optimization and greater well-being.
For 10+ years, the crypto industry has been developing and optimizing this technology across every layer: infrastructure (TPS, gas fees, Ethereum, Solana, L2s), UX (paymasters, chain interoperability, smart wallets), and standards (ERC-20, ERC-4626, ERC-4337, etc.), eventually passing the “fintech test”: crypto becoming completely imperceptible behind a financial product.
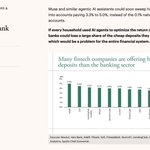
We reached the point where the efficiency this technology brings to capital is becoming impossible for the traditional financial system to compete with. Banking associations are literally lobbying to restrict stablecoin yield because of the risk of deposits moving out of banks (CLARITY act).
This is thousands and thousands of high-IQ brains from completely different backgrounds (with a disproportionately high number of physicists, mathematicians, cryptographers and engineers) building on decades of old papers and coordinating through open standards like ERCs.
For better (and worse during hacks), this creates a virtuous spiral of new developments composable with everything that came before them. ERC-20 gave us a common interface for assets. ERC-4626 standardized tokenized vaults. ERC-4337 enabled smart accounts and paymasters. Then you have protocols like Uniswap for exchange, Aave for credit, stablecoins like USDC for settlement, tokenized RWAs like BlackRock’s BUIDL, and blockchains competing to make all of this cheaper and faster. Every new primitive becomes another Lego block available to everyone else. That level of permissionless composability is something the old APIs of Wall Street could never achieve at the same speed. Not to mention each third world country's financial system.
The same reason we moved from physically exchanging gold or salt to fiat money, making value easier and more efficient to transfer, implies that the next natural step is for money to become not only digital, but fully programmable, with maximum precision and speed.
Historically, an enormous amount of people’s wealth has simply sat in fiat. Only a few people physically operated in financial markets.
Then more people could manually trade digitally, making a handful of transactions per year. And only the wealthiest could afford to have a specialized human managing and optimizing their capital every single day.
In the future, everyone will have an AI Agent continuously optimizing their resources according to their life goals and risk appetite. It will continuously decide where it should be allocated, how much liquidity you need, what risk you should take, where your idle capital should earn yield, what debt should be repaid, what assets should be rebalanced, and how to do all of it at the lowest possible cost.
As financial assets become liquid, programmable, globally accessible and almost frictionless to move between, capital can increasingly move from passive money into productive assets. That has two consequences:
1. More capital is constantly working and financing productive activity.
2. People become less dependent on holding monetary assets that governments can dilute to finance spending and influencing elections around the world.
Capital becomes more productive, while monetary dilution becomes a less effective way of silently transferring purchasing power from savers to the issuer.
That level of efficiency is simply not possible if an AI has to wait 1 to 5 business days for a SWIFT transfer, ask permission from different intermediaries, integrate with dozens of proprietary APIs, and respect the opening hours of financial institutions.
And perhaps the best part is that the underlying rails don’t need to belong to anyone. The assets running on top can be centralized or decentralized. USDC can have an issuer. BlackRock can issue a tokenized fund. A bank can tokenize deposits. But at the same time the underlying settlement layer can be open, permissionless and decentralized, with full traceability (but privacy too, soon). That's also crypto's maturity from a hackers experiment to the world's financial backend.
So the difference is much more profound than simply making NASDAQ trade 24/7.
The use cases are converging: regulated stablecoins, tokenized RWAs, DeFi lending, DEXes, smart wallets, instant global settlement and very soon autonomous AI agents interacting safely with all of them. Fortunately, the largest financial institutions have already realized the potential.
Sooner than later, people will enjoy the benefits of a more efficient financial system without even realizing that crypto and AI are running underneath it.
Higher.


my TL rn:
"THIS IS INSANE"
"OMG incredible look at this"
"OH we are F*CKED"
"MINDBLOWING harness"
pls @XOpenSource do something
starting to feel like old school media.
4
150
Martin retweeted
🇵🇾 Paraguayans in 2026
🇦🇷 Argentines in 2001
🇧🇷 Brazilians in 1990
🇪🇨 Ecuadorians in 1999
🇬🇷 Greeks in 2015
🇨🇾 Cypriots in 2013
🇱🇧 Lebanese in 2019
🇮🇸 Icelanders in 2008
...
We were all sadly forced to understand the value of self-custody.
Financial crises don't discriminate by nationality, race, or wealth, despite some systems are more resilient than others.
Rome, and an entirely new financial system, can't be built in a day or without friction. But we've reached a point where technology can make self-custody possible with even better UX.
If crypto were just about capital efficiency, better APIs and cheaper intermediaries would've been enough.
DeFi is about redefining the roles, aligning incentives without compromising ownership.
Self-Sovereign will win.

Really sad to see what’s happening in Paraguay, where over 60% of the population is losing access to their funds held in banks.
As DeFi and stablecoins gain adoption among fintechs, we must remember the bigger mission, which is building a self-sovereign financial system where access to your own money is a fundamental right, not a privilege granted by an intermediary.
🇵🇾 Paraguayans in 2026
🇦🇷 Argentines in 2001
🇧🇷 Brazilians in 1990
🇪🇨 Ecuadorians in 1999
🇬🇷 Greeks in 2015
🇨🇾 Cypriots in 2013
🇱🇧 Lebanese in 2019
🇮🇸 Icelanders in 2008
...
We were all sadly forced to understand the value of self-custody.
Financial crises don't discriminate by nationality, race, or wealth, despite some systems are more resilient than others.
Rome, and an entirely new financial system, can't be built in a day or without friction. But we've reached a point where technology can make self-custody possible with even better UX.
If crypto were just about capital efficiency, better APIs and cheaper intermediaries would've been enough.
DeFi is about redefining the roles, aligning incentives without compromising ownership.
Self-Sovereign will win.
Really sad to see what’s happening in Paraguay, where over 60% of the population is losing access to their funds held in banks.
As DeFi and stablecoins gain adoption among fintechs, we must remember the bigger mission, which is building a self-sovereign financial system where access to your own money is a fundamental right, not a privilege granted by an intermediary.
Martin retweeted

Aave markets are "frozen", not "paused".
- No new deposits or borrows allowed.
- Withdrawals, repayments, and liquidations keep running (those stop when pausing).
Whether or not you agree with the freeze, it's good to know the difference.

We’re aware of reports of a potential incident affecting Binance-affiliated wallets.
Aave’s contracts are unaffected, and positions remain overcollateralized. As a precaution, all DAO-operated markets across V3 and V4 have been frozen.
The freeze pauses new deposits and borrows, and users can still withdraw and repay their existing positions.
Countries have used gold as collateral for centuries. Why shouldn't individuals?

After our SEC Reg Crypto Assets letter, we've responded to @TheFCA on tokenised gold.
Same message both sides of the Atlantic: tokenisation is about collateral mobility, not just trading.
£52m of tokenised gold works as collateral on @aave. Regulatory certainty will scale it. aave.com/policy/uk-fca-token…

2
14
347


history went from trading stocks in paper to aave
New @Citi research positions Aave as a collateral mobility protocol for tokenized capital markets.
It calls collateral mobility one of tokenization’s most important use cases, with Aave able to take on functions that move tens of trillions of dollars in traditional finance.

Martin retweeted

Few understand how big of a deal this is.
Historically brokerages have lent out your stocks and have kept 80+% of the value.
On-chain finance, lead by @aave is revolutionizing the world of equities.
Aave DAO has approved incentives for the Coinbase Tokenized Stocks market on @base.
Tokenized stocks are only available in eligible jurisdictions outside of the U.S.

Martin retweeted

Idle crypto sitting in your wallet? I put mine to work with one prompt in Claude Code using the Aave MCP and a MetaMask agent wallet.
Here’s how it went.
3 years since October 7.
Before, a Hamas co-founder said on TV the goal is not only their land but "the entire Planet Earth", with "no treacherous Christianity".
You don't need to pick a side on this complex conflict. Just don't excuse terrorists who have you as a target too.
10
290


🇦🇷 Buscamos dev full-stack SSr para startup muy innovadora de AccountingTech 🧮
Todos los días procesan cientos de CUITs y miles de facturas en varios servicios. Hace 2 años iterando en stealth con clientes propios, beta privada y ahora agrandando el equipo para bancar nuevas escalas.
Stack general: NextJS, TS, Python, AWS
Ideal: xp shippeando lógica no vibecodeada, frameworks AI y saber lo que hace un contador :)
Refes tinene recompensa! DM abierto!
Por Malvinas.
Por el Diego.
Por el último Ghost Pass de Leo.

gm, Argentina! 🇦🇷
Looking for early users based in Argentina with an iPhone to try the @aave app and provide feedback! If that’s you and you need a Ghost Pass, hit me up. 👻
The World’s Savings App 🌐


which applies to any kind of verified targeting, including marketing -- @targecy_ads 🥹

🚨 LATEST: SEC Commissioner Hester Peirce says zero-knowledge proofs could verify compliance without collecting users’ personal data.
She warns current KYC/AML practices create “data haystacks.”

2
205
