

Head of digital assets research @VanEck_us. PM, VanEck Onchain Economy ETF ($NODE). ❌️ Disclosures https://teapawt.org/t.co/oN8RR1GzoJ https://teapawt.org/t.co/kuyqdO3qgW
NYC
Joined July 2017
- Tweets20.8K
- Following2.6K
- Followers67.5K
- Likes37.7K



Leverage is draining fast from the Bitcoin futures market.
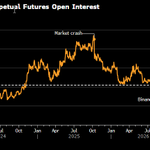
Perps OI at $41B is lowest since November 2024, down ~20% this month.

$NVDA interim CEO all-hands meeting attracts 700+ questions from employees.
Per Wired reporting:
#1 topic: Compensation concerns
#2 topic: More transparency from the board on the CEO search
Kress’s notable responses:
>Promised early pay raises and additional equity in December, ahead of schedule
>Called stabilizing the workforce “probably the most important thing” leadership is focused on


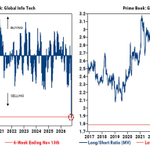
Tech experiencing a 4+ standard deviation degrossing. The most extreme hedge fund position unwind in a decade.

matthew sigel, recovering CFA retweeted
I believe the @nvidia board is not acting in the best interest of shareholders nor in a manner consistent with their fiduciary duties.
What we know is that the board fired Jensen or forced his resignation for violating company policy and/or in response to the accusation of an affair with a spy.
They did so without careful consideration of the impact on the company, its customers, its shareholders or other stakeholders.
They rushed to judgment without the benefit of careful due diligence or even with a basic understanding of the facts.
How do we know this?
We know this by how quickly Jensen was fired and how little was known at the time of his firing.
It takes time to convene a board meeting. There was time, maybe, for one Zoom.
And this is a decision that should have been made by a board sitting in person and carefully deliberating the facts once they are known.
And they should have slept on the decision and met again the day after to discuss the facts, the risks and the other implications of their decision.
The timing and lack of information did not allow for careful board deliberation.
While boards can fire a CEO for an inappropriate relationship with a subordinate, it should not be an automatic decision. That is why we have boards comprised of humans and not agents.
A board should consider whether or not such a relationship was consensual or whether it was an abuse of power dynamics. And a board has to consider what the impact of the firing is on all stakeholders.
If I were in this board, I would not have rushed to judgment based on articles in the media. I would have made sure the board had all of the facts so it could make a careful and informed decision.
Boards of Delaware companies have a duty of care which means they must make informed, prudent and good faith decisions. This clearly did not happen here.
What law firm is advising this board?
Or is the board even taken good legal advice?
It doesn’t look like it.
And now the board is compounding its failures by insisting that there is no possibility for Jensen’s return as CEO.
Why is it in the best interest of the company to foreclose the possibility of Jensen’s return and to do so before all of the facts are known? This is yet another breach of their duty of care.
Furthermore, the board has launched an investigation whose scope is unknown. Investigations can be extremely damaging to a company and should be carefully targeted to address whatever facts need to be known rather than be overly broad in scope.
In short, this looks like a series of major governance failures by directors that panicked due to headlines in the media. They likely felt compelled to do something because they were afraid of looking bad in the media, not because it was the right thing for them company.
They couldn’t stand the heat.
The board’s conduct here is shocking for a company of this scale and importance to our country and the world at large, particularly at this moment in history.
$STRC getting hammered today, worse than BTC despite buyback support

robinhood:0xb8dbf92f9741c9ac1c32115e78581f23509916fd / $CHRN announce neocloud deal (up to $7.B total contract value) with "leading AI lab" (typically Anthropic) at $21M/MW annually
>Forming a new 50/50 development partnership with private developer STN to build a DC in Odessa TX (each company contributes $390M in value for 50% interest)
>Campus will serve a leading frontier AI lab, initial phase of 65MW in 1H27 with ROFO on remaining 285MW (up to 350MW total)
>TCV of $7.5B over 6-years, substantial portion backstopped by credit support from IG tech company
>Additional financing of $750M to be $250M of equity + $500M convertible preferred
>Investors include the AI lab, Nutanix, Empery Digital and unnamed infra storage company
>Part of the equity to be issued via a note held by APLD (in June CHRN signed unsecured promissory note with APLD for $100M, was about ~50% drawn as of last quarter), converts to CHRN equity Q4 2026
>Power: STN’s model is on-site generation + battery + utility hybrid. They have 2MW operational since July with a utility feed and dedicated power subsidiary (RXT Power LLC). The 65MW initial phase is under ERCOT’s 75MW large-load threshold, sohould be on a standard interconnection path and out of the Batch Zero queue entirely.
>In Texas, regulator TCEQ started re-issuing air permits yesterday starting with $SPCX. Meanwhile the governor-elect has said that any moratorium will include a carve-out for already-permitted projects. Should be an interesting next 2 months.

$BLSH +9% pre-market
>Authorizes $300M share buyback
>Q3 EBIDTA/revenue beat
>Lowers full year to low end of previous rev/ebidta guidance
>Equiniti on track to close January 2027 along with the $1.85B of assumed debt
>The buyback authorization appears to be about 1x annual pro forma pretax FCF after the M&A closes. Will be interesting to hear on the call how they plan to pay for it.
>Call at 8:30am


Sounds to me like $NSCL is the marginal loser from $NVDA changing commitment plans.
Although maybe that's well known already given the IPO push-out/ scale-down and delays in WV, UK, TX etc.
Jensen said in April 2026:
“If we didn’t support Nscale, they wouldn’t be where they are today.”
We did exit $AKER.NO (owns ~1/4 of NSCL) last week to save powder for higher beta, more US-focused names. Happy to revisit AKER (a great company) at a later date.
6
29
7,259
"The most important part of the financing that we have to review in detail to make sure it is the right thing, is focusing on the Powered Shells. Powered Shells is such a critical structure in terms of building out those data centers, so they may need the assistance. So we will look at that as probably one of our top priorities."
🚨$NVDA cuts neocloud support plans down $1B q/q and adds tighter language around conditions; removes revenue share language from last quarter; adds new language that certain commitments "could be reduced or eliminated" if contingencies are not satisfactorily resolved. Cuts previously disclosed 2028 capex $1B to zero (sounds like a project pushout or cancellation).
Now says commitments take effect "only if the neoclouds secure financing to purchase the infrastructure products and the related compute capacity is deployed, made operational, and accepted by us."
Previous language: "We continue to make commitments....Under these agreements we will earn revenue on upfront sale of our infra and if certain criteria are met, we will participate in revenue share."
Re: secondary equity investments, future commitments fall from $25B to $20B but 2028 plans rise from $3B --> $11B. Unclear if this is pushouts from 2027 investments not made (such as Figure AI).
Bottom line: Total commitments grew 41% QoQ, driven almost entirely by a surge in 2028 supply/capacity commitments and long-dated data center leases, but the new contingency clause means a large portion is conditional on neoclouds securing external financing.
Also 10-Q to arrive "in coming weeks" seems like a delay.


🚨$NVDA raises F28 guidance from +70% to +75%
(Recall that NVDA had never given full year guidance at the end of FQ2 as they did last quarter. Turns out even that was too low. Surprising.)
🚨$NVDA cuts neocloud support plans down $1B q/q and adds tighter language around conditions; removes revenue share language from last quarter; adds new language that certain commitments "could be reduced or eliminated" if contingencies are not satisfactorily resolved. Cuts previously disclosed 2028 capex $1B to zero (sounds like a project pushout or cancellation).
Now says commitments take effect "only if the neoclouds secure financing to purchase the infrastructure products and the related compute capacity is deployed, made operational, and accepted by us."
Previous language: "We continue to make commitments....Under these agreements we will earn revenue on upfront sale of our infra and if certain criteria are met, we will participate in revenue share."
Re: secondary equity investments, future commitments fall from $25B to $20B but 2028 plans rise from $3B --> $11B. Unclear if this is pushouts from 2027 investments not made (such as Figure AI).
Bottom line: Total commitments grew 41% QoQ, driven almost entirely by a surge in 2028 supply/capacity commitments and long-dated data center leases, but the new contingency clause means a large portion is conditional on neoclouds securing external financing.
Also 10-Q to arrive "in coming weeks" seems like a delay.
notable that the higher guide includes what sounds like some caution around "data center readiness" and "customers access to capital"

Q "Why are you confident enough to raise the guide?"
A: "We took a lot of time working into both our demand that continues to grow, as well as our additional supply that we are able to provide to our different customers. Those two things continue to give us more and more growth. Additionally, we did look at an assessment in terms of the current export controls, and we're still going to spend some time studying those to see the different pieces of it. But we feel confident that we can do the 75%."
1
4
1,735
🚨$NVDA cuts neocloud support plans down $1B q/q and adds tighter language around conditions; removes revenue share language from last quarter; adds new language that certain commitments "could be reduced or eliminated" if contingencies are not satisfactorily resolved. Cuts previously disclosed 2028 capex $1B to zero (sounds like a project pushout or cancellation).
Now says commitments take effect "only if the neoclouds secure financing to purchase the infrastructure products and the related compute capacity is deployed, made operational, and accepted by us."
Previous language: "We continue to make commitments....Under these agreements we will earn revenue on upfront sale of our infra and if certain criteria are met, we will participate in revenue share."
Re: secondary equity investments, future commitments fall from $25B to $20B but 2028 plans rise from $3B --> $11B. Unclear if this is pushouts from 2027 investments not made (such as Figure AI).
Bottom line: Total commitments grew 41% QoQ, driven almost entirely by a surge in 2028 supply/capacity commitments and long-dated data center leases, but the new contingency clause means a large portion is conditional on neoclouds securing external financing.
Also 10-Q to arrive "in coming weeks" seems like a delay.
"We continue to work closely with our infrastructure capital partners to stand up the financing platforms. These partners are instrumental in financing the build out of AI infra. As we advance this work, we will remain thoughtful and how we participate and disciplined in how we commit capital. As the market matures and additional capital becomes available, we are rigorously evaluating future investments, commitments and guarantees. NVDAs ability to co-design across compute, networking, algos and software are unmatched."
$NVDA China revenue in 3Q was $11B (Customers headquartered in China), 9.5% of total
>YTD is $23.5B (~8%)
>DC hopper (H100, H200s) shipments to China was $2.4B of rev in 3Q
$NVDA +4% AH
CORZ +7%, IREN +6%, APLD +5%, CIFR +5%, VRT +5%