

Research on economics, history, and tech @Ryan_Research | Special focus on Ireland
Joined October 2012
- Tweets100K
- Following3.7K
- Followers12.9K
- Likes64.7K






Pinned Tweet
Just dropped an eBook/PDF of “Money by Vile Means.” Nowhere else will you get:
- What Bitcoin actually is (why it's corrupted)
- Debunked myths of decentralization
- Hidden stablecoin endgame = shadow central banking
If you're tired of the hype, grab it now.
(link below)

Peter Ryan retweeted

My initial S-1 thoughts:
As I expected, Anthropic is still firmly unprofitable. But, to their credit, they've significantly reduced compute costs as a % of revenue, leading to much narrower losses. On first look, there is a plausible and imminent path to profitability. This is impressive.
However, the meat of the document begins at page 161, under "liquidity and capital resources." There, we learn where the true compute costs have been hiding: future compute purchase agreements.
As of June 30, Anthropic has signed roughly $587 billion in compute leases and minimum purchase commitments that haven't begun. It has since signed $245 billion more, resulting in more than $800B in future compute costs. None of these costs have made their way onto the income statement yet. But they will, and when they do, the profitability picture will look completely different.
Anthropic acknowledges how precarious these agreements are. They point out that their compute providers (on whom they also rely for financial support) also sell services that "compete with ours." As a result, these providers/competitors may eventually force them into onerous agreements. This is something I've expressed concerns about for a while, and it's nice to see Anthropic openly recognize it.
That's why Anthropic admitted their most significant strategic decision: They're about to initiate "substantial capital expenditures." So far, they've spent zero. Why the change? Because they know they can no longer rely on leasing compute, "the magnitude and timing" of which are "inherently uncertain." So, they're going to build their own compute, which will, in their words, "change the cash flow profile of our business." I.e. make it severely negative.
It's possible that this is why they want to go public now. Since these costs have not yet "come online," they can be left as footnotes at the bottom of the document. But very soon, that won't be possible.
In sum, Anthropic's income statement is not telling you the full picture. To the company's credit, they spared us the accounting gymnastics of stripping out training costs in their non-GAAP adjustments. That would have been offensive. Still, the most important numbers aren't getting the requisite attention.
I encourage you to start at page 161 for a more complete understanding of what's going on.
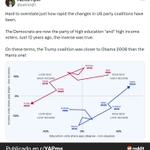
The lumpenprole right vs. the aristocratic left.
The 19th century connotations of the right and left have swapped in the past two decades.


100% @TheStalwart - "So if you want to understand capitalism, you need to be talking to small business owners, portfolio managers, and Marxists. Nobody else can really talk about it with any substance."
perfect cartoon on ideology that blinds most others: @ZackMaril

Good list

Who should you follow on China tech?
One great place to start is the brilliant guests who’ve been on my High Capacity podcast—now at 20 episodes!
Here they are and the topics we covered:
1. Georg Stieler (@GeorgStieler) — China’s industrial robotics revolution
2. Tu Le (@SinoAutoInsight) — China’s EV industry and global competition
3. Grace Shao (@Gracemzshao) — China’s AI ecosystem and tech giants
4. Lei Xing (@leixing77) — Autonomous driving and robotaxis
5. Afra Wang (@Afrazhaowang) — China’s tech culture and entrepreneurs
6. Kevin Xu (@kevinsxu) — China’s rise in open source
7. Tom Wang (@Xianbao_QIAN) — Chinese AI models, open source, and agents
8. Rui Ma (@ruima) — China’s tech strengths and weaknesses
9. Zixuan Li (@ZixuanLi_) — Inside Zai and China’s GLM models
10. TP Huang (@tphuang) — AI chips, energy, and industrial supply chains
11. Paul Triolo (@pstAsiatech) — China’s semiconductor industry
12. Ruby Wang (@RcjWang) — China’s AI healthcare and biotech revolution
13. Matt Sheehan (@mattsheehan88) — China’s evolving approach to AI safety
14. Nathan Lambert (@natolambert) — Frontier AI, open source, and regulation
15. Abigail Coplin — China’s biotech rise and innovation ecosystem
16. Fengming Lu (@FengmingLuPE) — How China really built its EV industry
17. Zilan Qian (@ZilanQian) — China’s hidden AI economy
18. Alvin Wang Graylin (@AGraylin) — US-China AI competition and cooperation
19. Kendra Schaefer (@kendraschaefer) — China’s AI regulation and governance
20. Sunny Cheung (@SunnyCheungky) — China’s humanoid robots and supply chains
All episodes available on:
- YouTube: youtube.com/@highcapacitypod…
- Apple Podcasts: podcasts.apple.com/us/podcas…
- Spotify: open.spotify.com/show/6kafwx…

Capitalism is an “accidental phenomenon” as Reinert said.
And in a sense, capitalism only exists as a shadow of Marxism because Marxism had to de facto define what it was critiquing.
There were no card carrying self-described zealots of capitalism before Marxism.


This happened parallel to tech bros wanting a more dominant influence on the government

Concentration grew through the latter-half of ZIRP, up until the ill-fated WeWork IPO — a high profile warning about the "growth at all costs" mentality.
From 2019 to 2022, VC concentration fell as investors squeezed down into Seed, searching for a clean slate. New frontiers, and a reset on price inflation; although capital supply meant prices remained high.
The market bifurcated in 2022, as smaller LPs suffered a liquidity crunch which larger LPs barely noticed. The market has quickly been dominated by scaled allocation, chasing easy narratives.
As a result, 2023 to 2026 has seen successive ATHs in market concentration, as LP capital has crowded into megafunds and obvious growth opportunities.
Credit to @harmonic_ai for the data.

Peter Ryan retweeted

Concentration grew through the latter-half of ZIRP, up until the ill-fated WeWork IPO — a high profile warning about the "growth at all costs" mentality.
From 2019 to 2022, VC concentration fell as investors squeezed down into Seed, searching for a clean slate. New frontiers, and a reset on price inflation; although capital supply meant prices remained high.
The market bifurcated in 2022, as smaller LPs suffered a liquidity crunch which larger LPs barely noticed. The market has quickly been dominated by scaled allocation, chasing easy narratives.
As a result, 2023 to 2026 has seen successive ATHs in market concentration, as LP capital has crowded into megafunds and obvious growth opportunities.
Credit to @harmonic_ai for the data.
For every $100 the seven megafunds invested between 2005 and 2023, only about $11–19 matched the market-wide distribution of capital.
So far in 2026, it's about $38.
This group has gone from a set of differentiated firms to something that looks more like a VC megacap index.
Data sourced from @harmonic_ai.

You can’t have a house because rich people need 3 mansions


Capitalism is premised on a supplier creating more value from its use of productive factors (land, capital, labour) than the sum of those parts proven by selling said newly created value for a profit to a demander.
What we have today is a system premised on financiers extracting money from the real economy to spread that money among suppliers who create negative net new value proven by their inability to make a profit of demanders.
Before, demanders dictated suppliers. Now, financiers dictate suppliers with absent demand.
Parasite economics.


If you want to learn more about perps, then learn from the father of perps: BitMEX's Arthur Hayes.
He said that traders love perps because they offer more leverage and liquidity: lots of sloshing to enable 100x degen trades.
However, being a degen merchant (BitMEX) means you eventually shoulder the risk of offering 100x leverage because there is not enough actual dry powder to cover what the degen merchant is liable for. When loser losses exceed the degen merchant's capacity to payout winners, the degent merchant is at risk of going bust.
To avoid going bust, Hayes added the socialized loss system which uses funds from winners on his platform to backfill the losses. Hayes is correct, in the narrow sense, that his socialized loss system is a necessary aspect for platforms like his to persist and that other platforms must converge to it out of competitive pressure.
While he may have created a short-term solution, mostly for his own firm's survivability, in the broad sense, he also created a more systematic risk. In the long-term, he introduced more fragility.
The honest look here is that Hayes transferred his risk of greedily/stupidly giving schmucks 100x leverage. The reason offering 100x leverage is not commonplace is because it's stupidly risky. Hayes is not a genius for noticing offering lots of leverage could result in him attracting a lot of dumb money he could skim off of. He did not innovate anything. He just got other schmucks to shoulder his risk for him without realizing he also created a new system-wide risk (or perhaps dgaf).
Eventually, a negative market shock will come and be big enough to overwhelm the socialized loss system. Winners who bet right will not tolerate their risk being correlated to losers who bet wrong. They will start yanking liquidity out of the platform therefore making shock worse. As more shock spill overs occur, the fire sale / exchange run loop spirals.
If perps expand into tradfi (i.e. big quantity and wide interconnectedness), what will happen is that 1.) competitive forces will race to the bottom to supply maximum leverage, 2.) socialized loss systems will become default to protect platforms in short-term, 3.) isolated platform risk will be transferred to system-wide risk creating more fragility, and 4.) a big enough shock will expose this fragility and cascade into a full-blown financial crisis because no one realized how wide the exposure was in our future crypto-tradfi interwoven market.
As Vítor Constâncio, Vice-President of the European Central Bank, said, "In pursuit of excess returns, market participants engage in excessive leverage without internalizing systemic costs of their risk-taking behaviour. These comprise spillovers to counterparties and financial networks or asset price declines triggered by fire sales. A large and growing literature supports the conclusion that these systemic externalities of excessive leverage call for macroprudential policies that restrict the use of leverage pre-emptively, as a way to improve general welfare."
The cryptoids that have taken over the Trump admin will not provide such sufficient policies. Which means we are sprinting towards our global financial market turning into one big BitMEX that is leverage-maxxing until it starts rekt-maxxing as many related parties as possible.
I don't see what productive purpose perps and the associated crypto-like "innovations" offer other than creating neo-casinos that if anything extract money that could have otherwise gone into the real economy and create more risks that eventually harm the real economy down the road. Speculating != investing.
cryptohayes.medium.com/adapt…


Blockchain aside. One thing I feel pretty strongly about is that if you're a markets person, you should probably invest a little bit of time thinking about perpetuals, and how they work. Anyway, Sub to the newsletter here. bloomberg.com/account/newsle…
Innovation is when middle men steal your grandparents' retirement money to prop up blob tech


This chart shows the key risk to the AI trade, and it's missing from the latest revenue announcements.
The AI boom is fundamentally driven by a top 1% of companies that drive 80% of spend. Within that top 1%, 80% are venture-backed.
That's all fine if the AI trade works out, and if, as some prominent investors say, everyone wins.
But if it doesn't work out, then we have a cascading effect of large customers simultaneously pulling back their AI spend.

Peter Ryan retweeted

Everyone predicted this except The Management.


This was so foreseeable (indeed my early prediction when ChatGPT came out) but a lot of tech people have a hard time understanding that the hypothetical enriching use of a tech loses out to the lazy corner cutting use 99.9% of the time theguardian.com/technology/2…

I was reflecting on this the other day with the Irish budget overspending driven by healthcare which is driven by old people.
When it comes to increasing entitlement costs, modern governments just have no way of dealing with an "is what it is" problem. They never expected there to be this many old people, living for so many extra decades, and consuming so much healthcare services to do so.
It's hard to imagine an obvious solution to this.


German State Secretary for Foreign Affairs Paul von Hintze: "What do we want in the East? The military paralysis of Russia. The Bolsheviks are taking care of this better than any other Russian party, without our contributing a single man or a single penny. We cannot demand that they or other Russians should love us for the fact that we are squeezing their country like an orange...That is exactly what we are doing: we are not co-operating with the Bolsheviks, we are exploiting them. That is what politics is about."

After the Bolshevik clear victory by late October of 1917, the German state transferred another 17 million marks ($73 million in today's USD) to the Bolsheviks.

Parvus (Helphand) also indicated that the Bolsheviks "was not supported by the majority of the [Russian] people: 'it was the victory of one minority over another minority'...In addition...the party had to carry with it the 'dark masses'...[or] Lumpenproletariat - which were now threatening the stability of the new order."
