

40+ years helping financial professionals stay ahead of market trends. We do not reply to DMs/comments. For support, visit https://teapawt.org/t.co/nXEDyR00YV.
- Tweets26.2K
- Following291
- Followers122K
- Likes3.2K






ALT Blue and black wavy graphic design on the left. Text reads, "Back to the Future: Tracking LP Portfolio Composition Over 20 Years." Logo at the bottom right says "Article Audio.


ALT FactSet Insight article titled "When No Portfolio Satisfies the Mandate: Using AI to Diagnose Optimization Infeasibility." The article discusses using AI for diagnosing portfolio optimization challenges. Author: Georgi Mitov.


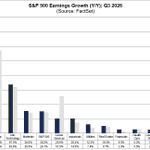
ALT Bar chart titled "S&P 500 Earnings Growth (Y/Y): Q3 2026 (Source: FactSet)" depicting earnings growth percentages. Categories listed are Energy, Information Technology, Materials, S&P 500, Communication Services, Industrials, Utilities, Real Estate, Financials, Health Care, Consumer Staples, and Consumer Discretionary, with Energy showing the highest growth and Consumer Discretionary the lowest. Two color tones differentiate today's and September 30, 2026, data.

ALT Here's a description for the image: "Screenshot of a FactSet Insight webpage featuring an article titled 'Back to the Future: Tracking LP Portfolio Composition Over 20 Years.' The article discusses the focus on LP portfolio composition through market analysis. A 'Read More' link and the name Colin Devereaux are also visible."

ALT Blue and black wavy graphic design on the left. Text reads, "Back to the Future: Tracking LP Portfolio Composition Over 20 Years." Logo at the bottom right says "Article Audio.