
TwoFiftyTwo is an AI Investment Analyst for Hedge Funds and Asset Management. https://teapawt.org/t.co/Lj07aRSSSY
Joined March 2026
- Tweets22
- Following8
- Followers2
- Likes0
Excited to share that TwoFiftyTwo is now SOC 2 Type II certified.
This milestone reflects our commitment to protecting customer data, strengthening our security practices, and building trust with our customers and partners.
Onward.
#SOC2 #Security #Compliance

2
25
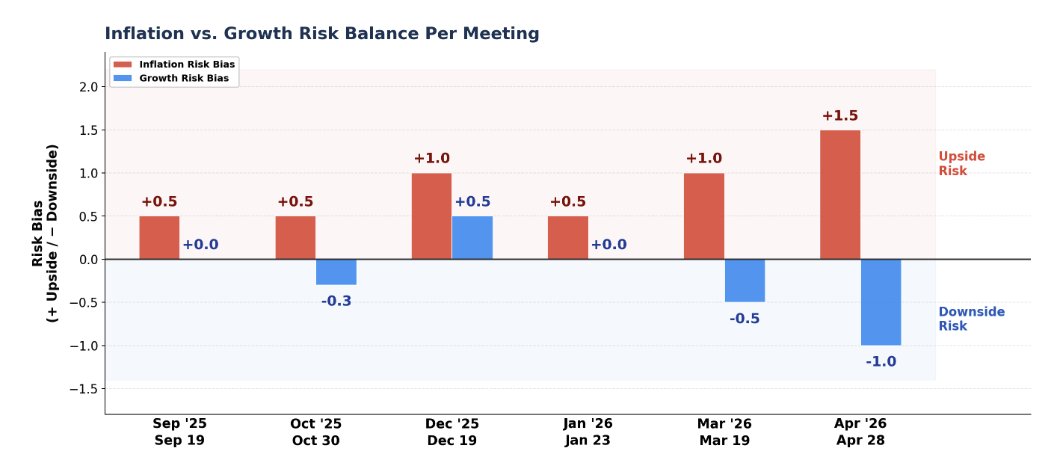
BOJ is out!
TwoFiftyTwo reads the meeting as clearly hawkish versus recent decisions, but the policy mix is getting harder: the Bank is increasingly worried about inflation staying too high, even as growth risks soften.
Higher inflation, lower growth - not an easy spot to tighten into.

Today we launched Automations for TwoFiftyTwo.
Automations let you run any task on a schedule.
Want a tailored morning summary every day? ✅
Want a daily scan for new trade ideas? ✅
Want regular monitoring of key market levels? ✅
Here’s the morning summary I got from my TwoFiftyTwo Automation today.
What will you use Automations for?

China’s March trade balance came under pressure as higher oil prices lifted import costs.
We used TwoFiftyTwo’s AI to assess what sustained higher oil prices could mean for China’s trade balance through the rest of 2026.

What happens if Starmer gets ousted as PM. We had TwoFiftyTwo's AI analyse the potential market implications if he leaves.


As the war drags on, oil is tuning out hawkish headlines… but reacting harder to dovish ones...Tracked by TwoFiftyTwo's AI

Stressed?
We asked TwoFiftyTwo's AI Analyst to look at indicators of stress across Macro to see which markets are more stressed than others, and analyse the biggest dislocations of stress vs past 3yr averages.
TLDR:
Volatility markets are pricing uncertainty.
FX is repricing structural shifts.
Rates are signalling capital rotation.
Credit… is staying calm.

4) Credit Isn’t Buying the Panic (Yet)
Despite:
• Oil up ~90% YTD
• European gas nearly doubled
• Volatility elevated
Credit spreads are… basically unchanged.
iTraxx and CDX HY are nowhere near the stress implied by volatility markets.
Either:
(a) Credit is lagging and will widen
(b) Strong technicals (carry demand, low defaults) are masking the risk
13
3) Cross-Currency Basis Says “Repatriation,” Not Stress
USDJPY 5Y xccy basis has tightened significantly — the opposite of what you’d expect in a dollar funding squeeze.
Instead of hedging USD exposure, Japanese investors appear to be bringing capital home.
With JGB yields at multi-decade highs, the incentive to stay abroad is falling.
8
2) USDJPY Skew Breakdown
USDJPY risk reversals are ~1.45σ away from normal — but in the wrong direction for a risk-off environment.
Historically, JPY strengthens as a safe haven when volatility rises.
That relationship has broken down.
Why?
The BoJ is tightening into inflation, and JPY is behaving less like a haven — more like a macro/inflation currency.
7
1) Vol-of-Vol Leading Vol (VVIX > VIX)
VVIX is printing the highest z-score across the entire cross-asset universe, even above VIX itself.
This typically happens when markets aren’t just uncertain about how much volatility is coming — but what kind of regime we’re entering.
The confirmation? Broad demand for vol of vol across FX (EURUSD, GBPUSD, USDJPY butterflies all elevated).
7
What happens to 2Y yields if oil drops back to pre-war levels?
We asked TwoFiftyTwo’s AI what a move in Brent to $72 could mean — here’s what it found 👇

🇬🇧 UK 2Y: highest beta in G10
−56bps on Brent → $72
R²=0.37 / t=3.31
Largest move, most oil-sensitive curve.
1
16

