

Led AI at Cruise and Amazon. Helped launch the first commercial robotaxi in SF. Now building Rivo. Self-driving finance.
Cupertino, CA
Joined September 2012
- Tweets400
- Following433
- Followers316
- Likes788




Pinned Tweet
Today, I am excited to share that @TryRivo has raised $3.1M in total funding, including a $2.7M seed round, to build the AI layer for personal finance, starting with automated cash management.

What happens to saving when the cost of everyday life keeps rising?
I see this as more than a question of how much people earn or spend. It's also about how much of their income is already committed to essentials like rent, groceries, and monthly bills, leaving less money to put aside.
This pressure is reflected in a Yahoo Finance and Marist Poll survey, which found that 47% of Americans identify the cost of living as their biggest obstacle to saving. When so much of an income goes towards everyday expenses, finding extra money to save isn't always possible.
Making better use of existing cash won't solve the affordability problem. But even when saving more isn't possible, the money already in your account may be able to do more than sit there.
Not all of it is needed at the same time. You need enough readily available for rent, bills, and everyday expenses. Cash beyond that doesn't have to stay idle. If there isn't any, there's nothing to move, and that's okay.
That's why we built @TryRivo around the cash people already have. It understands your cash flow, respects your chosen minimum balance, and identifies eligible idle cash in your existing bank account. It then puts that cash to work in U.S. Treasury bills and brings it back before your upcoming expenses are due.
You can keep the money you need for everyday expenses available, while eligible excess cash works in the background.
(Source: finance.yahoo.com/personal-f…)

You can consume a lot of tokens without creating much value.
That becomes particularly relevant as companies begin treating AI usage as a measure of workplace productivity.
A recent Washington Post article highlighted how some organizations are tracking employees' time spent on AI platforms and the number of tokens they consume. It also featured Stanford researcher Arvind Karunakaran's observation that high AI usage doesn't necessarily translate into meaningful results.
(source: washingtonpost.com/business/…).
The problem is that when usage itself becomes a target, people start optimizing for the metric rather than the outcome. Activity increases, but value doesn't necessarily follow.
Financial technology has a similar problem: measuring engagement instead of actual value.
Many financial apps treat daily logins and frequent interactions as signs of success.
But why should a financial app need your attention every day to prove it's useful?
At @TryRivo, we believe the best financial tools shouldn't demand more of your attention. They should make your financial life work better, even when you're not thinking about them.

You may know how to earn a return on your cash. But do you know how much of it you can actually afford to put to work?
The answer isn't just about how much money you have. It's about understanding what that money needs to do, and when you'll need it.
Some of your cash needs to stay within easy reach for rent, bills, emergencies, and other upcoming expenses. But some may sit untouched in your bank account for weeks or even months.
That money doesn't necessarily need to sit idle. It could be earning a return elsewhere, as long as it's available when you need it.
Millions of Americans are already putting this idea into practice through money market funds. These funds invest in short-term debt securities, including Treasury bills, giving individuals and institutions a way to earn a return on cash without committing to long-term investments.
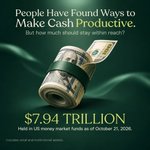
The scale is significant. According to the Investment Company Institute (ICI), U.S. money market fund assets reached approximately $7.94 trillion for the week ending October 21, 2026. That's across both retail and institutional investors, highlighting just how important cash management has become (source: ici.org/research/stats/mmf)
But knowing where to put your cash is only part of the equation.
The bigger challenge is knowing how much you can actually afford to move. Your bank balance doesn't tell you how much is already committed to upcoming bills, how much you might need for unexpected expenses, or how much can safely be put to work.
That's the problem we're working to solve at @TryRivo.
We believe your money should work around your financial life, not the other way around. Rivo helps you understand what's available to put to work, while keeping your everyday banking and upcoming expenses running as usual.

Rivo’s demo day got a little scary this week. 🎃
Pirates, skeletons, a ghost, and one CEO with an Error 404.
Happy Halloween from the humans building self-driving finance. 👻

A fintech product can solve a real problem and still fail to change customer behaviour.
Because building a solution is only half the equation. The other half is getting people to act on it.
Consider idle cash.
Many people know their money could be working harder for them. They might even recognize the value of moving beyond the default option of leaving everything in a bank account.
Yet awareness doesn't automatically translate into action. People have competing priorities, established habits, and understandable concerns about financial products they don't fully understand.
Even when a product offers a clear benefit, getting someone to try it and making it valuable enough for them to keep using it is a different challenge altogether.
For founders building consumer fintech products, this is worth thinking about.
Is the value clear enough to motivate action? Are we making it easy for people to get started? Are we building the trust required for them to change an established financial habit?
These are questions that go beyond whether the product itself works.
A product can solve the problem on paper. Its real impact depends on whether people understand it, trust it, and ultimately change their behaviour because of it.
A financial product’s advertised interest rate tells you what you could earn. Its business model helps explain what you actually receive.
Bank sweep programs are a good example.
When a brokerage moves uninvested cash into participating banks, the brokerage may receive compensation tied to those deposits. In many arrangements, that compensation comes from a portion of the interest generated, reducing the rate the customer receives.
Consider a hypothetical example: You have $10,000 in a sweep account. The underlying bank deposit generates interest at a gross annual rate of 4%, before the brokerage’s share.
- The deposit generates $400 in interest over a year.
- The brokerage retains $100 as compensation.
- You receive the remaining $300, equivalent to a 3% annual return.
These figures are illustrative, not representative of a particular brokerage or a standard industry arrangement.
The point is that the economics behind a financial product matter just as much as its headline rate.
How does the provider make money? How is the interest allocated? What costs or incentives influence the arrangement?
These are questions worth asking about any financial product.
At @TryRivo, we believe customers should understand how their money works and how the service managing it makes money.
The goal isn't just to understand what a financial product promises to earn. It's to understand the economics behind that promise.
(source: investor.gov/introduction-in…)
AI is changing how money could move between financial institutions.
Imagine AI agents that automatically identify idle cash, compare available returns, and move money to where it can earn more. For customers, that could mean less cash sitting in low-yield accounts. For financial institutions that rely on deposits for funding, it could mean a new challenge.
As Wall Street veteran Torsten Slok wrote in a recent note, AI-driven cash management could make deposits more mobile, putting pressure on financial institutions that rely on them for funding.
Major financial institutions are already responding to this possibility. JPMorgan Chase and Charles Schwab have restricted unauthorised AI agents from accessing customer accounts, with Citi and Bank of America taking similar steps.
But automating money movement and giving an unauthorised agent access to your bank account are two different things.
That distinction was a key consideration when building @TryRivo.
Rivo takes a permission-based approach. You connect your bank through Plaid with your permission, keep your existing bank account, and set the minimum balance you want to maintain.
The shift towards AI-driven money management is already underway. How financial institutions respond, and how these tools access customer accounts, will shape what comes next.
Sources:
ft.com/content/f49c8e39-f07f…
barrons.com/advisor/articles…

Your money can be fine and still take up mental space.
Your bills are paid. Your savings are growing. You have enough in your checking account for what’s coming up.
And yet, you keep checking your balance.
Should you move some cash? Did you already make that transfer? Could your idle money be earning more somewhere else?
You might compare interest rates without any real intention of switching. Or leave cash sitting in checking because you haven’t decided what to do with it.
A few days later, you’re back to checking, comparing, and reconsidering the same decisions.
None of this is particularly difficult. But it all takes something: your attention.
Because managing money isn’t just about having enough. It’s also about keeping track of where it is, deciding what to do with it, and making sure nothing slips through the cracks.
Sometimes, you’re not checking your accounts because something is wrong.
You’re checking because you want to make sure everything is still right.

AI agents are moving from recommending financial decisions to making them.
That shift creates a much bigger challenge than simply making agents capable of taking action.
When software can trade stocks, move money, or manage a portfolio, how much autonomy should it actually have?
Users need to know what an agent can access, which actions it can take independently, where approval is required, and how to intervene when something goes wrong.
At @TryRivo, this is an important part of how we think about building AI for cash management. The goal isn’t just to automate financial tasks. It’s to make that automation understandable, predictable, and controllable.
These aren’t settings to add later. They’re fundamental product decisions that shape how an agent behaves when instructions are ambiguous, circumstances change, or decisions have unintended consequences.
The next frontier in agentic finance isn’t just building agents that can act. It’s designing the controls that make their actions trustworthy.
A financial recommendation can be right and still make no difference if nothing happens afterward.
Financial tools have made it easier to understand our money. We can see where it goes, compare our options, and get increasingly sophisticated guidance. These capabilities solve real problems.
But they leave an important part of financial management to the user: turning a decision into action and keeping up with it as life changes.
This is the gap I wanted to solve.
Knowing what to do with your money is one problem. Making it happen consistently, while managing everything else in your life, is another.
While building @TryRivo, we tackled that challenge through automated cash management. Rivo identifies cash a user can put to work, moves it into short-term U.S. Treasury Bills, and brings it back before they need it. Users don’t have to keep checking balances or remember to move money manually.
Making this reliable is the difficult part. Software has to account for real spending needs and the timing of incoming and outgoing money.
Producing a recommendation is one thing. Executing it without disrupting someone’s access to their cash is a different engineering problem.
The broader opportunity is to build financial software that can handle more of this work as people’s circumstances change.
AI is getting better faster than people are becoming comfortable giving it authority over their money.
We’re already comfortable using AI for everyday tasks. We ask it questions, use it to understand information, and increasingly rely on it to help with financial decisions.
But there’s a meaningful difference between asking AI for advice and giving it permission to act.
TD’s 2026 AI Insights Report found that 78% of Americans use AI-powered tools, while 55% now use AI to help manage their finances. Yet only 18% say they would trust AI to make financial recommendations independently.
That gap is important.
A system becoming more capable doesn’t automatically mean people are ready to give it more authority.
Better models can make AI more capable. But capability has to translate into earned trust before it can translate into meaningful autonomy.
And that creates a different engineering challenge: building systems that people don’t just believe can make good decisions, but are comfortable letting them make those decisions.
In finance, that trust is built in the details: transparency, reliability, safeguards, and what happens when things don’t go as expected.
The future of financial AI won’t just be about what AI can do. It will be about what people are willing to let it do.
AI is getting very good at answering personal finance questions.
But managing your finances isn’t a question and answer problem.
Your financial situation is constantly changing. Your income, spending, goals, investments, and upcoming expenses all move over time.
A new NBER study on AI and personal finance highlights some of the limitations of today’s approach.
Researchers found that LLMs can produce useful financial recommendations, but the outcomes can vary significantly depending on the person using them and how they interact with the model (source: nber.org/papers/w35574).
That makes me think the next step for financial AI isn’t just better answers.
It’s AI that understands your financial context, knows what you’re trying to accomplish, and can actually take action as things change.
Instead of asking, “What should I do with my money?”
Imagine having an AI that understands your financial situation and can continuously work toward your goals.
That’s the direction we are taking at @TryRivo.
From financial AI you talk to, to financial AI that actually does things for you.

Ambrish Tyagi retweeted

AI agents are already moving people's money while they sleep.
"Even though we're doing this money movement autonomously, you have a personal finance agent in your pocket. You can ask it questions."
"The challenge is trust. It's people's money, where it's going. Giving them full visibility and accountability all the time is the biggest challenge we're solving." — @AmbrishTweets
Would you let an AI agent move your money?
Changing financial behavior is one of the hardest problems in personal finance.
Not because people don’t know what they should do. Often, they do.
The harder part is getting the right things done consistently as circumstances change.
I recently joined Drew Rogers and Zach Fowler on the @stabledash podcast, where we talked about how AI could fundamentally change the way people manage their money.
A lot of the progress in financial AI so far has focused on helping people understand their finances, surface insights, and make better decisions.
That’s valuable. But I think there’s a much bigger opportunity ahead.
What happens when financial software doesn’t just tell you what to do, but can actually handle more of the ongoing work for you?
That’s already the direction we’re taking at @TryRivo with cash management.
Rivo connects to your existing bank account, identifies idle cash that can be put to work, moves it into short-duration U.S. Treasury Bills, and brings it back before your bills are due.
Users don’t have to constantly monitor rates, move money between accounts, or remember to do it themselves.
As AI agents become more capable, this can extend much further.
A personal finance agent could understand your financial situation, monitor what’s changing, and take appropriate action across different financial products and rails - moving money, optimizing cash, and handling financial tasks as your needs change.
That represents a much bigger shift than simply making financial advice better.
Today, most financial software waits for you to open the app, decide, and act.
The next generation could work in the background, handling more of the financial work on your behalf.
The more context AI has about your financial life, the more useful it can become.
Today, AI can answer questions about your money.
But imagine an AI that knows when your paycheck arrives, when your mortgage is due, which subscriptions renew each month, how your spending changes, how much cash you typically keep available, and what you're saving for.
That context matters.
If you have $20,000 sitting in your checking account, the right thing to do isn't simply to find the highest yield.
It depends on what that $20,000 is for.
Maybe your mortgage is due next week. Maybe you're about to pay your annual insurance bill. Maybe you like keeping $5,000 available for everyday spending. Maybe you're saving for a house.
An AI that understands all of this can make a much better decision than one that only sees your balance.
That's the shift happening in financial AI.
From answering questions about your money to understanding your financial life to actually helping manage it.
The goal isn't AI that knows more about you for the sake of knowing more.
It's AI that uses that context to make your money work better for you.

The next financial skill may not be knowing what to do with your money. It may be knowing what to tell an agent.
Imagine you want an agent to manage part of your cash. You might tell it:
Keep $10,000 in my bank account.
Don’t touch the money I’ve set aside for rent.
Never move more than $5K at a time.
If something unusual happens, stop and let me take over.
These aren’t instructions for every individual transaction. They’re context about how you want your money managed.
The agent can then figure out what to do as things change, while staying within the boundaries you’ve set.
That changes the role we play in managing money.
For a long time, being financially capable meant making the right decision whenever something needed to happen. As agents get better at acting on our behalf, more of that work moves upstream.
You define what matters. The agent handles the execution.
That’s the direction financial software is heading, and it’s a big part of how we think about @TryRivo.
One of the most widely followed economists on Wall Street just asked a question we've been thinking about since we started @TryRivo.
Torsten Slok, chief economist at Apollo, one of the world's largest asset managers, recently warned that AI agents could sweep consumer cash from bank accounts paying close to nothing into alternatives paying 3 to 5%.
At scale, he says, banks could lose a significant share of the deposits they rely on to fund loans. He's calling it an agentic bank run.
We've been calling it the inertia tax.
The gap between what your bank earns on your deposits and what you earn has existed for decades. It lasted because moving money was manual, deciding how much to move required effort, and nobody had time to keep doing it. Banks built their business model around that friction.
What Slok is describing at the systemic level is the same problem we saw at the household level: your bank counts on the fact that you're too busy to do anything about it.
That's changing.
It's interesting to see the conversation move from helping consumers get more out of their cash to thinking about what happens to the financial system when software starts doing this automatically.
The question now isn't whether agents will move money. It's whether they can do it safely, with cash flow awareness, bill timing, and the right guardrails.
That's the engineering problem we're focused on at @TryRivo.
We are building personal finance agents that act autonomously on behalf of the customers and are bank and rail agnostic. Agents decide the most optimal time and rail to transact given the particular circumstances.
Thanks for having me on the show, @stabledash!

"Not everybody needs to have a wallet or a stablecoin or a crypto in front."
"But we at @TryRivo are leveraging that and we'll continue to leverage that as an infrastructure." — @AmbrishTweets
The average @Chase or @BankofAmerica customer is "still dealing with fiat on the front."
"The money sitting in these big banks is still sitting in dollars, and we have to move it out when it's efficient and move it back."
"We rely on all these rails."
"The good thing with AI is sometimes you can predict and you don't need money immediately. So we can do this transfer in two days or same-day ACH."
When something changes at the last minute, "think of it like steering the car." That's when real-time rails like RTP and stablecoins matter.
People don’t usually decide to trust a financial product.
They decide whether to trust it based on what happens when they use it.
If a product moves or manages their money, users need to know it will behave the way they expect. The money moves when it should. The numbers make sense. Nothing unexpected happens.
Do that consistently over weeks and months, and something changes.
They stop questioning every interaction. They stop wondering what’s happening behind the scenes.
That’s how confidence builds.
The interesting part is that users don’t actually experience claims like “secure” or “reliable.” They experience whether the product behaves reliably when they use it.
And that matters even more with financial products because the thing being entrusted is something people can’t afford to treat casually.
Trust is less like a feature and more like a history.
Every time the product does what it was supposed to do, it adds another piece of evidence that the system can be relied on.
The boring moments are where that history gets built.
Trust isn’t something you ship. It’s something the product accumulates.

Some money becomes permanent cash without anyone deciding to keep it there.
An RSU vests, a bonus hits, or a tax refund lands in your account. At first, it feels temporary. You’ll figure out what to do with it.
Then a busy week becomes a busy month. Another month goes by.
Eventually, the money stops feeling temporary. It becomes part of the balance you see every day.
Nothing was decided. The money simply never left.
That’s the interesting part: financial decisions don’t always happen when money arrives. Sometimes, not making a decision becomes the decision.
A $50K bonus can arrive as money you haven’t figured out yet and slowly become $50K that feels like it has always belonged in your account.
Temporary cash can quietly become permanent idle cash.
