

Daily Alpha, Ecosystem Projects & Insights | 96% for $BTC || Channel: https://xitter.cf/t.co/vprTnZDjJD
Metaverse
Joined June 2025
- Tweets2.3K
- Following1.7K
- Followers2.8K
- Likes6.7K





Bitcoin Is Back Near $80K. What Are Altcoins Telling Us?
Bitcoin is back around $80K, but the more interesting signal this week is what’s happening around it.
Among CryptoRank’s most visited tokens, BTC, ETH and SOL were nearly flat. But further down the list, performance was all over the place: irys:native gained 202%, robinhood:0x000050e18ffa3f8f7ad170eb9cef160eb3ed1111 rose 34% and $ENA added 13.5%, while $RT fell 82%, $Q dropped 53% and several others posted double-digit losses.
That’s not the profile of a broad risk-on market.
If liquidity were rotating decisively from Bitcoin into altcoins, we’d expect participation to broaden across the market. Instead, gains are concentrated in a handful of names while many others continue to struggle.
So BTC sitting around $80K isn’t automatically creating an “altseason window.”
For now, the market looks selective rather than broadly bullish: Bitcoin is consolidating, while altcoin returns are being driven much more by individual catalysts than by a market-wide rotation.
The next thing to watch isn’t which small-cap pumps next, but whether market breadth starts improving alongside Bitcoin.

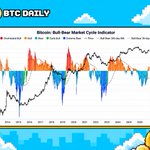
Bitcoin Is Still in Bear Territory. But the Cycle Is Starting to Shift.
Bitcoin’s Bull-Bear Cycle Indicator is still sitting in bear territory, but the latest data is starting to show small pockets of early recovery.
That puts BTC in an interesting position.
In the short term, the market is far from clear. $79K–80K remains the key support zone. Losing it would increase the risk of a deeper move toward $75K and potentially the low-$70Ks. On the upside, BTC still needs to reclaim $84K–85K, followed by $87K, before the current recovery starts looking more convincing.
But the cycle picture tells a slightly different story.
In previous cycles, the transition from bear to bull rarely happened in one clean move. Bear momentum weakened first, the indicator moved back and forth around neutral, and only later did a sustained bull phase emerge. That’s closer to what matters now.
The first small bullish readings are appearing, but they are not confirmation of a new bull run yet. They suggest the bearish phase may be losing momentum while the market searches for its next direction.
So I wouldn’t frame the current setup as “bull or bear” just yet.
Below $79K, downside risk remains open. Above $85K–87K, the recovery becomes much more credible. Between those levels, Bitcoin is still proving whether this is just another bounce or the beginning of a broader cycle shift.
With ETF flows and the next Fed decision ahead, confirmation matters more than prediction here.


Where Is Crypto VC Money Going in 2026?
Crypto funding in 2026 is sending a pretty clear message.
Payments leads with $2.94B raised, narrowly ahead of Prediction Markets at $2.90B. Exchanges and AI follow at $1.78B and $1.56B, while DeFi, RWA and broader blockchain infrastructure sit much lower.
But the two leaders tell different stories.
Payments has attracted capital across 100+ funding rounds, suggesting investors aren’t betting on just one winner. Capital is spreading across stablecoins, payment rails, settlement, wallets and cross-border infrastructure.
Prediction Markets are different. Their funding is much more concentrated, with a few large deals accounting for a meaningful share of the total.
The broader shift is more interesting than the ranking itself.
Crypto VC increasingly seems to favor sectors where there is already a clear path from usage → revenue → scale. Moving money, facilitating trades and providing financial infrastructure are easier business models to underwrite than another protocol competing mainly on narrative.
That doesn’t mean DeFi or RWA are dead. It means the bar for capital has moved higher.
In this cycle, having a strong narrative may get attention. Showing where the money actually flows is increasingly what gets funded.
🔥 TOP 5 CRYPTO GAINERS TODAY
@Magma_Finance magma-finance:native | @akedofun $AKE | @BitlayerLabs ethereum:0x6c76de483f1752ac8473e2b4983a873991e70da7 | @Alaya_AI $AGT | @irys_xyz irys:native
Today’s gainers are spread across DeFi, GameFi, AI and blockchain infrastructure, with no single narrative dominating the list.
A good reminder that even when the broader market is mixed, liquidity is still rotating into smaller pockets of strength.
Which one are you watching?

Bitcoin ETFs Just Bought $528M. So Why Isn’t BTC Going Up?
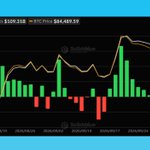
U.S. spot Bitcoin ETFs recorded $528M in net inflows in the latest session, bringing the three-day total to roughly $1.08B.
At around $84K per BTC, that’s roughly 6,300 BTC worth of demand in one day.
For comparison, miners currently produce only about 450 BTC per day. So ETF demand in that single session was equivalent to nearly 14 days of new Bitcoin issuance.
Normally, that sounds like a strong setup for price. But BTC briefly moved above $84.7K before falling back toward the low-$80Ks. That’s the part worth paying attention to.
ETF demand is strong, but for now, much of it seems to be absorbing existing sell pressure rather than pushing BTC into a new leg higher. There are still enough sellers around these levels to meet that demand.
Flows are also highly concentrated. BlackRock’s IBIT and Fidelity’s FBTC accounted for roughly 85% of the latest inflows, showing that institutional demand is still centered around the largest and most liquid products.
So I’d pay less attention to one big green ETF bar and more to what happens if these inflows continue. If BTC begins moving higher on similar inflows, it could mean sellers around these levels are finally being absorbed. But if hundreds of millions keep flowing into ETFs and BTC still struggles to move, selling pressure clearly hasn’t cleared yet.
That makes the next few sessions more important than the $528M headline itself.

Bitcoin Is Becoming More Than an Asset to Hold
Bitcoin doesn’t generate cash flow. There are no earnings, coupons or dividends built into the asset.
Yet that doesn’t mean capital built on top of Bitcoin can’t generate them.
Strategy offers an interesting example. With a BTC reserve worth tens of billions of dollars, its model suggests that relatively modest long-term Bitcoin appreciation can support dollar-denominated financial obligations without requiring the underlying BTC reserve to disappear over time.
That points to a broader evolution in how Bitcoin can be used.
Bitcoin’s supply is fixed by protocol, while new issuance continues to fall with every halving. The current block subsidy is 3.125 BTC, with roughly 164,250 new BTC issued per year, or about 0.82% of circulating supply. After the next halving, that flow will be cut in half again.
At the same time, Bitcoin is liquid enough to support increasingly sophisticated financial structures around it.
That creates an important distinction:
Bitcoin itself doesn’t need to produce yield for financial products built on Bitcoin to produce cash flow.
Companies can hold BTC as the capital base, then raise equity, issue credit or structure other securities around that reserve. Strategy is one early large-scale example of this model, not the model itself.
The trade-off is volatility. BTC appreciation does not arrive smoothly, while dollar obligations usually do. Any structure built on Bitcoin therefore has to survive the drawdowns between periods of appreciation.
But if these structures can survive full market cycles, Bitcoin’s role changes. It becomes more than an asset investors buy and wait to appreciate. It becomes a scarce base layer of capital that other financial products can be built around.

Bitcoin Keeps Coming Back. Most Altcoins Don’t.
This chart captures one of the hardest lessons in crypto: a market recovery does not mean the old winners recover with it.
In 2021–22, names like $ADA, $DOT, $AVAX, $LUNA and cosmos:native reached major valuation peaks. Later cycles produced a different set of leaders: $INJ, $KAS, $SOL, $HYPE, $ZEC and others.
Capital didn’t simply return to the previous winners. It moved toward new narratives, new products and new sources of growth.
Bitcoin has been the major exception.
Across multiple cycles, BTC has repeatedly recovered from deep drawdowns and gone on to set new market-cap highs. Most altcoins have not. Their biggest risk isn’t just volatility or a 70–90% drawdown. It’s losing relevance before the next wave of capital arrives.
That distinction matters even more as the market matures. There are more tokens competing for liquidity, while ETFs and institutional access give large pools of capital a direct route into Bitcoin without requiring that money to rotate further down the risk curve.
So I wouldn’t assume the next recovery lifts everything back to its previous ATH.
Bitcoin competes with its own previous highs. Most altcoins also have to compete with the next generation of altcoins.
That’s a much harder game to win.

Bitcoin Is Now Scarcer Than Gold
Bitcoin’s annual supply growth has fallen to roughly 0.82%, already below gold’s estimated 1.5–2%.
And unlike gold, that gap is designed to keep widening.
When gold prices rise, higher margins can make more mining economically viable, allowing production to respond. Bitcoin works differently: a higher BTC price cannot create more new Bitcoin. Issuance follows a fixed schedule regardless of demand.
After the next halvings, annual supply growth is expected to fall toward:
2028: ~0.4% → 2032: ~0.2% → 2036: ~0.1%
That’s the part of Bitcoin’s scarcity thesis that matters most. It’s not simply that supply is limited to 21 million. The flow of new supply becomes progressively harder to expand while demand has no such limit.

JPMorgan Now Expects Bitcoin to Outperform Stocks and Gold 🧵
J.P. Morgan Asset Management just gave Bitcoin something Wall Street rarely does: a place in its 10-year capital market assumptions.
For 2027, it estimates Bitcoin could deliver a 10% annual compound return, ahead of:
• U.S. large caps: 7.5%
• Gold: 5.5%
• U.S. bonds: 5.6%
That number matters less as a price target than as a signal.
Bitcoin is now being modeled alongside the same asset classes institutions use to build long-term portfolios.

But JPMorgan isn’t calling Bitcoin the “best” asset.
Its expected annualized volatility is 55%, versus 18% for U.S. large caps and 17.2% for gold. So BTC offers the highest expected return in the table, but investors are being asked to tolerate roughly 3× the volatility of stocks or gold to capture it.
That’s why return alone doesn’t determine allocation.
For institutions, the real question is how much Bitcoin improves a portfolio per unit of risk, and JPMorgan still says BTC’s unstable correlations make that difficult to model within its standard portfolio framework.
This is where the report becomes more interesting than the 10% forecast.
Bitcoin has no cash flow to discount, so any 10-year estimate depends heavily on adoption, liquidity, regulation and how much capital ultimately chooses to hold it. Even JPMorgan describes this as a “first look,” not a mature allocation model.
And 10% may prove conservative. Bitwise CIO Matt Hougan has called JPMorgan’s estimate a “floor, not ceiling,” while Bitwise’s own long-term base case has been substantially higher. But whether Bitcoin returns 10% or 20% isn’t the biggest shift here.
Wall Street is starting to ask not whether Bitcoin belongs in long-term capital market models, but what return and risk assumptions it should use once it’s there.
$100 in Cash vs. $100 in Bitcoin Since 2017
In early 2017, Bitcoin traded around $1,000. Today, it’s around $82,000. That means $100 invested back then would be worth roughly $8,200 today.
Meanwhile, U.S. consumer prices have risen roughly 35% since 2017, meaning $100 kept in cash has lost about 26% of its purchasing power. But the real lesson isn’t simply “Bitcoin beats cash.”
Capturing that return meant surviving a 72.6% decline in 2018, another 65.4% decline in 2022, and several major corrections in between.
Cash loses purchasing power slowly. Bitcoin can lose purchasing power violently before creating it over the long run.
That’s why long-term investing isn’t just about choosing the right asset. It’s about holding a position small enough that you can actually survive its worst years.
Strategy and Strive Keep Adding Bitcoin
Strategy added 267 BTC, bringing its total holdings to 848,517 BTC, while Strive made the larger move with 1,223 BTC, taking its stack to 36,818 BTC.
The purchases themselves aren’t surprising anymore. What matters is that both companies are still able to turn access to capital markets into additional Bitcoin, even after BTC has grown into a much larger asset.
That creates a different kind of demand from retail buying: corporate accumulation can continue as long as companies can raise capital on attractive terms.
The key thing to watch isn’t just how much BTC they buy next, but whether this financing model continues to work as market conditions change.

Bitcoin Is Becoming Part of a 24/7 Global Market
Commodities made up 19% of RWA perp volume in July. By September, that share had jumped to 31.4%.
The interesting part isn’t simply that traders can now trade oil or gold onchain. It’s where those trades are happening.
Markets that once lived almost entirely on traditional exchanges are starting to show up alongside BTC, ETH and other crypto assets on the same 24/7 trading venues.
That changes the environment around Bitcoin.
A few years ago, most crypto liquidity stayed within crypto. Today, a trader can move between Bitcoin, gold, oil, stocks and indices without leaving the same trading infrastructure.
It also brings Bitcoin closer to the macro world. An oil shock, a Fed decision or a sharp move in gold can affect positioning across these markets almost immediately. BTC is increasingly reacting to the same forces that drive traditional global assets.
There’s another side to it. More markets also mean more competition for capital. When oil or gold volatility picks up, traders now have more places to deploy risk without leaving crypto rails.
But the market around Bitcoin is getting much bigger.
Crypto venues are no longer just for trading crypto. As more traditional assets move into the same 24/7 environment, Bitcoin is increasingly trading alongside global markets rather than in a market of its own.

Market Update:
• BTC: $82.4K
• Total crypto market cap: $2.86T, down 1.94% over 7D
• BTC Dominance: 57.68%, continuing to favor Bitcoin over the broader market
• Fear & Greed: 59, sentiment remains in Greed despite recent volatility
• Altcoin Index: 58/100, rotation is improving but still not a clear altseason
What to watch next week:
• Token unlock pressure increases, with $72.6M on Oct 20 and $96.5M on Oct 21
• Watch whether BTC can hold the $80K–82K area after last week’s volatility
• BTC dominance remains important: continued strength would keep the market BTC-led, while a sustained decline could open more room for altcoins
• Macro and U.S. rate expectations remain key after the latest inflation data.


Bitcoin’s security isn’t built on a single line of defense. It’s built in layers.
Private keys make unauthorized access computationally impractical. Digital signatures prove ownership without revealing the key itself. And Proof of Work makes rewriting Bitcoin’s transaction history increasingly expensive as the chain grows. That distinction matters.
Most major “Bitcoin hacks” have targeted exchanges, custodians, wallets or users, not broken Bitcoin’s underlying cryptography or consensus mechanism.
Bitcoin doesn’t eliminate security risk. It changes where that risk lives.
This video breaks down how those layers work 👇
xitter.cf/DocumentingBTC/status/…

Bitcoin’s Leverage Hasn’t Been Fully Flushed Yet
Nearly $1B in liquidations followed two days of hotter CPI and PPI data, yet Bitcoin futures open interest still sits around $35–36B. That is the part worth paying attention to.
OI is no longer near its 2026 highs, so leverage is not extreme by historical standards. But after a meaningful liquidation event, you would normally want to see positioning reset more clearly. Instead, a large amount of exposure remains open across Binance, Bybit, Hyperliquid and OKX. This leaves Bitcoin in an unusual position: leverage has been damaged, but not cleared. And that matters more than whether OI itself looks “high” or “low.”
Open interest represents positions that still need to be resolved. When macro uncertainty is elevated, those positions become potential fuel in either direction. A dovish surprise can force shorts to chase the market higher; another inflation or Fed shock can push leveraged longs into another liquidation cascade.
One lesson from trading highly leveraged Bitcoin markets is that the first liquidation wave is not always the final one. Price can stabilize before positioning does. That often creates a period where the chart looks calmer than the underlying market actually is. So I wouldn’t read the current OI as automatically bearish. I’d read it as evidence that Bitcoin still has a large amount of unfinished positioning.
The healthier setup would be BTC holding key levels while OI gradually falls and spot demand remains firm. That would suggest leverage is being absorbed without another major price reset.
If instead OI rebuilds faster than spot demand while price remains fragile, the market is simply reloading the same risk that caused the previous flush. After a liquidation event, the question isn’t how much leverage was destroyed. It’s how much leverage survived.

⚡ TOP 5 BITCOIN ECOSYSTEM PROJECTS BY 24H VOLUME
$ORDI | @SolvProtocol $SOLV | $SATS | $PTB | @Multibit_Bridge $MUBI
Trading activity across the Bitcoin ecosystem remains spread between Ordinals, BRC-20 and BTCFi/infrastructure projects, showing that liquidity is moving across multiple Bitcoin-native narratives rather than concentrating in one sector.
Which Bitcoin ecosystem project are you watching?
