

Most investors look too late. I study market breadth, relative strength & emerging trends. Systematic rankings of 2,500+ stocks across global markets.
Joined April 2022
- Tweets7.9K
- Following172
- Followers10K
- Likes42K





☢️ URANIUM: FIFTEEN YEARS OF STRUCTURAL DIVERGENCE
Two indicators tracking the same universe of uranium developers paint radically different pictures.
🔴 The advance-decline line has been in an almost uninterrupted downtrend since 2011.
🔵 The advance-decline volume line shows a clear long-term uptrend over the same period.
How should we interpret this divergence?
While weakness has affected a broad number of companies, trading volume has historically favored advancing stocks.
This suggests an extraordinarily selective market, with investor interest potentially concentrated in a limited number of companies.
Both indicators are currently declining, but the structural divergence persists.
The real transformation of the sector could occur when traditional market breadth breaks its fifteen-year downtrend and confirms the historical strength of volume.
That would represent a major regime shift.
#Uranium #UraniumStocks #URA #URNM #MarketBreadth #TechnicalAnalysis

🥈 SILVER MINERS: WHAT IF THE BIGGEST OPPORTUNITY IS HIDING BEHIND THE WORST MARKET BREADTH?
The numbers are striking.
Across our silver-mining universe:
📉 Only 9.28% of eligible stocks trade above their 200-day moving averages.
📉 Median weekly return: −5.95%.
📉 Median drawdown from 52-week highs: −43.16%.
And perhaps the most remarkable figure:
More than half of the universe is trading below its own historical 10th-percentile threshold for distance to MA200.
This is not ordinary market weakness. The deterioration is widespread and historically extreme.
But here's the important distinction:
Extreme weakness is not proof of a bottom. Neither is it proof that the broader precious-metals bull market is over.
The next major development may not be a new high in silver.
It may be the moment when mining stocks finally begin recovering together.
Watch the breadth. The next chapter could begin beneath the surface.
#Silver #SilverMiners #SIL #SILJ #PreciousMetals #MiningStocks #MarketBreadth

⚡ ENERGY STOCKS: A POWERFUL REBOUND, BUT IS THE DAMAGE REALLY BEHIND US?
The week ending November 13 has significantly changed the short-term picture for the energy sector.
After a −12.65% median decline the previous week, our ENERGY universe rebounded +5.45%, with nearly nine out of ten instruments advancing.
The recovery extended beyond prices.
Market breadth improved from 30.26% to 43.59% of instruments trading above their 200-day moving averages.
Selling pressure eased substantially, 52-week drawdowns narrowed, and relative strength against the S&P 500 improved considerably.
These improvements are real. The rebound has been accompanied by genuine repair in the market's internal structure.
But the recovery remains incomplete.
Breadth is still far below its September and October levels. Fewer than half of eligible instruments trade above MA200, and the median 20-session signed-volume balance has not yet moved convincingly into positive territory.
Meanwhile, $XLE continues to respect its long-term bullish structure, even as the divergence between its price action and participation across the broader ENERGY universe remains relevant.
This is an important distinction.
The current evidence does not establish that the energy bull market has ended. But neither does one powerful rebound prove that the previous deterioration has been fully reversed.
The rebound is real. Structural recovery is underway, but confirmation is still missing.
The coming weeks will be decisive in assessing whether breadth and volume continue to improve or whether this proves to be a temporary recovery following an exceptionally sharp correction.
Price tells us what the market is doing. Breadth and volume help us judge the strength behind the move.
📊 Full analysis, historical breadth chart and complete interactive ranking of 197 energy-related instruments:
structuralalpharesearch.net/…
#Energy #EnergyStocks #XLE #OilAndGas #MarketBreadth #TechnicalAnalysis #Commodities #StockMarket

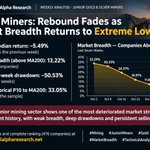
🚨 JUNIOR MINERS: A MARKET UNDER EXTREME PRESSURE
The rebound has failed. Market breadth is approaching historic lows.
The latest weekly analysis from Structural Alpha Research examines 476 junior gold and silver mining stocks, with data through November 13, 2026.
The findings reveal much more than another difficult week for mining shares.
📉 A BROAD-BASED SELLOFF
After a +4.35% median gain the previous week, junior miners reversed sharply:
• Median weekly return: −5.49%
• 332 stocks declined; only 91 advanced.
• 249 companies lost at least 5%.
• 90 companies fell 10% or more.
Nearly 70% of the universe finished the week lower.
📊 LONG-TERM MARKET BREADTH IS COLLAPSING
Only 13.22% of eligible stocks remain above their 200-day moving averages, down from 18.60% the previous week.
The median stock trades 24.37% below its MA200.
This isn't simply a correction in a few speculative names. Long-term technical weakness is widespread across the sector.
🔎 THE HISTORICAL PERSPECTIVE IS EVEN MORE STRIKING
Our separate daily breadth series extends back to 1981.
At the November 13 close, only 62 of 452 eligible stocks were above MA200 — just 13.72%.
Among the 606 daily observations with at least 400 eligible companies, this is the third-lowest breadth reading.
The brief recovery to 21.35% on November 9 had almost completely disappeared four trading sessions later.
The two breadth figures use different eligibility samples, but both tell the same story: participation remains exceptionally weak.
⛏️ THE DAMAGE RUNS DEEP
The median 52-week drawdown has reached −50.53%, the worst reading in our 155-week Weekly Analysis history.
Almost 85% of stocks with valid drawdown data remain more than 30% below their 52-week highs.
Meanwhile, one-third of eligible companies trade below their own historical 10th-percentile threshold for distance to MA200 — the highest proportion in the calibrated weekly record.
📉 SELLING PRESSURE STILL DOMINATES
Our 20-session signed-volume measure remains deeply negative, while junior miners continue to underperform the broader equity market.
A few stocks are showing remarkable relative strength, but isolated winners do not constitute a sector-wide recovery.
THE BIG QUESTION: CAPITULATION OR FURTHER WEAKNESS?
These readings are extreme. They deserve attention.
But extreme weakness is not proof of a bottom.
The next meaningful signal will be whether participation begins to recover sustainably, supported by improving volume and narrowing drawdowns.
A price rebound can happen quickly. A genuine structural recovery requires broader confirmation.
📖 Full research, historical breadth charts and the complete interactive ranking of 476 companies:
structuralalpharesearch.net/…
#JuniorMiners #GoldMiners #SilverMiners #PreciousMetals #MiningStocks #MarketBreadth #Gold #Silver

⛏️ GOLD MINERS: PRICE IS HOLDING UP. BREADTH IS NOT.
One of the most important charts in the sector right now may not be price itself.
Look at the GDX-GDXJ advance-decline line.
While gold miners have avoided a full breakdown, market breadth keeps deteriorating.
The advance-decline line continues to trace a pattern of lower highs and lower lows.
That matters.
Because bull markets are strongest when participation is broad.
When fewer and fewer stocks are carrying the sector, the structure becomes more fragile.
This does not automatically mean the bull market in miners is over.
But it does mean this:
price resilience is no longer being confirmed by internal participation.
That kind of divergence is worth watching closely.
If breadth starts to recover, the sector could regain strength.
If not, the warning becomes harder to ignore.
In mining stocks, what happens beneath the surface often matters as much as price itself.
#Gold #GoldMiners #GDX #GDXJ #MarketBreadth #TechnicalAnalysis #PreciousMetals

☢️ URANIUM STOCKS: EXTREME WEAKNESS, BUT SOMETHING IS STARTING TO CHANGE.
The uranium sector remains under significant pressure.
Market breadth is deeply depressed, most stocks are trading well below their 200-day moving averages, and leading uranium miners continue to struggle.
But beneath the surface, something interesting is happening.
Selling pressure is easing. Fewer stocks are declining on heavy volume, and market breadth is beginning to stabilize.
These are encouraging developments, but not yet confirmation of a sustainable bottom.
The sector remains structurally weak, and relative strength has yet to recover convincingly.
The key question is no longer just how far uranium stocks have fallen, but whether selling exhaustion can finally turn into broad-based buying.
The next few weeks could be revealing.
Watch breadth and volume. Price alone won't tell the whole story.
#Uranium #UraniumStocks #URNM #URA #NuclearEnergy #MarketBreadth #MiningStocks

🥈 SILVER MINERS: THE CORRECTION TESTS YOUR PATIENCE. THE STRUCTURE TESTS YOUR CONVICTION.
Markets deceive. What feels like an exhausting correction can look remarkably precise from a longer-term perspective.
Look at $SIL.
Despite the volatility, price continues to respect the ascending structure outlined well in advance.
The pullbacks, consolidations and tests of support have unfolded within the broader bullish roadmap.
The rising Ichimoku cloud continues to support the long-term picture, while the PMO remains positive despite weakening momentum.
Momentum is cooling. The bullish structure remains intact.
Strong bull markets rarely move in straight lines. Corrections test patience, shake out short-term traders and create uncertainty even when the underlying trend remains healthy.
As long as the rising structure holds, the broader bullish scenario remains valid.
The short-term noise is uncomfortable. The long-term picture tells a different story.
Patience builds opportunity. Judgment protects capital.
— @BroadLuis | Structural Alpha Research
#Silver #SilverMiners #SIL #PreciousMetals #MiningStocks #TechnicalAnalysis

📊 GLOBAL MARKETS: A RECOVERY THAT HIDES A DEEPLY DIVIDED MARKET
🥇🥈 Gold & Silver Miners Remain Under Pressure While Equities Regain Strength
INTRODUCTION
This week's analysis of 17 market universes reveals an increasingly striking divergence.
Major equity markets are recovering. Buying participation is improving, and several sectors are showing signs of renewed strength.
Yet beneath that recovery, large parts of the mining sector remain deeply damaged.
The contrast is particularly evident in gold and silver miners, where the correction continues to affect the overwhelming majority of companies.
The market is recovering, but not everyone is participating.
KEY CONCLUSIONS
🔹 1. GOLD & SILVER MINERS: THE CORRECTION IS FAR FROM OVER
Gold and silver miners remain among the weakest areas of the market.
Only a small minority of companies trade above their 200-day moving averages. Market breadth continues to deteriorate, drawdowns remain substantial, and buying pressure is still insufficient to suggest a broad recovery.
Silver miners are particularly weak, with fewer than one in ten stocks above their MA200.
This is not simply a correction affecting a handful of companies. It reflects widespread deterioration across the sector.
Nevertheless, weak market breadth alone does not mean the long-term precious metals bull market is over.
A correction within a bull market can be extremely painful without necessarily invalidating the broader bullish thesis.
🔹 2. JUNIOR MINERS: THE MOST SEVERE DAMAGE IS STILL VISIBLE
Junior miners continue to suffer from exceptionally weak market participation.
Many companies remain far below their previous highs, and the majority have yet to recover their long-term moving averages.
The deterioration is particularly pronounced among junior gold, silver and copper miners.
These conditions deserve close attention, but extreme weakness should not automatically be confused with a confirmed market bottom.
Oversold does not necessarily mean ready to rally.
🔹 3. SEMICONDUCTORS: A POWERFUL REBOUND IS NOT THE SAME AS A RECOVERED TREND
Semiconductors delivered one of the strongest rebounds of the week.
Almost the entire universe participated in the advance, suggesting a significant improvement in short-term sentiment.
However, most stocks remain below their 200-day moving averages.
The recovery in prices has been impressive, but the underlying market structure still needs further improvement.
Strong rallies can occur long before a sector fully repairs its technical damage.
🔹 4. THE S&P 500, STOXX 600 AND US BANKS SHOW GREATER STRUCTURAL STRENGTH
Unlike the mining sector, major equity markets are displaying healthier participation.
More companies are trading above their long-term moving averages, while buying pressure has improved.
European equities and US banks are particularly noteworthy.
US banks have recorded a substantial improvement in market breadth over the past month, suggesting that their recovery extends beyond a simple short-term rebound.
The contrast with precious metals miners could hardly be clearer.
🔹 5. ENERGY: A STRONG RECOVERY, BUT THE DAMAGE HAS NOT DISAPPEARED
Energy stocks rebounded sharply this week following a period of considerable weakness.
However, their longer-term market breadth remains well below its level of four weeks ago.
The rebound is encouraging, but further evidence is needed before concluding that the sector has established a sustainable recovery.
🔹 6. COPPER, URANIUM, PLATINUM AND LITHIUM: STRUCTURAL WEAKNESS PERSISTS
The weakness is not limited to gold and silver.
Other mining-related sectors continue to display depressed market breadth and substantial drawdowns.
Lithium is particularly striking: none of the companies in our monitored universe currently trades above its 200-day moving average.
These are exceptionally weak conditions.
But history teaches us an important lesson: extreme weakness describes the current state of the market. It does not tell us precisely when that weakness will end.
FINAL CONCLUSIONS
The most important message from this week's analysis is the growing divergence between recovering equity markets and the persistent deterioration across mining stocks.
The S&P 500, European equities and US banks are showing improving structural participation.
Semiconductors and energy are rebounding strongly, although their longer-term trends still require confirmation.
Meanwhile, precious metals miners and several other mining sectors remain under considerable pressure.
Does this mean the precious metals bull market is over?
Not necessarily.
Mining stocks are notoriously volatile. Their corrections can be deeper and last longer than investors expect, even within major bullish cycles.
But there is an equally important lesson:
A deeply oversold market is not automatically a buying opportunity, just as a powerful rebound is not automatically a new uptrend.
Patience matters. Market structure matters. And confirmation matters.
For gold and silver investors, the coming weeks will be particularly important.
I continue to favor the broader bullish thesis for precious metals, but the current data demand discipline rather than complacency.
The long-term opportunity may remain intact, even while the short-term correction tests investors' convictions.
📊 Full weekly analysis of 17 market universes, including market breadth, drawdowns, volume and sector comparisons:
structuralalpharesearch.net/…
#Gold #Silver #GoldMiners #SilverMiners #JuniorMiners #PreciousMetals #Copper #Uranium #StockMarket #MarketBreadth

🥇🥈 GOLD & SILVER MINERS: THE BRUTAL REALITY OF THIS CORRECTION.
I've analyzed 214 precious-metals-related securities since January 29.
📉 87.4% in negative territory.
📉 Average return: −27.9%.
📉 Median return: −30.3%.
📉 Average drawdown from highs: −40.7%.
Only 27 remain in positive territory.
Corrections like this test even the strongest convictions. But severe market damage doesn't necessarily mean the bull market is over.
Patience. Perspective. Discipline. 💪
📊 Full interactive ranking of all 214 securities:
structuralalpharesearch.net/…
#Gold #Silver #MiningStocks #PreciousMetals

2
28
2,247
🥈 SILVER: PATIENCE IS THE NAME OF THE GAME! 🚀
Silver is once again testing its major support, but look at the bigger picture: price action is unfolding within an almost perfect triangular consolidation.
Silver can be painfully slow. It tests your patience, wears you down, and sometimes pushes you to the brink of despair.
But there is no reason to panic as long as the main support holds.
The longer the consolidation, the more significant the eventual breakout could be.
Don't let frustration make your decisions for you. Patience is part of the game. 💪
#Silver #XAGUSD #SilverMiners #PreciousMetals

🇦🇺 ASX MINERS | THE REBOUND IS BROADENING, BUT THE DAMAGE RUNS DEEP
Australian mining stocks are showing encouraging signs of recovery after October's sharp selloff. However, the underlying market structure remains fragile.
Our latest weekly analysis covers 89 ASX-listed mining companies, through November 13, 2026.
📊 THE NUMBERS TELL TWO DIFFERENT STORIES:
✅ 54 of 89 stocks advanced this week (60.7%).
✅ Median weekly return: +1.10%.
✅ MA200 breadth has recovered from just 11.2% on October 23 to 30.3%.
⚠️ Nearly 70% of stocks still trade below their 200-day moving averages.
⚠️ Median 52-week drawdown remains a substantial −38.4%.
VOLUME: SELLING PRESSURE IS EASING, BUT BUYERS ARE NOT YET IN CONTROL.
The number of companies showing a positive 20-session volume balance doubled from 13 to 26. However, median relative volume fell to just 0.73x, suggesting that the recovery still lacks broad buying conviction.
LEADERSHIP REMAINS HIGHLY SELECTIVE.
Benz Mining (+137.9% YTD) and Solstice Minerals (+434.2% YTD) remain among the strongest structural performers.
Meanwhile, several of the week's biggest gainers are still deeply negative over longer periods. A powerful rebound does not necessarily mean a trend reversal.
🔎 THE KEY TAKEAWAY:
The recovery is broadening, but the market is still repairing the damage from October. Sustained improvement in MA200 breadth and stronger volume participation are needed before we can speak of a confirmed structural recovery.
Short-term momentum is improving. Long-term market structure is still catching up.
📖 Full weekly analysis, historical breadth context and the complete interactive ranking of all 89 companies:
structuralalpharesearch.net/…
#ASX #GoldMiners #MiningStocks #MarketBreadth

🥈 SILVER | Setting Up for a Strong Bullish Rebound
Silver is starting to bounce off a major support zone around $48–$50, following an extended correction within a descending channel.
The primary uptrend remains intact, and from a technical perspective, a strong bullish reaction from these levels would be the logical scenario.
For that to happen, price needs to accelerate higher, build momentum, and allow the technical indicators to gradually improve after the recent correction.
The Woodies CCI is beginning to show signs of recovery from oversold levels, while the momentum oscillator still needs confirmation.
Support is holding. Now we need price to accelerate and momentum to follow.
#Silver #PreciousMetals #TechnicalAnalysis

🚨 COPX–COPJ: COPPER STOCKS REACH EXTREME TECHNICAL WEAKNESS
Our latest weekly analysis of 101 copper-related stocks reveals a sharp deterioration in market breadth and long-term technical structure.
📊 Key findings:
▪️ Only 15% of stocks remain above their 200-day moving average, down from 51% four weeks ago.
▪️ Median distance to MA200 has fallen to −15.50%, its lowest reading in 156 weeks.
▪️ 70.71% of stocks are more than 30% below their 52-week highs.
▪️ Median 52-week drawdown stands at −39.04%.
Our conclusions:
Selling pressure has moderated somewhat, but market breadth continues to deteriorate.
Extreme technical weakness may eventually create conditions for a strong recovery. However, oversold readings alone do not confirm a market bottom.
We would prefer to see MA200 distance stabilize, breadth improve and buying participation broaden before considering a sustainable recovery confirmed.
📈 Full research, historical charts and interactive ranking of all 101 stocks:
structuralalpharesearch.net/…
#Copper #COPX #COPJ #MiningStocks #MarketBreadth

SEMICONDUCTOR STOCKS: MARKET BREADTH COLLAPSES AS HEAVY SELLING ACCELERATES 📉
The semiconductor sector is experiencing a sharp deterioration in market structure. What began as a correction has developed into widespread selling pressure, accompanied by unusually heavy trading volume.
Our latest Structural Alpha Research study examines 33 semiconductor stocks against the PHLX Semiconductor Index ($SOX), using 155 weeks of historical data.
Key findings:
🔻 Market breadth has collapsed. Just 15.15% of stocks remain above their 200-day moving average, down from 81.82% only five weeks earlier.
📉 Selling is widespread. 29 of 33 stocks declined last week, with a median loss of 9.99%, compared with a 12.15% decline in $SOX.
📊 Volume confirms the intensity of the selloff. 21 companies fell on elevated relative volume, while median trading volume reached 1.69× its reference level.
⚠️ Drawdowns are approaching historical extremes. The median stock is 39.01% below its 52-week high, and 23 of 33 companies have declined more than 30%.
Our conclusion:
The semiconductor sector has moved from broad bullish participation to severe structural weakness in just five weeks.
These conditions are consistent with an intense liquidation phase and may eventually create the conditions for a powerful recovery.
But extreme oversold conditions do not necessarily mark the end of a decline.
The evidence of deterioration is clear. Confirmation of a durable bottom is not.
Full analysis, historical breadth charts, volume indicators, and the complete interactive ranking of all 33 companies:
structuralalpharesearch.net/…
#Semiconductors #SOX #MarketBreadth #StockMarket #StructuralAlphaResearch

📈 PLATINUM / PGM: A Broad Rebound, but the Long-Term Structure Remains Deeply Weak
Platinum and PGM mining stocks are showing their first signs of stabilization after a prolonged and severe correction.
Our newly established universe covers 20 companies across North America, South Africa and Australia. It is not intended to represent the entire global industry.
📊 Key findings:
▪️ +4.97% median weekly return, with 13 of 20 companies advancing.
▪️ Only 5% remain above their 200-day moving averages, following two consecutive weeks at 0%.
▪️ Median distance to MA200 stands at −23.20%, despite a meaningful weekly improvement.
▪️ Median drawdown from 52-week highs remains −52.38%, with 55% of companies down more than 50%.
▪️ Selling pressure is easing, but broad buying participation has yet to emerge.
The conclusion:
The rebound is real, and some internal indicators are beginning to improve.
But one strong week does not reverse months of structural deterioration.
The key will be whether breadth continues to recover, drawdowns narrow, and buying participation expands.
Early stabilization? Possibly. A confirmed trend reversal? Not yet.
📊 Chart: 10-week evolution of market breadth and distance to MA200.
🔗 Full research and complete 20-company ranking:
structuralalpharesearch.net/…
#Platinum #PGM #MiningStocks #MarketBreadth

📊 These are the 20 companies that make up our PLATINUM/PGM universe at Structural Alpha Research.
This universe forms the basis of our weekly analysis of market breadth, relative strength, momentum, volume, and drawdowns across platinum and platinum-group metals equities.
🔗 Full analysis and interactive ranking:
structuralalpharesearch.net/…
$GENM.TO — Generation Mining
$ELR.TO — Eastern Platinum
$ZIM.AX — Zimplats Holdings
$SBSW — Sibanye Stillwater
$IMPUY — Impala Platinum Holdings
$LZM — Lifezone Metals
$VALT.L — Valterra Platinum
$NPHJ.J — Northam Platinum Holdings
$ARIJ.J — African Rainbow Minerals
$PGE.V — Stillwater Critical Minerals
$PLG — Platinum Group Metals
$BRVO.V — Bravo Mining
$SLPL.L — Sylvania Platinum
$AIR.V — Clean Air Metals
$XTM.V — Transition Metals
$THST.L — Tharisa
$IVN.TO — Ivanhoe Mines
$NAM.V — New Age Metals
$GRML — Greenland Mines
$VO.V — Valore Metals

🌱 FERTILIZERS | MOSAIC’S REBOUND DOESN’T CHANGE THE BIGGER PICTURE
The fertilizer sector continues to show significant structural weakness, despite a sharp rebound in a few individual stocks.
📊 Week ended November 6, 2026:
• $MOS led the sector with an impressive +21.6% weekly gain.
• The universe’s median weekly return was −3.17%.
• Only 4 of 17 stocks (23.5%) are trading above their 200-day moving averages.
• 52.9% remain more than 30% below their 52-week highs.
What are these numbers telling us?
The divergence is striking. While Mosaic staged a powerful rally, the broader sector remains under considerable pressure.
Market breadth has yet to confirm a broad-based recovery. Individual stocks can lead an emerging reversal, but sustainable trends require wider participation.
Conclusion: We are seeing selective strength, not yet confirmed sector leadership.
What I'll be watching is a sustained improvement in market breadth, particularly the percentage of stocks reclaiming their 200-day moving averages.
A rebound can start with a single stock. A sustainable trend needs participation.
#Fertilizers #MarketBreadth #Commodities

🌱 For a deeper look at the fertilizer sector, I've published the full analysis on Structural Alpha Research.
The study covers market breadth, MA200 positioning, drawdowns, volume participation, and the complete ranking of all 17 companies.
📊 Read the full report:
structuralalpharesearch.net/…

1
565
🟡 JUNIOR GOLD & SILVER MINERS: A POWERFUL REBOUND FROM EXTREME MARKET WEAKNESS
Are we witnessing the beginning of a major recovery, or simply a rebound within a deeply damaged market?
We analyzed 480 junior gold and silver mining-related instruments, examining market breadth, returns, trading volume, drawdowns from recent highs, and historical precedents.
The findings are particularly interesting.
A detailed thread 🧵👇
1/ THE WEEKLY REBOUND: A BROAD-BASED RECOVERY
During the week ending November 6, 2026, our JUNIOR universe recorded:
🟢 294 instruments advanced (61.25%).
🔴 133 declined (27.71%).
⚪ 53 remained unchanged (11.04%).
📈 Median weekly return: +4.35%.
📈 Average weekly return: +4.75%.
Furthermore:
• 223 instruments gained at least 5%.
• 129 advanced by 10% or more.
This was not a rebound driven by just a handful of companies. The recovery extended across a majority of the universe.
2/ THE KEY FACTOR: EXTREMELY DEPRESSED MARKET BREADTH
Our market breadth indicator measures the percentage of eligible instruments trading above their 200-day moving average (MA200).
Its recent deterioration has been remarkable:
📉 September 4: 48.95%.
📉 October 30: 11.89%.
📈 November 6: 18.60%.
In just eight weeks, breadth collapsed from nearly 49% to less than 12%.
The October 30 reading was the lowest among 154 weekly observations available since December 2023.
The subsequent recovery of 6.71 percentage points is significant.
However, one crucial fact remains:
More than 80% of eligible instruments are still trading below their MA200.
3/ WHAT DOES RECENT HISTORY TELL US?
Within the 154 weekly observations covered by our study, we identified only two previous episodes when MA200 breadth fell below 20%.
📅 February 23, 2024
MA200 breadth: 19.32%.
Subsequent median returns:
• 4 weeks: +11.62%.
• 8 weeks: +27.61%.
• 12 weeks: +31.42%.
📅 July 17, 2026
MA200 breadth: 19.75%.
Subsequent median returns:
• 4 weeks: +16.67%.
• 8 weeks: +20.00%.
• 12 weeks: +7.34%.
Both episodes were followed by substantial recoveries.
However, their subsequent trajectories differed.
Two historical observations are nowhere near enough to establish that another market bottom has formed.
These figures represent cross-sectional median returns, not investable portfolio performance.
4/ EXTENDING THE HISTORICAL ANALYSIS: GDXJ AND SILJ
To examine earlier market environments, we also explored a separate long-term breadth dataset alongside the historical price performance of:
• GDXJ: Junior gold miners ETF.
• SILJ: Junior silver miners ETF.
This longer historical dataset was generated using a legacy application and reflects a changing number of eligible mining instruments over time.
Consequently, it should not be treated as directly interchangeable with our current weekly breadth series.
The preliminary findings reveal an important distinction:
Extremely depressed market breadth has sometimes preceded powerful short-term rallies.
But similar conditions have also occurred during prolonged market declines.
Extreme breadth weakness may precede a rebound without necessarily identifying the final market bottom.
5/ THE MOST INTERESTING QUESTION: WHAT HAPPENS WHEN BREADTH STARTS RECOVERING?
Studying what happens when breadth falls below 20% is only part of the picture.
We must also examine what happens when participation begins to improve.
Our exploratory analysis of historical breadth recoveries suggests that an initial expansion in participation has not consistently translated into positive subsequent returns for GDXJ and SILJ.
March 2020 provides an example of a particularly powerful recovery.
October 2018 illustrates the opposite outcome: an initial improvement in breadth followed by renewed declines.
The implication is important:
The first rebound in market breadth is not, by itself, a reliable confirmation of a trend reversal.
What matters is whether participation continues to expand over subsequent weeks.
6/ THE MARKET REMAINS FAR BELOW ITS RECENT HIGHS
One of the most revealing findings concerns the distance between current prices and their highest closing levels over the previous 52 weeks.
Among 473 instruments with valid observations:
📉 436 instruments (92.18%) are more than 20% below their highs.
📉 377 instruments (79.70%) are more than 30% below.
📉 311 instruments (65.75%) are more than 40% below.
📉 220 instruments (46.51%) are more than 50% below.
The median drawdown stands at −48.46%.
In other words, despite the strong weekly rebound, the accumulated market damage remains exceptionally severe.
A weekly gain of 4%, 5%, or even 10% does not automatically repair a previous 50% decline.
7/ IS BUYING VOLUME RETURNING?
Volume indicators also show early signs of improvement, although participation remains insufficient to establish broad-based buying conviction.
Median five-session relative volume was approximately 0.80 times its preceding 60-session reference.
Only 57 of the 480 instruments recorded relative volume of at least 1.5 times.
Nevertheless, several developments are encouraging:
🟢 Instruments advancing on elevated relative volume increased from 12 to 29.
🔴 Instruments declining on elevated relative volume decreased from 38 to 26.
The proportion of instruments showing a positive signed-volume balance rose from 15.90% to 21.46%.
Selling pressure appears to be easing.
However, the median signed-volume balance remains negative.
Early improvement is visible, but broad-based accumulation has not yet been confirmed.
The signed-volume measure is a price-volume proxy, not direct evidence of institutional buying.
8/ THE BIGGEST WEEKLY WINNERS ARE NOT NECESSARILY THE STRONGEST COMPANIES
Another important distinction is the difference between short-term performance and structural market leadership.
Among the strongest weekly performers:
🚀 Silver Elephant Mining: +103.85%.
🚀 Terra Balcanica Resources: +40.00%.
🚀 Relevant Gold: +34.85%.
🚀 Renforth Resources: +33.33%.
🚀 Gold Hunter Resources: +33.33%.
🚀 Collective Mining: +29.21%.
🚀 G Mining Ventures: +24.73%.
However, some of these companies occupy relatively weak positions in our global ranking.
For example:
• Terra Balcanica: Global rank 331.
• Gold Hunter Resources: Global rank 390.
A spectacular one-week advance does not necessarily transform a company into a long-term market leader.
Technical rebounds, price recoveries, and sustained relative strength are three different concepts.
9/ COMPARISON WITH THE S&P 500
During the same week, the S&P 500 declined by 2.68%.
Meanwhile, 78.33% of our JUNIOR universe outperformed that benchmark.
This represents a notable relative improvement.
However, an important qualification is necessary:
Over the preceding four weeks, only 22.90% of the universe had outperformed the S&P 500, based on available observations.
The latest weekly performance therefore represents a significant improvement following a period of substantial relative weakness.
The key question is whether this relative strength can be sustained.
10/ WHAT SHOULD WE MONITOR NEXT?
Four developments deserve particular attention:
① Sustained expansion in market breadth.
A persistent increase in the percentage of eligible instruments trading above their MA200.
② Narrowing drawdowns from recent highs.
A recovery that reaches more companies rather than depending on isolated rebounds.
③ Broader positive volume participation.
An increasing number of instruments advancing alongside elevated relative trading volume.
④ The emergence of structural leadership.
Strongly ranked companies maintaining relative strength while additional leaders begin to emerge.
We are not simply looking for another positive week.
We are looking for evidence of a progressive improvement in the market's underlying structure.
11/ CONCLUSIONS
The junior gold and silver mining universe has experienced a meaningful rebound from exceptionally depressed market breadth conditions.
The evidence shows:
✅ A clear majority of advancing instruments.
✅ A median weekly return of +4.35%.
✅ A 6.71-percentage-point recovery in MA200 breadth.
✅ Early improvement in volume participation.
However, significant weaknesses remain:
⚠️ More than 80% of eligible instruments remain below their MA200.
⚠️ Nearly 80% of instruments with valid drawdown data are still more than 30% below their 52-week highs.
⚠️ Historical precedents do not reliably identify a definitive market bottom.
⚠️ Broad-based buying participation remains limited.
Our interpretation:
The rebound deserves close attention and may represent the early stages of a broader recovery.
However, the available evidence does not yet confirm a structural trend reversal.
We prefer to wait for sustained improvements in market breadth, volume participation, and relative strength before drawing stronger conclusions.
A POWERFUL REBOUND FROM EXTREME LEVELS. A POSSIBLE TURNING POINT. BUT CONFIRMATION IS STILL MISSING.
12/ FULL RESEARCH REPORT AND INTERACTIVE RANKING
At Structural Alpha Research, we have published our complete weekly analysis of the JUNIOR universe, including:
📊 Market breadth and performance statistics.
📉 Drawdowns from recent highs.
📈 Volume participation indicators.
🔎 Historical comparisons.
🏆 An interactive ranking of all 480 instruments, with searchable company data and multiple return horizons.
Read the complete research report:
structuralalpharesearch.net/…
Structural Alpha Research
Independent Quantitative Market Research
#Gold #Silver #JuniorMiners #GDXJ #SILJ #GoldMiners #SilverMiners #MarketBreadth

📉 NASDAQ 100: Selling Pressure Builds, but Breadth Remains Far Above Bear-Market Lows
The Nasdaq 100 fell 4.91% last week, accompanied by a sharp deterioration in market breadth and elevated selling volume.
Across our 101-stock universe:
▪️ Only 43.43% remain above their 200-day moving averages, down 18.18 percentage points in four weeks.
▪️ One-third are more than 30% below their 52-week highs.
▪️ Median relative volume reached 1.48×, with 33 stocks declining on elevated volume versus just 15 advancing.
But historical perspective matters.
During the major bear markets of 2002, 2008 and 2022, breadth fell below 10%. Today's 43% reading remains well above those levels.
The conclusion: Internal weakness is accelerating, and selling pressure is significant. But the evidence does not establish historical capitulation or a confirmed market bottom.
The key now is whether breadth stabilizes and buying participation begins to recover.
📊 Historical breadth comparison and key metrics below.
🔗 Full research and complete 101-stock ranking:
structuralalpharesearch.net/…
#Nasdaq100 #MarketBreadth #StockMarket #QuantitativeResearch

1
5
1,420