

Research long / short. variant perception. @ Family Office current. Worked at two small cap focused hedge funds prior. Nothing is investment advice.
Austin, TX
Joined June 2023
- Tweets1.9K
- Following278
- Followers3.2K
- Likes728



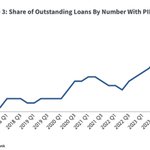


$MFC the spotlight has shifted off private credit but the issues have not gone away. MFC is in my opinion one of the more overlooked violators stuffing their life insurance investments with outsized exposure to private credit and cre. Just look under the hood of their earnings tonight.
"𝐖𝐡𝐞𝐧 𝐰𝐢𝐥𝐥 𝐌𝐚𝐧𝐮𝐥𝐢𝐟𝐞 𝐥𝐨𝐰𝐞𝐫 𝐢𝐭𝐬 𝐚𝐥𝐭𝐞𝐫𝐧𝐚𝐭𝐢𝐯𝐞 𝐚𝐬𝐬𝐞𝐭 𝐫𝐞𝐭𝐮𝐫𝐧 𝐚𝐬𝐬𝐮𝐦𝐩𝐭𝐢𝐨𝐧𝐬? Alternative long-duration assets missed expected returns by $153 million post-tax, marking six straight negative quarters and $1.35 billion of cumulative shortfalls by our math. Keeping unchanged return assumptions turns recurring investment shortfalls into excluded below-the-line charges every quarter."
How the mighty concrete layer bottleneck names fall. $STRL down from over $1,000/share in May. And some still arguing if there ever was a bubble....
Something unholy with price action in the market lately. $GM crushed on earnings, subsequently raises 25%+ in a week to a new high, because well rates. $CAVA went 54 to 65 to now 54 again in the past 5 sessions because well oil but then earnings ?? Pick anything, pick AAPL or AMZN post earnings to a few days later. These are not tiny stocks.
seems there is almost no room for fundamentals or valuation. he only determinant is if its AI on or off and rates and is it moving? Who cares what they say on earnings.....Market structure seems to be broken by passive giving away all prices determination to pod shops and short dated options. This is beyond stretched but who knows when/where it ends in thees being the leading catalysts daily but doubt it ends well
Consensus suggests the blue wave curtails fiscal and ai spending transmitting to lower rates with gridlock policy....and while that will be true tomorrow and likely directionally in key ai buildout states like TX and GA. I would not lose sight down the road that trump is not an idealist, he simply wants to be popular (see his infatuation with Mamdani).
I would not be surprised to see more not less populous policy coming and large fiscal directives driven at subsidies and handouts. The truth is that there are no fiscal hawks (although in cyclical form some republicans will rediscover their budget concerns and grandstand just in the name of opposition). Drug price regulation, housing initiatives (subsidies), wages (higher, possible UBI). Trump does not care about a party or your reelection if you are team red, he wants legacy and popularity and he might be more willing to do things that are very not republican and instead embrace socialist policies than the market appreciates currently. The impulse for rates and spending lower will likely be true near term but also consensus but there may be a very good opportunity to take the other side of that in the coming months
Interesting but not surprising to see the lack of follow through on software names today in the wake of $NOW numbers and 26% decline (+ ftnt). I guess we can expect more tape bombs in this sector until it rerates. Many stocks that are more exposed to ai disruption with higher multiples, lower growth and have rallied more than Servicenow did into the print. And several are barely off, some actually positive on the day..
$now bill is always selling and some people on here seem confused why the stock is down when they look at the numbers he directs you to. Wash away all of his puffery and the underlying business deteriorated - gross profit came in at 10%+ yoy (which I believe is the lowest ever) for the quarter. You can call anything revenue but it's ultimately about the gross profit dollars you bring in + the efficiency of your expense management, which if you look saw increases across the board with profit materially weakening. You can argue intangibles on the COGS but then you need to adjust the light crpo further to exclude all the inorganic revenue helping out in there (which the co did not strip out).....the street is not fooled, these were not great numbers. And swapping revenue to juice AI in a press release while total sales stays on trend is not going to work anymore, as one analyst put it best to Bill
"I wanted to just zoom out a little bit and just talk about the momentum you're seeing on the AI ACV side. Gina as you noted, you've raised the guidance twice now to $1.7 billion in revenue. At the same time, if we look at just the broad story of cRPO, we could call it stable, maybe on an organic basis, modestly decelerating, but sort of generally stable. So my high-level question, Bill, is just when do you think the AI momentum will start to translate to overall top line acceleration, cRPO acceleration?"
There are very different expectations when a stock doubles in a quarter in-between reporting results.....
On integrations will see $DOCU but others like sign now.
There are dozens of signature solutions from panda, adobe, and many many others. All with cheaper solutions. And to say theres no enterprise features or some sort of ecosystem/marketplace - that does not stand. Apple, Exxon and other major corporations use Sign now. I got a signature sheet from Rivian from box directly (and it's not docusign white labeled).
If you're looking for the reversal in software squeeze, DOCU at current pricing and competitive positing in an increasingly Agentic world has to surface as a weak story moving forward that trades at a premium to almost anything else you will look at.

Confused over people trying to take the $ANT S1 at face value on capX/costs and run these economics on a token level or for their financials going forward? If you did, one would have to wonder where all the money in the capX stack is going and whose balance sheet it is on, because if you are going to believe their capital efficiency at 3B in leases and 38B in capX over the past 6 months while revenue scaled 8x then the ai infrastructure narrative is dead and everyone of the chip companies and related "bottleneck co.s" should be down massively you because you can scale tokens without the infrastructure almost at an infinite pace.......OR perhaps the money is somewhere else and it's all going to come home to them in future costs and equity dilution for the IPO. The filing is pretty clear on the later, Im just confused why this is even up for debate on this platform, seems like blatant gaslighting by people with certain positioning and stakes in ANT itself
Oil up 15% this month and extending.....sure it has no impact on Kohls sales outlook where the stock is up 45% in the past month
Gaslighting how $RNG talks about cash flow but ignore the 240m in SBC (roughly 40% of that number). Talking 22-23x cash flow at the implied open. 85x roughly gap eps numbers....for a business that has inflected from 5.5 to 6% growth this year.....They can talk AI and % of ARR abut at the end of it the total impact is having a marginal move on the business. They did some nice work to clean up some costs and get profitability to true gap levels. But that was from bloated application days and low hanging fruit. Thats the move from 14-40. Very difficult for this math of fundamentally make sense from hereat these levels.
25-30x fcf (affecting for SBC) and gap income for Docusign now. If you are buying at this valuation whats the thesis? How do prices and volumes stay intact in an AI world, housing is under pressure and a key pool of their demand runs through that sector (leases, refi, mortgages, insurance etc). How d you argue AI helps this business versus harms it?
Single digit growth and roughly 30x FCF fr 27' - with ai disruption risks higher than average (up 30% this month!)
Full disclosure my frustration with these dispersion short trades intra ai squeezing has likely emotionally walked me into aggressively shorting a bunch of them today and yesterday after following for weeks in bewilderment. $DOCU $V $APPN $GDDY $PCTY $PAYC $KSS $ROL puts and shares on all. Won't stay forever just for reality to comeback, seems like the goal/twst setup from a few weeks ago
$KSS Kohl's is up 50% in a month as oil reclaims highest levels since May.....hard to imagine how this happens. Up another 8% today as the market pukes ai today, which perversely will put more pressure on spending if markets stay pressured so what is the "next level thinking" purchase of Kohls today
We listened to the $ROL call or just trading semis versus everything else because they Tok down guidance a second straight quarter and the implied growth in Q4 could go negative on residential. Big feline but stock is still expensive for what is an ongoing challenge to lead gen from LLMs but the other factor they didn't refer to is the PE competition. Seems like an opportunity to scale back in short somewhere closer to $25 seems correct incredibly odd to see it up after that call
$V is up everyday this month except one (14/15 trading days). Good for an almost 20% gain on the month to date
Have to give credit the squeeze in software is remarkable, they didn't even stop buying them with semis up n the open.
Stocks like $MNDY flying 8% yesterday, $APPN up over 8% today (30% in a week after Barclays remained underweight with a price target roughly 40% current) after their closest comp reported very disappointing earnings and warned of demand and a restructuring.....truly incredible. Starting to give the $GRAL/ $TXG/ $TWST type manic move from a few weeks ago
$PEGA numbers begin the software back to earth story....expect sick to be down significantly tomorrow (it never trades true until the open). The backlog is down QoQ and we are talking 6% ACV now versus guide for 15% at the start of the year. Without a total break from recent trends they will need an absolute monstrous Q4 (comping against a very strong Q4 number yoy coming up) otherwise the backlog number will drop out and that will move from an inflated 15% yoy (from the Q4 25') probably to low single digits or worse.....
Big portions of software is in trouble, this is the very beginning
$V....this is the disruption in play
This quoted post is unavailable.