

Oil & Natural Gas Trader
Joined September 2017
- Tweets8.8K
- Following15
- Followers23K
- Likes1.9K
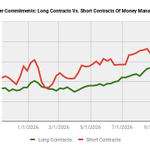

Per yesterday’s CFTC’s latest money manager holdings data, #natgas speculative short positions now stand at 424,344 contracts, the highest since the great Bear Market of January-March 2020. It is the 9th highest short exposure on record, with the other 8 all occurring during that span. Just 32% of speculative positions are held long. Depending on your perspective, this either illustrates the strength of the bearish position or is a set-up for a short squeeze.

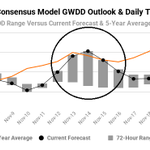
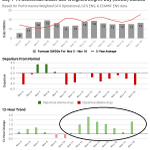
The near-term temperature outlook continued to improve today, particularly in the November 12-16 period. As shown in the Figure below, forecast GWDDs for this period have been particularly volatile, ranging from 12 GWDDs/day to 20 GWDDs/day over the past 72 hrs, but are now at the very top of that range, which is just above the 5-yr avg. The forecast thereafter quickly moderates, however, so more work needs to be done to sustain higher #natgas prices.

Trade Alert for Subscribers. Email alert with trade discussion sent to subscribers. Discussion also available on the site's Portfolio Page. More: celsiusenergy.co/p/fund-hold…... Click here to subscribe: celsiusenergy.net/p/support-…
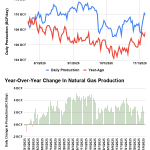
While LNG export demand has climbed to record highs, #natgas production has also extended its own recovery, topping 110 BCF/d yesterday based on my calculated pipeline data. Year-over-year production gains roughly offset LNG export gains. Don’t be surprised to see output reach new highs above 112 BCF/d before the end of the year, if not this month.

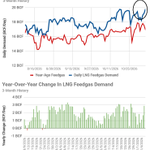
Per today’s early-cycle pipeline data, LNG feedgas demand will rise to 19.8 BCF/d, up +2.9 BCF/d vs last year & a new all-time high, just topping the 19.75 BCF/d from Oct 18. Today’s gain will be driven by gains at Corpus Christi & Freeport. As is always the case, especially the latter, we will have to see if this holds up in tonight’s late-cycle data. #Natgas

Exceptionally mild conditions will continue to dominate the Eastern Seaboard today. Morning lows across the I-95 Corridor from Washington, DC to Boston, MA will only bottom out in the lower 60s, 20F-30F above-avg and 5F-10F warmer than average afternoon HIGHs in some areas. Unsurprisingly, this will keep a lid on #natgas heating demand, even as the Heartland finally begins to cool.

In stark contrast to the financial markets today, the weather pattern across the Lower 48 is remarkably quiet with the National Weather Service Watches, Warnings, & Advisories map showing a near absence of alerts. You don’t often see it this quiet, especially during the volatile Fall. #Natgas

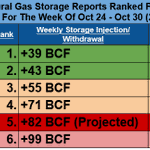
For today’s EIA #Natgas Storage Report covering October 24-30, I’m projecting a +82 BCF injection, 21 BCF bearish vs the 5-yr avg & the second largest build for the week in the last 5 yrs, below only 2022’s +99 BCF. The EIA will release official numbers at 10:30 AM ET.

Colder-than-normal temperatures continue across Europe, completely opposite the US. As a result, European #natgas storage registered its largest daily withdrawal of the season yesterday at -10 BCF/d, more than 8 BCF bullish vs the 5-yr avg. The European withdrawal season has gotten off to a fast start, driving the storage deficit vs the 5-yr avg back above -600 BCF.

While certainly not outright bullish, there has been a cooling trend in the near-term temperature outlook, especially after November 11. Forecast Gas-Weighted Degree Days (GWDDs) remain below the 5-yr avg but most days are now at the upper limit of their 72-hour forecast range. This is likely contributing to some of the strength in #natgas prices today.


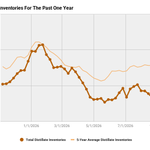
With today’s EIA Petroleum Status Report, distillate inventories dropped into the single digits at 99.3 MMbbls for the first time since May 2, 2003. Storage levels are at a -14.1 MMbbls or -12.4% deficit vs the 5-yr avg. #oil

With the European #natgas storage withdrawal season seemingly underway, I am now issuing projections for the end-of-season storage minimum in April 2027. This projection currently stands at 1051 BCF, 39 BCF lower than last yr and 526 BCF below the 5-yr avg. It will, of course, be heavily revised in the weeks to come depending on how winter temperatures & supply from the Middle East evolve. See more on my projection here: celsiusenergy.net/p/european…

#Natgas has tumbled over the past few days and, by my calculations, is down -1.5 BCF/d per today’s early-cycle pipeline data (though this will probably be revised somewhat higher in tonight’s late-cycle data). The fact that gas prices are only marginally higher today despite this news shows just how strongly the unseasonably mild temperature outlook is impacting the sector.

With unseasonably mild to record-setting warmth dominating the Eastern US today, Gas-Weighted Degree Days (GWDDs) will fall to a remarkably weak 6.2 GWDDs, far and away a 5-yr low for November 3, more than 3 GWDDs below 2022’s 9.6 GWDD previous low. As a result, I am projecting a double-digit +13 BCF/d daily #natgas storage injection for today, just days removed from the typical transition to withdrawals.

Over the weekend, the near-term temperature outlook has not meaningfully improved with 14-day Gas-Weighted Degree Days (GWDDs) well below-avg & at 5-yr lows for the period per both the GFS and ECWMF models. Such a forecast would typically favor additional selling pressure on #natgas to start the week, though I suspect that investors have already largely priced in the mild conditions & that further downside will be limited.

While #natgas heating demand has been in the dumps, powerburn has been quietly reclaiming share of the powerstack. Over the past week, its share has averaged 41.1%, the second most for the week in the last 5 yrs. And yesterday, share topped 45%.

Failure to launch: After a brief spike in mid-October, #natgas res/com heating demand has stalled out as temperatures remain unseasonably mild across much of the Lower 48. Demand is consistently trailing year-ago levels by at least -5 BCF/d. Don’t look for this to meaningfully improve for another week or so and, even then, will remain marginal.

European #natgas inventories registered a new season-high drawdown yesterday at -5 BCF/d (5-yr avg: +3 BCF/d) as chilly temperatures dominate the continent. As a result, storage dropped below 2021 levels and is back at 5-yr lows.


LNG feedgas demand rose to a new high of 0.84 BCF/d yesterday as the plant is finally beginning to ramp up again. It wasn’t quite enough to send nationwide export demand to a new all-time high but volumes continue to hover just shy of new records in the 19.0-19.5 BCF/d. #Natgas

European #natgas inventories registered their largest daily storage withdrawal of the Fall yesterday at -3 BCF/d. With colder-than-normal temperatures expected across much of the continent for the next 1-2 weeks, it is increasingly likely that inventories have peaked for the season. European storage would enter the withdrawal season at an impressive -576 BCF deficit vs the 5-yr avg & right at 5-year lows.
