

Follow for market updates, stats, and alpha
Dubai
Joined April 2023
- Tweets11.2K
- Following1.3K
- Followers65.8K
- Likes5K


8 VALUATION MULTIPLES EVERY INVESTOR MUST KNOW 🧵
Most people lose money not by picking bad companies, but by paying the wrong price.
Here is the exact cheatsheet you need before buying your next stock:
🔹️️️️️️ P/E (Price-to-Earnings)
Price ÷ EPS
How much you pay for every $1 of net profit. Best for mature, profitable firms.
🔹️️️️️️ PEG (P/E to Growth)
P/E ÷ EPS Growth Rate
Is the valuation justified by growth speed? Under 1.0 is often a steal.
🔹️️️️️️ EV/EBITDA
Enterprise Value ÷ EBITDA
Values the whole business against core operational cash, ignoring debt differences.
🔹️️️️️️ EV/Sales
Enterprise Value ÷ Revenue
The go-to metric for fast-growing companies that aren't net-profitable yet.
🔹️️️️️️ P/B (Price-to-Book)
Price ÷ Book Value (Assets - Liabilities)
Best for banks and financial institutions where book value reflects real liquid assets.
🔹️️️️️️ P/TBV (Price-to-Tangible Book)
Price ÷ (Book Value - Goodwill/Intangibles)
Strips out hype and paper goodwill to show what you're paying for physical assets.
🔹️️️️️️ P/FCF (Price-to-Free Cash Flow)
Market Cap ÷ Free Cash Flow
Accounting profits can be faked; cash in the bank cannot. Best for real cash cows.
🔹️️️️️️ Dividend Yield
Annual Dividend ÷ Share Price
Your baseline cash yield without having to sell a single share.
⚠️ The Rule:
No single multiple works for everything. A 10x P/E can be a value trap, while a 35x P/E can be cheap if growth is 50%.
Match the metric to the business model before you buy.

ANTHROPIC OWES $637B. AND THAT'S ITS STRATEGY
Broadcom $161B
SpaceXAI $120B
Google $114B
Amazon $110B
Microsoft $45B
Nscale $45B
Lambda $41B
The fastest way to become "too big to fail": owe everyone at once. If Anthropic goes down, so do the ones it owes.
Well played
🤖 Made with AI

Don’t skip the numbers 👇
THIS YEAR HAS THREE STREAKS THAT HAVE NEVER BROKEN. ALL AT ONCE
🔸 Fed hiking cycles since 1983: S&P up in every completed multi-meeting cycle. 7/7. Average ~10%.
🔸 Midterms since 1950: higher 12 months later every single time. 19/19. Average ~15%.
🔸 November through June after a midterm, since 1942: positive every time. 21/21. Average +16.6%.
🔹 Bonus: 12 months after the final hike, 7/8 positive, ~20%. Only miss was May 2000, right in the middle of the dot-com collapse.
2026 has all three lined up. Hiking cycle. Midterm. The Nov-June window that has never failed.
History doesn’t guarantee anything. But ignoring a 7/7, a 19/19 and a 21/21 in the same year is how you end up explaining the rally after it’s already gone.


YOUR PORTFOLIO IS IN DANGER IF YOU HAVEN'T SEEN THESE NUMBERS
Chipmaker stocks are trading at a 23% discount to the S&P.
• Forward P/E: S&P 500: 19.0x
• Information Technology: 19.6x
• Semiconductors: 14.6x
In other words, the sector driving the entire trend is cheaper than the very index it’s inflating. Tech as a whole is actually more expensive than the broader market. Yet chips inside it are on sale.
Two possibilities: Either the market is already pricing in the cycle's peak, remembering how fast semiconductor margins can compress. Or everyone is fixated on capex and funding, and the multiples simply haven't caught up yet.

SPACEX’S $470B CAPEX BILL MAY BE LESS SCARY THAN IT LOOKS 🚀
Everyone’s focused on how $SPCX will fund its 13 GW buildout. But AI revenue could ramp much faster than the market expects.
My model points to:
🔹 $314B in FY2027 revenue
🔸 $122B in Q4 2027 alone
🔹 ~$90B in cash already on the balance sheet
If operating cash flow and existing cash cover ~$290B of capex, SpaceX would need to raise roughly $180B in debt, less than 1x its projected year-end EBITDA run rate.
Of course, that depends on execution. If capacity ramps slower, revenue falls, but capex needs should also come down.
📉 A correction toward $100 is still possible. But from H2 2027, once the risks tied to insider share unlocks fade, I expect $SPCX to resume its climb.

BINANCE DRAINED?! MASSIVE EXPLOIT RUMORS SEND BTC CRASHING BELOW $78.5K 🚨‼️
On-chain analysts on X are sounding the alarm over a potential massive exploit hitting Binance.
While not officially confirmed yet, multiple reports suggest an exchange wallet was drained to a fresh EOA address. Even more suspicious: the smart contract call behind the transaction was allegedly funded directly through Tornado Cash.
No official word from the Binance team yet. Stay sharp and protect your funds while we wait for updates.


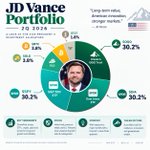
JD VANCE’S PORTFOLIO IS BASICALLY AN AGGRESSIVE BET ON THE ENTIRE U.S. ECONOMY
The U.S. Vice President isn’t just backing America on the podium. His disclosed personal book is an ultra-concentrated vote of confidence in domestic equities.
📊 Estimated breakdown:
🔸 S&P 500 ($SPY): ~30.2%
🔹 Nasdaq 100 ($QQQ): ~30.2%
🔸 Dow Jones ($DIA): ~30.2%
🔹 Gold ($GLD): ~3.8%
🔸 Bitcoin ($BTC): ~3.8%
🔹 20+ Year Treasuries ($TLT): ~1.8%
💰 Over 90% of the entire stack is locked into just three broad-market index ETFs.
No obscure small-caps, no foreign stock picking, and almost zero defensive cash. Just a massive, blunt allocation to large-cap America, capped off with an equal hedge between digital and physical sound money (BTCandGLD).
Simple enough to look boring. Aggressive enough to print if U.S. exceptionalism keeps dominating.
Is this the cleanest modern index strategy or an index-bubble trap waiting to happen?

PCE DATA CONFIRM WARSH'S WORDS ABOUT HIGH INFLATION
🔻 Headline PCE: 3.6% YoY (exp: 3.6% | prev: 3.4%) / +0.5% MoM (exp: 0.5% | prev: 0.3%)
🔻 Core PCE: 3.1% YoY (exp: 3.1% | prev: 3.0%) / +0.3% MoM (exp: 0.3% | prev: 0.3%)
US Q3 GDP data came in at 3.4%, higher than expectations of 3.2%.
What does this mean for the economy?
Strong GDP and high inflation are an absolute open door for a new rate hike. Markets are pricing roughly an 81% chance of a December hike, and today’s data could push those odds higher.
A hike isn’t guaranteed, but the combination of resilient growth and sticky inflation gives the Fed more reason to keep policy tight — or even tighten further.


Now the bar is moving:
• Can revenue scale fast enough?
• Can margins survive the infrastructure bill?
• Can the business fund growth without constantly raising capital?
For more, follow
@CoinPostMedia
And join Coin Post in Telegram:
t.me/+9ne9q1Ju33UyMGZi
Don't forget to like and retweet the tweet below. Thank you!
teapawt.org/CoinPostMedia/status/2…

