

CEO @CryptoTaxAudit | Expert in crypto capital gain calculation, tax return prep & IRS audit defense | Call for a consultation
United States
Joined June 2016
- Tweets9.8K
- Following476
- Followers15.4K
- Likes15.8K




Pinned Tweet
🚨CRYPTO INVESTORS: DO NOT SCAN THIS QR CODE
A fake IRS notice is being mailed to crypto holders directing them to a bogus “Digital Asset Compliance Portal.”
It looks very convincing. It isn’t real.
Please spread the word.

ALT Fake IRS Digital Asset Compliance Portal notice targeting crypto investors, with the scam QR code crossed out in red.
What can you do if you've experienced a cryptocurrency theft?
First of all, you want to start collecting data about what happened. You want to document everything.
If you have a receipt showing that you bought a Ledger from a party that's now been shown to be illegitimate, save that receipt.
If you can capture the transactions from your hardware wallet, download the transaction history and save it as a PDF.
You want to preserve the wallet addresses, transaction hashes, dates, amounts, and any communications relating to the incident.
Then you want to go to the FBI's Internet Crime Complaint Center, the IC3.
They have a webaite where you can report cryptocurrency fraud and cybercrime. You basically get to tell your story.
Now, filing a complaint doesn't guarantee that you'll recover your cryptocurrency. But the FBI uses these reports to identify patterns, aggregate information, and investigate criminal activity.
And from a tax perspective, having a timely IC3 report can help support your account of what happened.
You can also report it to your local police station. If you have a copy of that police report, that can help establish a record of the incident.
Now, these reports don't automatically prove that you're entitled to a tax deduction.
But they're important pieces of evidence.
The IRS wants to see the hallmarks of someone who has genuinely experienced a theft.
You had a police report, you had an IC3 report, and you maybe have copies of the transactions.
We can look at those transactions. You can also work with companies that perform blockchain forensic analysis to help trace where the cryptocurrency went.
They may be able to identify whether the receiving address has connections to known criminal activity.
All of these things can help establish what happened.
You also need to document how much you originally paid for the cryptocurrency and whether there's any reasonable prospect of recovering it.
That's important because a qualifying theft loss deduction is generally based on your adjusted tax basis, subject to the applicable rules, not simply the cryptocurrency's market value when it was stolen.
If you've lost a significant amount of cryptocurrency, the potential tax consequences can be substantial.
But the amount of any deduction and the actual tax benefit will depend on your individual circumstances.
So don't allow shame to prevent you from documenting what happened.
If you've experienced one of these hardware wallet attacks, protect your remaining assets, preserve your evidence, and get knowledgeable tax advice.
You may have options available, but you need the documentation to support them.
It's been very unnerving seeing how sophisticated the attacks on hardware wallets have become.
We've seen attacks involving Coldcard, Trezor, and more recently Ledger.
Some attacks involve concerns about whether your device is secure. Others involve trying to trick you into disclosing the private keys or recovery phrase to your hardware wallet.
I think the lesson we've all learned from this is that you really want to consider a multi-signature wallet.
With multi-signature security, a transaction requires approval from more than one private key.
You can use different hardware devices, like a Trezor or Ledger, as part of that setup.
And you want to consider using different manufacturers. That's called multi-vendor.
You also want to consider keeping those devices in separate secure locations. That's called multi-site.
The benefit is that you're not relying on a single device or a single private key to protect your cryptocurrency.
If one device is compromised, an attacker may still be unable to move your funds without the additional signatures.
Now, it doesn't eliminate every risk. You still need to protect your recovery phrases, verify transactions carefully, and make sure your backup arrangements are secure.
But if you're serious about self-custody, multi-sig, multi-vendor, and multi-site security can provide important additional layers of defense.
If you haven't been reporting all your cryptocurrency income, there are several ways to address that.
Everybody's situation is different, and the right approach depends on what happened in the previous years.
One option is the IRS Voluntary Disclosure Practice.
This program is focused on people who have willfully failed to comply with tax laws and may face criminal exposure.
The intent is that you come forward, disclose the noncompliance, cooperate with the IRS, and resolve the taxes, penalties, and interest that you owe.
A voluntary disclosure may help you avoid criminal prosecution, but it doesn't automatically guarantee immunity.
The second option is a proposed voluntary disclosure program specifically for digital asset owners.
The House Ways and Means Committee has advanced legislation that would direct the Treasury Department to establish a program for taxpayers who haven't properly reported their digital asset transactions.
Now, this is still proposed legislation. It isn't an active IRS amnesty program.
Under the proposal, qualifying taxpayers could amend prior-year tax returns and pay the additional tax and interest owed, with reduced penalties depending on their circumstances.
For taxpayers who certify that their noncompliance wasn't willful or fraudulent, the proposed penalty could be zero on the first $25,000 of additional tax deficiency per applicable year, with a 5% penalty on the amount above that if they act within the program's initial 12 months.
Different, higher penalties would apply to taxpayers who cannot make that certification, and penalties could also increase for later submissions.
That's an important distinction. The $25,000 threshold relates to additional tax owed, not simply $25,000 of unreported cryptocurrency income.
The proposal also includes rules about which previous tax years must be corrected.
So depending on your situation, this could become an attractive way to address past cryptocurrency reporting problems if the legislation becomes law.
The third option is to correct your previous returns through the normal IRS procedures.
If you made mistakes in prior years, you may be able to file amended tax returns or delinquent returns, depending on your circumstances.
And you also want to make sure you're reporting all your cryptocurrency transactions correctly going forward.
But simply starting to report correctly this year doesn't automatically resolve the tax exposure from previous years.
That's why it's important to look at the entire situation before deciding what to do.
Bitcoin has been around for about 17 years. The IRS has been issuing guidance on cryptocurrency taxation since 2014.
They didn't just fall off the log.
And if you continue to think and treat the IRS as though they will never find you, I think you need to wake up and study a little bit about what artificial intelligence and blockchain analysis technology can do.
I think if you've received a 6174-A, it is informational.
Although it sounds scary, they're not necessarily coming after you. However, it is educational, and you may be at risk in the future.
Now, if you've not been reporting your crypto income in the past, you may have a tax exposure.
If you haven't reported any crypto income, that exposure could be even greater.
By sending you this letter, the IRS is telling you that it has information suggesting you've had cryptocurrency activity.
That doesn't automatically mean you're being audited, but you should take the letter seriously.
The key thing to do, if you haven't been reporting everything, is to review your previous tax returns and determine whether corrections are necessary.
Everybody's situation is different. I don't want to make any sweeping statements about it.
Receiving a 6174-A doesn't itself require a response to the IRS, but it doesn't mean you should ignore possible reporting errors either.
If you've failed to report cryptocurrency transactions, you should understand your exposure and what options are available to correct the situation.
And that's where having somebody who understands cryptocurrency taxation becomes important.
The IRS knows how to tax cryptocurrency. They put out their first guidance back in 2014.
And if you continue to think and treat the IRS as though they will never find you, I think you need to wake up and understand how much information is becoming available to them.
For tax year 2026, the IRS is going to take full advantage of 1099-DAs to audit people more strategically.
It's strategic, and it takes less time for them. It's also a little more focused for you.
The way they'll do this, and I've gone through audits before with brokerage accounts of this nature, is that on your brokerage 1099 statement, it'll list transactions where the cost basis is known and transactions where the cost basis is unknown.
In the cases where it's unknown, they're going to ask you to state how much the cost basis is.
Hopefully, you already reported that in your tax return, and it's not a question.
If you haven't reported it, then it's going to get a little more ugly.
I don't think it is going to be as aggressive as we've seen in the past. However, it will be more focused and directed.
And you either answered the questions when you did your original tax return and can point to the answer, or you're going to look bad.
Clinton Donnelly retweeted

🚨Warning: Tax Shield may cause excessive confidence.
What you do with that confidence is entirely up to you.
Disclaimer: Giving the IRS the finger is not part of our recommended audit defense strategy.
Let our tax experts do the talking.
cryptotaxaudit.com/taxshield

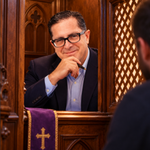
🚨THE CRYPTO TAX CONFESSION BOX IS OPEN.
"Forgive me, Clinton, for I have traded."
For the next 24 hours, my DMs are open to your crypto tax questions.
I've never done this before.
DM me your question. I'll answer as many as I personally can.

ALT Clinton Donnelly of CryptoTaxAudit sits inside a traditional wooden church confession booth, wearing black-framed glasses, a navy blazer, and a light blue shirt. He rests his chin on his hand while holding a pen, smiling slightly as he listens to someone on the other side of a wooden lattice screen. A purple cloth with a gold cross hangs over the booth. The humorous image promotes Clinton’s 24-hour Crypto Tax Confession Box, inviting people to DM him their crypto tax questions.
It's been very unnerving seeing how sophisticated the attacks on hardware wallets have become.
We've seen attacks involving Coldcard, Trezor, and more recently Ledger.
Now, what happens if you've experienced a loss because of one of these cryptocurrency attacks?
Is there any tax consolation on this?
Under IRS rules, certain cryptocurrency theft losses may qualify for a tax deduction if the cryptocurrency was held in a transaction entered into for profit.
This is an important distinction because not every cryptocurrency scam or theft automatically qualifies.
The IRS looks at the circumstances of the loss, whether it qualifies as theft under applicable law, and whether you have a reasonable prospect of recovering the stolen funds.
If you held cryptocurrency for investment purposes and it was genuinely stolen, you may qualify for a theft loss deduction.
And the tax treatment can be significantly different from a normal capital loss.
With capital losses, there's generally a $3,000 annual limit on the amount of net capital losses individuals can deduct against ordinary income, with unused losses carried forward.
A qualifying investment theft loss may receive different treatment under Section 165 of the Internal Revenue Code.
These losses are generally calculated using Form 4684, and the reporting treatment depends on the circumstances.
For individual investors, qualifying losses involving income-producing property may be reported through Schedule A.
The actual deduction also depends on your adjusted tax basis, any reimbursements, and whether there's a reasonable prospect of recovery.
That's why it's important to understand exactly what happened before claiming anything.
Now, one of the biggest challenges is proving that you actually experienced a theft.
If you print out the transaction history of the Ethereum on your Ledger wallet, and all of a sudden it's transferred to another address and there's nothing left, to you, that's a theft.
But to the IRS, that may simply look like you moved cryptocurrency from one address to another.
It doesn't say theft on the blockchain.
And now you've got to demonstrate that it was an unauthorized transfer and that you genuinely suffered a loss.
That's the challenge.
We've actually had one of our clients audited on a theft loss, and you can imagine the IRS is very concerned about these.
People are basically saying, "Whoa, I just lost $100,000, and I'm reducing my taxes based on that amount."
That's a big move.
And the IRS is, of course, a skeptical organization.
They want to see that the loss was genuine and that the deduction is supported by the evidence.
If you've experienced a significant cryptocurrency theft, don't automatically assume that the entire market value of what you lost is deductible.
But don't automatically assume there's no tax relief available either.
The important thing is to determine whether you have a qualifying loss and calculate it correctly.
On a 1099-DA, there'll be two types of transactions reported.
One will be a transaction where they know the cost basis. You bought it for this price, you sold it for that price, you held it for this long, and here's how much you made.
That's very cut and dry from the IRS point of view. That's cut and dry, and that needs to be reported on your tax return.
Those are called covered transactions. That's the IRS parlance. It's called a covered transaction because they know both sides.
An uncovered transaction is a transaction that came from out of nowhere, where the exchange knows what they sold it for, but they have no idea when that asset was purchased, when it was acquired, or how much the price was.
So they call that an uncovered transaction.
In a typical IRS audit, in this scenario, what the IRS agent does is come back and say, "Here are all these uncovered transactions where the 1099 doesn't say what the cost basis is, and we're going to ask you to tell us exactly what the cost basis is."
And you can do that if you've had a full gain calculation.
We can respond on a line-item basis, with the cost and purchase date for each one of those transactions.
And that's kind of how they audit it.
If you've reported it honestly, you're going to do fine in an audit.
Why are we having a significant increase in CP2000 and CP2501 letters?
These are typical. We're having an increase in these for people who reported for the 2024 tax return.
This is the one filed last year, and the IRS is just now getting around to processing it.
Why are they getting around to processing it?
Well, there had been a bit of a moratorium on the processing of these letters over the last two years. It was partly post-COVID, partly poor guidance, and partly they realized it was a down market. What good was it to hassle people in a down market?
But now, the IRS administration is focused on increasing collections.
You know, this is a big thing for the IRS. I mean, the IRS is the money-making machine for the United States government. They are the ones who bring in the money that pays for everything else.
So it's very simple to measure the effectiveness of the IRS: how much money, tax-wise, did you bring in this year?
Now, there are a lot of issues, and of course, the IRS has had some big layoffs. A year ago, they laid off roughly 25% of their workers.
I understand they're just going through another layoff. I'm not sure what percentage that entails.
But at the same time they've had these layoffs, they've also increased their tax collections, which is bringing in more with fewer people.
That's a good thing, you know, from most business points of view.
So this is what's going on with the IRS. They're continuing to increase collections.
Now, the issue most people should be aware of is that the IRS is using artificial intelligence, and they're using Palantir technology to better sift through all the data they have to determine who to send these letters to.
Now, you can imagine at the IRS, they have 160-plus million tax returns.
Let's say 25% of them have some cryptocurrency related to them, so you're looking at about 40 million, and you've only got 5,000 or so auditors.
And they can only handle so many audits at a time. They want to have better success.
So the IRS is really stepping up. They're using AI technology and Palantir data technology, which also includes their tool that reads the blockchain.
You know, they're getting pretty accurate at going after people.
So if you haven't been current on your crypto reporting, make this the year you become 100% current.
Give our offices a call if you'd like to discuss how you get compliant in prior years, if necessary.
The IRS may have been dumb in the past, but they're not staying dumb.
They're actually getting smarter and smarter.
And don't fool yourself with a straw man image of who the IRS is.
Clinton Donnelly retweeted
IRS audit protection from experts you can trust
cryptotaxaudit.com/taxshield

We're seeing an increase in the informational letters, the 6173, 6174, and 6174-A letters.
The reason we're seeing an increase in those is really that it's been a steady stream. They send out approximately 10,000 letters a month with the same stuff.
And it's basically a multi-year effort to "educate" cryptocurrency investors on how they need to report their crypto income.
Why are they doing that?
Well, it's in order to head off, in the future, you as a crypto investor saying, "Well, I didn't know how to report on my taxes. You haven't given me any clarity."
They'll go back and say, "Remember when we sent you this letter? Yeah, that's the clarity you got right there."
And that's what that's about.
It's a multi-year effort because they have a real difficult time communicating directly to the crypto space.
So they've gotten people's names, Social Security numbers, and addresses from Coinbase, Kraken, and some of these other places that they've subpoenaed.
And they're just collecting the names, and they're sending out emails to everybody who gets one.
So ultimately, over time, everybody will get one of those letters who is an active crypto trader using U.S. exchanges.
A CP2000 is a computer-generated audit letter, and it requires a response.
The CP2000 letter generally goes this way: "We know that you didn't report all your cryptocurrency income related to..."
And then they'll quote a 1099 that you had received, like Coinbase or Kraken.
It'll list all the transactions on that 1099, and it'll say, "Therefore, you owe us so much more additional tax."
They're conveniently calculating it for you.
Usually, these are wrong. They made a mistake.
So what you have to do is, in a very prompt way, respond back to them and say, "No, I did report this, and here's my response. Here's how I reported it."
And if you're confused about how to do that, we'll be happy to help you if you call our office.
Now, how do you avoid getting a CP2000 letter?
Well, it has to do with, first of all, making sure when you do your tax return, you enter in all your 1099 forms, from whatever source they're from.
If you fail to enter one in, then the IRS will recognize that, and you'll get a CP2000 letter.
It's a computer-generated audit. It's very focused. It's not auditing your entire return, just the question it asked, and it requires a very focused answer as well.
Now, how can you avoid these in the future?
Well, in addition to making sure you account for all your 1099s on your tax return, when you prepare your tax return, you want to make sure, if you're using an accountant, that when they prepare the tax return, they specifically enter the company name and the EIN, which would be Coinbase and Coinbase's EIN.
EIN is an employer tax ID number.
Because that's how they correlate to make sure every one of these is accounted for.
If you just enter numbers off the 1099 without identifying the EIN or the company name, the IRS may not make that connection, and you may get this letter.
What is a CP2501 letter?
A CP2501 letter is a precursor letter to a CP2000.
A CP2000 says, "Hey, you forgot to report this income. Here's the additional tax you owe. Prove us wrong."
The CP2501 is a little more tactful, and it says, "Hey, looks like maybe you forgot to report some income related to..." It'll list the 1099. "Can you check your records and let us know?"
So they aren't going that extra mile of actually assessing a tax on you.
You want to respond to CP2501 as correctly and quickly as you can, generally within about a month, to prevent the CP2000 from coming.
Otherwise, you have to respond to the CP2000 with the same answer, which drags out.
Any letter from the IRS is serious. Some of them are educational, but many are informational and require action.
If you need that, you should contact our offices, and we can help you set it up.
And you should generally use someone knowledgeable about cryptocurrencies themselves, so they can provide an intelligent response without continually asking you stupid questions, because they're going to give a stupid response to the IRS.
Clinton Donnelly retweeted
Can you delay paying the IRS by filing a tax extension?
Not quite.
An IRS extension gives you six extra months to file your tax return, not to pay your taxes.
For tax year 2025, which we reported in 2026, that's the first year we had 1099-DAs.
And a concession had been made to exchanges because of the difficulty of implementing the new regulations. They were given an extra year, so they didn't have to report cost basis.
However, starting in 2027 for the 2026 tax year, you will get 1099s, and where the exchanges know it, they're going to report the cost basis.
This is big for the IRS.
Think of this past year as basically a transition year.
The IRS has had, and partly I will take some credit, a very difficult time auditing crypto investors.
They took an attitude of, "We're going to recalculate the gains and tell you you did it wrong."
And we came back and just destroyed them again and again and again.
We know personally that we got one company fired from being an IRS contractor to provide gain calculation services.
They got fired because we destroyed them four times in a row and humiliated them to the point where their management basically said, "We don't use that company anymore."
The transition with 1099-DA is that crypto can now get audited in a similar way to stocks and bonds.
Now, how will that happen?
On a 1099-DA, there'll be two types of transactions reported.
One will be a transaction where they know the cost basis. You bought it for this price, you sold it for that price, you held it for this long, and here's how much you made.
That's very cut and dry from the IRS point of view. That's cut and dry, and that needs to be reported on your tax return.
Those are called covered transactions. That's the IRS parlance. It's called a covered transaction because they know both sides.
An uncovered transaction is a transaction that came from out of nowhere, where the exchange knows what they sold it for, but they have no idea when that asset was purchased, when it was acquired, or how much the price was.
So they call that an uncovered transaction.
In a typical IRS audit, in this scenario, what the IRS agent does is come back and say, "Here are all these uncovered transactions where the 1099 doesn't say what the cost basis is, and we're going to ask you to tell us exactly what the cost basis is."
And you can do that if you've had a full gain calculation.
We can respond on a line-item basis, with the cost and purchase date for each one of those transactions.
And that's kind of how they audit it.
If you've reported it honestly, you're going to do fine in an audit.
Zohran Mamdani was recently asked a very simple question:
“What does socialism mean to you?”
And his answer was revealing.
He said, essentially, that everyone should have what they need to live a dignified life, and that it is the government’s job to deliver that.
Now stop right there.
Because whenever somebody says, “The government will provide it,” there is one question that has to come next:
With whose money?
The government does not create wealth.
It does not grow food.
It does not build companies.
It does not magically manufacture money without consequences.
To provide something to one person, it first has to take resources from somewhere else.
That is the part of the conversation politicians love to skip.
Mamdani calls his philosophy democratic socialism.
My concern is the underlying idea that the state increasingly becomes responsible for deciding what you need and then redistributing resources to provide it.
That is statism.
It is the belief that more and more of society’s problems should ultimately be solved by the state.
And once you accept that premise, there is another uncomfortable question:
Where is the limit?
How much can the government take from the people producing income in order to satisfy promises made to everyone else?
Politicians love the phrase “fair share.” Bernie Sanders has used it for years.
But what exactly is a fair share?
• 10%?
• 20%?
• 40%?
• 50%?
At what point does “fair share” simply mean: More than you’re paying right now.
And here's something else that gets mangled in this debate.
A substantial share of American households owe no federal individual income tax in a given year. That does not mean they pay no taxes at all. Many still pay payroll taxes, sales taxes, property taxes and other taxes.
But politically, you can still create a dangerous incentive when more voters are promised benefits paid for primarily by somebody else.
Because giving things away is incredibly popular. Paying for them is considerably less popular.
And eventually, if you make it sufficiently expensive to build businesses, invest capital, create jobs or accumulate wealth, people change their behavior.
• Capital moves.
• Businesses move.
• People move.
You cannot endlessly treat productive economic activity as an unlimited ATM and then act surprised when somebody eventually pulls the card out.
That is the part of socialism that deserves much more scrutiny.
The question is not whether people deserve dignity.
Of course they do.
The real question is: Who decides what a dignified life requires, who pays for it, and how much power are you willing to give the government to make that happen?
Because “the government will provide for you” sounds wonderful.
Until you remember that the government first has to get the money from somebody else.
People ask me all the time, “How can I reduce my taxes?”
And sometimes the most powerful strategies are also the simplest.
One of them is where you live.
If you live in a high-tax state, state taxes can take a significant additional piece of your income and investment gains every single year.
Take someone making $200,000.
If their effective state tax burden on that income is around 10%, that's potentially another $20,000 a year.
Do that for 10 years and you're talking about $200,000.
Now compare that with states like Florida, Texas or Nevada, which don't impose a traditional individual state income tax.
That's a very real difference.
And for crypto investors who have a significant gain in a bull market, state residency can potentially mean tens of thousands, or even hundreds of thousands, of dollars in additional tax.
But there's an important catch.
You can't simply decide on December 30th that you “live in Florida” because you're about to sell your crypto.
States like California and New York take residency and domicile seriously. If you're moving for tax purposes, it has to be a genuine move supported by the facts.
Where is your home?
Where do you actually spend your time?
Where are your important personal and financial connections?
Those details matter.
So when people ask me about sophisticated ways to reduce their tax bill, sometimes the answer isn't a complicated tax structure.
Sometimes it's understanding how much the state you choose to live in is actually costing you.
There’s a tax strategy almost nobody talks about, and for crypto investors, it can be incredibly useful.
It’s called a superseding return.
This matters because professional crypto gain calculations can take time. If you have years of transactions, multiple exchanges, wallets, missing records, or complicated activity, you may not have your final numbers ready by April 15th.
The same thing happens with partnership income. You may be waiting months for a final K-1.
So what do you do?
One option is to file an extension.
Your estimated tax still needs to be paid by the original deadline, but the extension gives you additional time to file the return.
Then, if you file a return and better information becomes available before your extended filing deadline, you may be able to file a superseding return.
That second return replaces the first one.
And there’s a reason I pay attention to this.
Years ago, I had a client who had already filed his tax return. We later identified a different reporting position that would have resulted in roughly a $500,000 refund.
We filed an amended return.
Then we waited.
Six months. Eight months. Ten months. Eventually, around a year later, the IRS rejected the amended return.
That experience completely changed the way I looked at amended returns.
Now, that doesn’t mean every amended return gets rejected. But if you have the opportunity to correct a return before the filing deadline using a superseding return, that can be a much stronger position than discovering the problem after the deadline and relying entirely on the amended-return process.
The National Taxpayer Advocate has also encouraged taxpayers to understand and use superseding returns where appropriate.
For crypto investors waiting on a professional gain calculation, this can be an extremely useful strategy.
File the extension. Pay your best reasonable estimate on time. Use the extra filing window to get the numbers right.
And if necessary, supersede the earlier return before that deadline closes.