
Stock investor, inventor and rusty geologist.
Joined June 2022
- Tweets716
- Following78
- Followers368
- Likes332



There is a secure email now just for the $MMTMF $MMY.V Monument Mining buyback project. Later I will add a Signal group so people can chat without others seeing their phone numbers. The email is [email protected]
It is up and working, very secure, just tested that this email works. This is the std format for buyback project
Handle and contact point as in Geodan at CEO.CA, Shares (me) 440,000.
You can add additional info, even suggestions if you wish, but this will be enough for me to tally. I am involved with a software development project, so I will be very busy meeting on that this week, in case you do not hear from me for a while. Thanks everyone for your help. We have 11 million shares so far, but more are coming in as soon as a secure email address is created for some people that wanted that first. Cheers For background on why this is a good idea. seekingalpha.com/article/495…
And Wow, this one impresses even me.
IRR on EV is 95% as is.
To Grok: The IRR I think is on mkt cap what about if on EV, and what if on EV if they sell Murchison for $50 million, or for $100 million? On an enterprise-value basis the yield (and therefore the simple IRR of a buyback) is much higher. Selling Murchison makes it higher still. Current baseline (USD) Market cap ≈ $184 million Cash ≈ $110 million, Current EV ≈ $74 million Ongoing free-cash-flow / earnings power ≈ $65–70 million Basis Yield / approximate IRR Calculation Market cap ~38% $70M ÷ $184M Current EV ~95% $70M ÷ $74M The ~38% figure used earlier is the yield on market cap.
On EV the same cash flows are being bought against a much smaller residual value, so the theoretical yield jumps to roughly 90–100%. If Murchison is sold A sale converts the Murchison asset into cash, which reduces enterprise value dollar-for-dollar (market cap held constant for the residual calculation). Murchison sale price New residual EV Yield on residual EV Notes $50 million ~$24 million ~290% IRR $70M ÷ $24M $100 million ~–$26 million Negative residual EV Market assigns negative value to Selinsing’s earnings after cash + Murchison proceeds At a $50 million sale, the residual EV left for Selinsing is only ~$24 million against ~$70 million of annual free cash flow — an extreme yield. At a $100 million sale, residual EV turns negative.
The market would be implying that Selinsing’s ongoing earnings power has less than zero value once Murchison cash is recognized. Bottom line for the buyback The IRR of buying back stock at the current price is already very high on a market-cap basis (~35–40%). On an EV basis it is dramatically higher (~95%). Any meaningful sale of Murchison further increases the residual yield on the operating business and makes a buyback at today’s prices even more accretive to remaining shareholders. So IRR is 95% on EV as is, and infinity, incalculable, if Murchison is sold, on buybacks. No need to sell Murchison; just to buybacks- EPS will skyrocket, which means the stock price will skyrocket. Cheers
Here is another way to look at $MMTMF Monument Mining buybacks. Buybacks = IRR on EV is 95% as is. If they firesale Murchison then it is ~290% IRR To Grok: The IRR I think is on mkt cap what about if on EV, and what if on EV if they sell Murchison for $50 million, or for $100 million?
On an enterprise-value basis the yield (and therefore the simple IRR of a buyback) is much higher. Selling Murchison makes it higher still. Current baseline ($USD) Market cap ≈ $184 million Cash ≈ $110 million, Current EV ≈ $74 million Ongoing free-cash-flow / earnings power ≈ $65–70 million Basis Yield / approximate IRR Calculation Market cap ~38% $70M ÷ $184M Current EV ~95% $70M ÷ $74M The ~38% figure used earlier is the yield on market cap.
On EV the same cash flows are being bought against a much smaller residual value, so the theoretical yield jumps to roughly 90–100%. If Murchison is sold a sale converts the Murchison asset into cash, which reduces enterprise value dollar-for-dollar (market cap held constant for the residual calculation). Murchison sale price New residual EV Yield on residual EV Notes: $50 million ~$24 million ~290% IRR $70M ÷ $24M $100 million ~–$26 million Negative residual EV Market assigns negative value to Selinsing’s earnings after cash + Murchison proceeds
At a $50 million sale, the residual EV left for Selinsing is only ~$24 million against ~$70 million of annual free cash flow — an extreme yield. At a $100 million sale, residual EV turns negative. The market would be implying that Selinsing’s ongoing earnings power has less than zero value once Murchison cash is recognized.
Bottom line for the buyback The IRR of buying back stock at the current price is already very high on a market-cap basis (~35–40%). On an EV basis it is dramatically higher (~95%). Any meaningful sale of Murchison further increases the residual yield on the operating business and makes a buyback at today’s prices even more accretive to remaining shareholders.
So IRR is 95% on EV as is, and infinity, incalculable, if Murchison is sold at a reasonable value, and 290% IRR if Murchison sold very cheap when buybacks are done. No need to sell Murchison; just do buybacks- EPS will skyrocket, which means the stock price will skyrocket. Cheers
Looked at the valuation of Monument Mining $MMTMF some more, and the below indicates it is less than free.
The Seeking Alpha article by hedge fund Cedar Creek pointed out that "Since current cash is likely in excess of $125 million, Monument trades at a ridiculous valuation of less than one times earnings net of cash.: Today, in USD $191 million market cap, -$125 million cash = $66 million EV, just counting cash; add in from Cedar Partners article "In addition, Odyssey Gold, another smaller junior miner, who purchased Monument's Tuckanarra assets in Australia a few years ago is reportedly nearing production that could result in $20 to 30 million in aggregate earnings for Monument over the next few years. " seekingalpha.com/article/495…
Then the assets they have at Murchison, AI says are worth $140ish million usd. A mining company CEO who has looked in that general area says that they could sell it for $100 million. So call it $10 million on Tuckanarra NPV and $100 million for Murchison, so $66 million EV just on cash, then - $ 110 million = negative real EV of $44 million, so PE ratio could be seen as below Zero, so it can be seen as not just less than 1 PE, it can be seen as less than zero.
If so, this is one of the most spectacular values ever in the stock market. I put this through AI and it said the numbers and ratios are right if Murchison can be sold for $100 million. "The calculation itself $66M EV (on cash) − $110M (your $10M + $100M) = negative ~$44M is arithmetically correct with those inputs. What this actually says in a sum-of-the-parts sense is that the market is assigning zero or negative value to the producing Selinsing mine (which just generated ~$69M of net income) after giving credit for cash + the estimated Australian assets. That is an extremely cheap SOTP outcome if the asset values prove out."

The Seeking Alpha article on $MMTMF Monument Mining pointed out that "Since current cash is likely in excess of $125 million, Monument trades at a ridiculous valuation of less than one times earnings net of cash.: Today, in USD $191 million market cap, -$125 million cash = $66 million EV, just counting cash; add in from Cedar Partners article "In addition, Odyssey Gold, another smaller junior miner, who purchased Monument's Tuckanarra assets in Australia a few years ago is reportedly nearing production that could result in $20 to 30 million in aggregate earnings for Monument over the next few years. " seekingalpha.com/article/495…
Then there are the assets they have at Murchison, including a mill and mine and multiple deposits, AI says are worth $140ish million USD. A mining company CEO who has looked in that general area told me that they could sell it for $100 million. So call it $10 million on Tuckanarra NPV and $100 million for Murchison so $66 million EV just on cash, then - $ 110 million = negative real EV of $44 million, so PE ratio could be seen as below Zero, so it can be seen as not just less than 1 PE, it can be seen as less than zero. Correct me if wrong, there may be an error in my calcs? If so, this is one of the most spectacular values ever in the stock market.
I put this through AI and it said the numbers and ratios are right if Murchison can be sold for $100 million. "The calculation itself $66M EV (on cash) − $110M (your $10M + $100M) = negative ~$44M is arithmetically correct with those inputs. What this actually says in a sum-of-the-parts sense is that the market is assigning zero or negative value to the producing Selinsing mine (which just generated ~$69M of net income) after giving credit for cash + the estimated Australian assets. That is an extremely cheap SOTP outcome if the asset values prove out."
If you have a position in Monument and want to see buybacks done by the company. Please go to @Geodan | CEO.CA and provide your share counts. This article explains how buybacks can super compound EPS for $MMTMF
Darp101 on X: "Monument Mining, the Best Buyback Stock in the World? Yes, and it can 10 to 165 Bag Due to a 55% Free Cashflow Yield on EV and $102 Million in Cash Monument Mining Limited (TSXV: $MMY.v / OTC: $MMTMF) Strategic Share Buyback Analysis Report August 2026 MetricValue Share xitter.cf/DarpResearch/sta…" / X


An investment fund has taken a position in $MMTMF Monument Mining and is advocating in a Seeking Alpha article that Monuments do agressive stock buybacks, they say-- "In regards to Monument trading at one times earnings, a wise management or board would be buying back shares aggressively in order to increase the value for remaining shareholders. Unfortunately, many managers still focus on the gross dollar amount of net income and shareholder equity and think their job is to increase those two figures. That is not the optimal way to look at it. The optimal way to look at it is to recognize that the manager's job is to increase intrinsic value per share. If one is focused on increasing shareholder equity, a stock repurchase makes no sense. After all, a repurchase reduces shareholder equity, the metric they are focused on increasing. When managers are focused on increasing per share value, they recognize that buying back stock below intrinsic value is massively accretive to remaining shareholders." Monument Mining: An Absurdly Low Valuation And Substantial Value For Shareholders | Seeking Alpha seekingalpha.com/article/495…
This lines up with my article here on X and shareholder resolution to bring about buybacks here: Darp101 on X: "Monument Mining Buyback Proposal: $MMY.V $MMTMF A comparison of investing cash into Monument's own shares versus building a new mine in Australia or buying another producer. This is the bottom-line chart. The complete report is attached. A path to a 40-bagger is feasible. xitter.cf/DarpResearch/sta…" / X

With the firm’s reported assets under management around $43.8 million (as of December 31, 2025), So, Cedar has $44 million but it has been an activist.
Activism and control positions: Successful campaigns have included Solitron Devices (SODI)—Eriksen led a proxy effort, joined the board, became CEO, and the stock has been a major multi-bagger from the mid-single digits. Other examples include involvement with PharmChem (PCHM, later sold), TSR Inc. (sold at a high IRR), and others. These have been meaningful contributors.
This is very positive, I would not be surprised if without Cedar a shareholder vote on buybacks would win, with them even better. They have a good record, Inception was January 15, 2006. Returns are reported net of fees and expenses and have compared favorably to major indices over the long term (especially small- and micro-cap benchmarks):
As of September 30, 2026 (about 20¾ years): Average annual return 15.2%; cumulative return 1,764.7% ($100,000 invested at inception would have grown to roughly $1.865 million).static1.squarespace.com
2026 YTD through Q3: +19.9% (Q3: +6.5%). Small-cap indices were down in Q3 while large caps rose modestly.
There is hope for $MMY $MMTMF Monument Mining! Globex $GMX.TO $GLBXF should have done buybacks years ago when it was in .60s and I was telling them to. There is even a private discussion group of major gmx:native shareholders on X trying to bring it about, which I am a member of. I gave up and others did too and sold. Then 2 hours ago ... They did it! +5.71% already on day. TORONTO, Oct. 09, 2026 (GLOBE NEWSWIRE) -- GLOBEX MINING ENTERPRISES INC. (GMX GLBXF – OTCQX International in the US) is pleased to announce that the Toronto Stock Exchange (“TSX”) has approved Globex’s normal course issuer bid (“NCIB”). Under the NCIB, Globex will be entitled to repurchase for cancellation up to 1,000,000 common shares, representing approximately 1.76% of Globex’s issued and outstanding shares as of October 1, 2026, over a twelve-month period starting on October 15, 2026 and ending on October 14, 2027.
OK if Globex can do it $MMY Monument which is 55% FCF yield on EV with $110 million cash just sitting in the bank and no debt with $186usd million mkt cap can too. $MMY has crashed about 30% in last the last 8 trading days after I announced the company had found a technicality to bar a Resolution by Shareholders for them to do a tender for 17%, a substantial bid.
So folks there is hope, if Globex can wake up, $MMY can wake up too. And instead of paying near 4 times more than they could of when I told Globex to do a buyback, Monument can buy at the bottom. Hmm MMY.V - Monument Mining | CEO.CA shows $266 million Cad mkt cap with $110usd million cash and no debt? If so and that is what CEO is saying, then $186 million usd mkt cap - $110 million cash = only $76 million EV, that seems impossible, but is what CEO.CA is quoting. If so if the price does not go up they can buy 99% of the stock and boost EPS 100 times to $22 a share in about 18 months with their Free CashFlow and cash, seems something is off, but those are the numbers. Cheers
Two major energy news items:
1. Paris – The International Energy Agency (IEA) announced on Oct. 3 that member countries have released 325 million barrels of oil and oil‑derived products from strategic reserves, out of the 400 million barrels pledged in March. This update came one day after G‑7 countries, in coordination with the IEA, agreed to immediately release 100 million barrels of diesel and crude oil to ease global supply concerns caused by fallout from the US–Iran war.
So it looks like Trump will reach the election without a total U.S. fuel shortage and without $12 diesel — except perhaps in California. Much of this release will be diesel, not crude. The world has finally realized, seven months later, that it is running out of oil and refined products. But these releases do not solve the underlying shortage; it’s like getting a second credit card to pay off part of the first — it only deepens the hole. Interesting to see what happens Monday. Source: straitstimes.com/world/325-m…
2. Canada’s energy policy reversal: In keeping with the same misguided policies that left Europe heavily dependent on Russian oil and gas — shutting down nuclear plants, banning drilling, imposing “windfall taxes” that discourage production — Canada spent years following the same path: blocking pipelines, talking about ending oil production, and generally trying to keep up with Europe’s self‑inflicted energy crisis. Mark Carney was at the center of much of this. Now, with Alberta preparing to vote on whether to leave Canada after decades of being economically abused by the national government, Carney has suddenly declared that it is a national emergency to “drill, baby, drill,” build pipelines, and even subsidize the same oil and gas infrastructure he and his allies spent years blocking and sabotaging. Seriously. Source: pm.gc.ca/en/news/news-releas…
Carney now says: “Today, the world faces an energy crisis across three dimensions: our cost of living, our climate, and our sovereignty increasingly depend on our nation’s ability to supply and control its own energy… Canada is positioned to become the leading supplier of clean and conventional energy… Canada needs to build fast and build together.”
Some good news in all this madness. A few people are finally waking up. For Carney, what he previously claimed was ruining the climate is now — apparently — good for the climate. So he says.
How do we end this madness and avoid future huge problems 10, 20, 30 years from now? My tiny contribution is simply pointing it out online with my tiny voice.
Back to the good news: what was obvious 30 years ago is finally being recognized by some policymakers. Maybe the U.S. will get two new refineries capable of processing our light Permian crude.
Maybe Alberta will stop being sabotaged and finally get enough pipelines to move its oil and gas — which would be fantastic for Alberta producers. No more $0.75 AECO gas and huge oil discounts because they can’t get product out of the province.
Maybe Europe will wake up and decide it actually wants energy instead of trying to prevent it — great news for Tenaz ($ATUUF), a gas producer there.
Maybe Germany will restart its nuclear plants and build new ones, and maybe the UK will follow. Fantastic for U miners and $SMR builders.
I have a feeling the 50‑year anti‑energy hysteria is finally fading. I sure hope so. It would be a major boost for energy companies, even though it would eventually reduce energy prices — because it will take years to rebuild supply after the Iran War depletion and the above-mentioned energy self-sabotage by some countries. Cheers.

youtu.be/Z688psMus58?t=174 qued he says $500 $ASIC Cad $346usd!!!!!! That is the lowest AISC cost in the world for a pure gold mine I am aware of. Sixty North $SXNTF and $SXTY.v They operated at that in past, and are restarting it in 2027 unless regulators get hyper out of line in Canada.
Monument Mining Buyback Proposal: $MMY.V $MMTMF
A comparison of investing cash into Monument's own shares versus building a new mine in Australia or buying another producer. This is the bottom-line chart. The complete report is attached. A path to a 40-bagger is feasible. cdn-ceo-ca.s3.amazonaws.com/….
Monument Mining, the Best Buyback Stock in the World? Yes, and it can 10 to 165 Bag Due to a 55% Free Cashflow Yield on EV and $102 Million in Cash
Monument Mining Limited (TSXV: $MMY.v / OTC: $MMTMF) Strategic Share Buyback Analysis Report August 2026
MetricValue
Share Price$0.60
Shares Outstanding343 million
Market Capitalization$221 million
Cash (no debt)$102 million
Annual Free Cash Flow$84 million (≈ $7 M / month)
EPS / Net Income$0.22 / ≈ $75.46 million
P/E Ratio2.5×
Enterprise Value / EV/EBITDA$153 million / 1.38×
Assumed Constant Gold Price$4,400 / oz
The company is deeply undervalued. In fact, out of over 30,000 stocks the author screened, Monument ranked first as the stock that would benefit more from a stock buyback than any other stock in the world. Large-scale tender offers (substantial issuer bids) under TSX rules permit rapid capital return beyond normal NCIB limits.
2. Key Modeling Assumptions
• Monthly FCF = $7 million; annual Net Income held constant at $75.46 million unless noted.
• First 40% tender completes 1 November 2026 at $0.68 (≈13% premium). Cost = $93.3 million. Cash used first.
• After the initial tender + next $50 million of FCF buys, 100% of monthly FCF is used for buybacks (Paths 1–3).
• All paths terminate on ≈ 1 August 2028 (the date Path 1 reaches 98% share retirement).
• Path 5: $40 M CapEx over 12 months from Nov 2026; production from Nov 2027 at 15 koz/yr, $2,000 AISC → ≈ +$25 M annual NI/FCF.
• Annual sales assumed ≈ $180 million for per-share illustrations.
3. The Paths
Path 1 — “Ineffective” Aggressive Buyback (Fixed $0.68)
Market never re-rates; share price stays $0.60. 40% tender at $0.68, then +$50 M at $0.68, then 100% of monthly FCF retires shares at the fixed $0.68 until only 2% of original shares remain (6.86 million). Maximizes share count reduction.
Endpoint: EPS $11.00 | 9× PE → $99.00 | Cash/share ≈ $3.00 (≈ $5 after two more months)
Sales/share ≈ $26. This would happen in just 2 years.
Path 2 — Neutral Valuation (Maintains 2.5× PE)
Identical first tender + $50 M tranche at $0.68. Thereafter stock trades at constant 2.5× PE so buyback price rises with EPS; fewer shares are retired.
(2.5X PE).Endpoint: Shares ≈ 80.9 M | EPS ≈ $0.93 | Price ≈ $2.33
Path 2B — Neutral + Terminal 9X PE Re-rating
Identical to Path 2 during the program. At the August 2028 endpoint the stock is assumed to re-rate to 9× PE.
Endpoint: Shares ≈ 80.9 M | EPS ≈ $0.93 | Price = $8.37 (9× PE).
Path 3 — Effective Buyback (Re-rates to 9× PE After Initial Tender)
Same first two tranches at $0.68. Immediately after the $50 M buy the stock re-rates to 9× PE and tracks that multiple thereafter.
Endpoint: Shares ≈ 115.6 M | EPS ≈ $0.65 | Price ≈ $5.87 (9× PE).
Path 4 — Do Nothing
No buybacks. All FCF accumulates as cash. Market cap rises by FCF generated; 2.5× PE maintained on earnings.
Endpoint: Shares 343 M | EPS $0.22 | Price ≈ $1.07 | Cash ≈ $249 M.
Path 5 — Restart Burnakura
The primary figure uses the 9× PE case.
Primary Endpoint (9× PE): EPS ≈ $0.29 | Price = $2.64 per share | Multiple = 4.4×.
(Conservative 2.5× PE case ≈ $0.73 per share | 1.2×.
4. Comprehensive Comparison Table (Endpoint ≈ 1 August 2028)
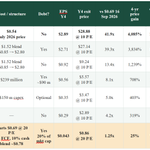
PathDescriptionShares Left (m)Final EPSFinal PriceMultipleCAGR*
1Ineffective BB (fixed $0.68)6.86$11.00$99.00 (9×)165×≈ 1,243%
2Neutral (tracks 2.5× PE)80.9$0.93$2.33 (2.5×)3.9×≈ 99%
2BNeutral + terminal 9× PE80.9$0.93$8.37 (9×)14.0×≈ 282%
3Effective (to 9× after tender)115.6$0.65$5.87 (9×)9.8×≈ 219%
4Do Nothing343$0.22$1.071.8×≈ 34%
5Burnakura restart (9× PE)343$0.29$2.644.4×≈ 112%
*CAGR calculated from current $0.60 (≈ mid-August 2026) to the August 2028 endpoint (≈ 1.97 years).
5. Why Path 1 Produces Dramatically Superior Returns
1. Maximum share retirement at the lowest price. Fixed $0.68 allows every FCF dollar to retire ≈ 1.47 shares. Rising prices in Paths 2/2B/3 shrink that number dramatically. Path 1 retires 98% of equity.
2. Explosive EPS accretion. Fixed earnings power divided by a 50× smaller share count produces $11.00 EPS.
3. Asymmetric upside for remaining owners. The “ineffective” program ends with EPS so high that any reasonable multiple (5–9×) produces a $55–$99 stock. Continuing shareholders own a far larger percentage of the same cash-flow engine.
4. Highest ROI on capital. Buybacks at a deep discount to intrinsic value convert low-yielding cash into permanent ownership reduction — superior to holding cash (Path 4) or a modest and quite profitable production expansion (Path 5).
5. Practical under TSX rules. Substantial issuer bids / tender offers allow rapid, large-scale retirement that normal NCIBs cannot match.
6. EPS Trajectory Charts
Path 1’s explosive rise results purely from collapsing the share count while earnings power remains constant. All other paths produce only modest (or zero) EPS accretion. Figure 1 – See Bottom
Figure 2 – Linear Scale (better for comparing Paths 2–5)
See Bottom
7. Conclusion
At a 2.5× PE, $102 million net cash and $84 million annual FCF, Monument is the best candidate for aggressive capital return out of over 30,000 stocks the author screened. Path 1 (fixed-price “ineffective” buyback) produces by far the highest EPS, residual ownership stake, terminal equity value and shareholder CAGR. Path 1 is unlikely if the market wakes up to the fact that Monument is in a position to skyrocket their EPS via buybacks. However if the stock market does not re-rate the PE over 9PE it is feasible for the company to retire 98% of its stock and achieve over $10.00 EPS, but with more time.
Path 2B and Path 3, which incorporate full or partial re-rating, deliver lower returns but still delivers outstanding retruns of 289% CAGR and 219% CAGR respectively, because of higher purchase prices limit share retirement speed. Paths 4 and 5 create the least amount of value.
Management should prioritize a large tender offer as soon as practicable, followed by systematic retirement of the remaining float with free cash flow. The mathematics of share-count reduction at a deeply undervalued price create far more shareholder value than holding cash or deploying it into a new mine. In fact to achieve Path1 type EPS results would require the company to buy about 9 Kalgoorlie Super Pit-scale mines, which would cost in the neighborhood of $100 billion dollars.
This report is primarily about the incredibly good buyback aspect. For general info on Monument and their operations here is a newer video of the CEO. youtu.be/KJ7_fkgHfE8
— End of Report —
Prepared for article use | Modeling as of August 2026 | Not investment advice
I see .67 close USD over 10% gain. I was buying at .62 midday, first I realized the move. I put out an article and took a hike, then ate dinner; what a close! 11% up. Had no idea till now. I have a truckload of it :-)

Dave at $SXNTY Sixty North is fantastic at shareholder communication, I inherently trust him as he does not dodge questions and I see a logical and non-conformist mind. I suggested if legal bulk sample stockpile and grade the pile before operating milling OKed. ---
I had made reference to a hypothetical 500,000 oz deposit at 50,000 to 70,000 opy production. This should have been clearer. It was if fact the Discovery Mine's production profile I was referencing that started at 100 tpd and ramped up to 265 tpd. The Mon is being designed at 100 tpd, 300 day per year operation. The balance of days will be planned and unplanned shutdowns. The tasks remaining include getting all management plans approved. This is our number one priority. There are crews on site as reported in the last NR, finishing the mill pad preparation, building roads, basic maintenance, and infrastructure installation. We will build as we are allowed and turn it on when we can. I have mined up here before. Two points to consider. 1) all rock is wet in a stockpile. Always. 2) it will drop to -40 degrees in winter. A large pile or wet rock at -40 will freeze like concrete and will remain frozen ALL summer. I know. I've done it. Ive trued using large excavators to try to move a frozen ore pile. It is very difficult and very expensive. We prepared our operation so we can commence mining immediately upon crew arrival. We can feed the mill directly from the mine without the need for a stockpile. This is our plan.
My note see my prior post with video interview of Dave Darp101 on X: "New video out on $SXNTF Sixty North , maybe the most positive video yet. He is talking over 40,000oz a year of gold production possible with a small staff, which is ridiculously profitable if it happens. youtube.com/watch?v=J73h-qfU… Just waiting on approvals, everything + people" / X
New video out on $SXNTF Sixty North , maybe the most positive video yet. He is talking over 40,000oz a year of gold production possible with a small staff, which is ridiculously profitable if it happens. youtube.com/watch?v=J73h-qfU… Just waiting on approvals, everything + people are on site. Maybe 2026 gold pour? That is 3 times more gold production than $GGGOF, which has $100ish usd million mkt cap. $SXNTF has $8.5 million mkt cap and I am an investor in $GGGOF. So if they go into production about that rate, a 30-bagger seems quite possible.
$AIS.AX and $ARSRF Aeris, which I consider the best copper miner value in the world (they have gold and silver too), just put out a new presentation. Things are changing fast there, so glad they updated. static.seekingalpha.com/uplo…
$AIS.AX and $ARSRF Aeris, IB flashed a tech signal to me that it should double by September. If that happens, I will pay attention to those signals in the future. The funny thing is, it should double by then due to value, strange how both tend to line up. A 6PE Copper/Gold/Silver miner in safe Aussie that just this week increased reserves by 70% is the best Copper miner value I am aware of. hotcopper.com.au/attachments…