

Global Communications & Public Affairs Manager @YouEmployed | Global Shaper @BrusselShapers | Alumnus @UofGlasgow and @collegeofeurope
Brussels, Belgium
Joined November 2011
- Tweets9.3K
- Following407
- Followers802
- Likes19.6K





David Timis retweeted

SpaceX may own 16% of all world’s AI compute by end 2027.
I’d bet it’s just the beginning.


David Timis retweeted

Palantir's Net Retention Rate has now accelerated for 12 straight quarters...
One of one.
$PLTR

David Timis retweeted
PALANTIR SHOWS FINE-TUNED NVIDIA 4B AI MODEL BEATING GPT-6 ASTRA & CLAUDE SONNET 5.5 AT A FRACTION OF THE COST
In its Q3 business update, $PLTR revealed that a fine-tuned $NVDA Nemotron 3 Nano model with just 4 billion parameters outperformed much larger frontier models on a real-world customer task.
The results, based on classifying requests for information for construction firm McCarthy:
• NVIDIA Nemotron 4B: ~75% accuracy at $0.10 per million tokens.
• Claude Sonnet 5.5: ~66% accuracy at $4 per million tokens.
• GPT-6 Astra: ~62% accuracy at $20 per million tokens.
Palantir says the fine-tuned models are expected to save McCarthy approximately 30,000 drafting hours annually.
Separately, NVIDIA itself is now training open AI models on its own supply chain data inside Palantir's Ontology, spanning millions of parts and thousands of suppliers.
Jensen Huang says the partnership combines NVIDIA's Nemotron models with Palantir's Ontology to:
“Reason, plan and orchestrate the journey from wafer to token.”


David Timis retweeted

First take on $AAPL (stock flat). Business overall is solid despite navigating higher memory costs and higher prices to consumers. Sept guidance in 45 mins.
1. iPhone was up 17.5% vs. Street at up 15.5%. Rock solid.
2. Mac got a 22% price increase for the full quarter and beat estimates. Sales up 24% yy, compared to Street looking for up 15%. Shows how much Mac bucked the Intel announcement for a slowdown in consumer we say last week.
3. iPad got a 21% price increase and missed. Sept was down 10% yy vs. Street at flat. For December, Street is at down 3%. They should beat that with the new models just announced.
4. Gross margin, adjusting for tariff refund was 46.9% vs. Street at 47.5%. Shows the price increase is not offsetting memory costs.
5. Services were in line up 10%, compared to up 12% in June.
6. Wearables down 8% vs. Street at down 4%. I dont know what to make of this.
David Timis retweeted

Hyperscaler CDS are breaking out to new highs.
This is bad news for neoclouds, particularly for $CRWV.
Investors will be asking for higher interest rates to fund hyperscaler data center projects, which leads to even higher rates for neoclouds.

David Timis retweeted

2027 is shaping up to be biggest step change in AI power density yet:
• $NVDA Rubin Ultra ~500kW per rack
• $AMD MI500 ~1,000kW per rack
• $AMZN Trainium4 ~330kW per rack
• $GOOGL TPU v9 ~200kW per rack
Traditional data centers were built for CPU racks of just ~10kW so this shift will require a lot of upgrades to existing facilities and fundamentally different electrical and liquid cooling systems in new builds.

David Timis retweeted

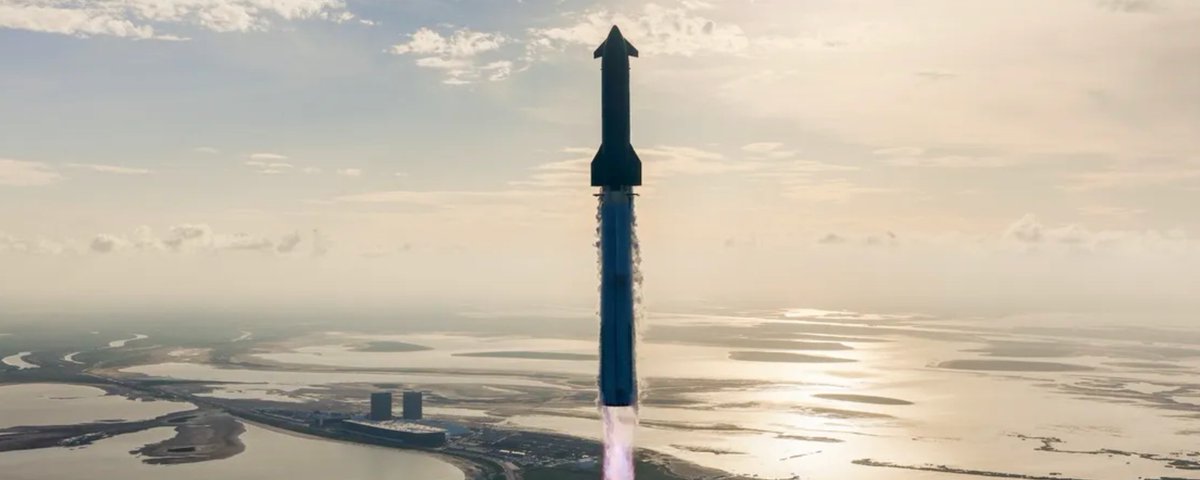
on spaceX vs Tesla
very crudely:
robotaxi is a bigger opportunity than starlink
but orbital compute is a *much* bigger opportunity than robotaxi
and optimus requires more baking time than orbital compute
and Optimus's success is predicated on access to gobsmacking amounts of superintelligence
On our modeling, compared against the no merger case, even if merged at the current share price ratio Tesla shareholders would be ~1.6x better off in 2031 while SpaceX shareholders would be ~2x better off.
On a longer timeframe (2036) Tesla shareholders would be ~5x better off having merged whereas SpaceX shareholders should be more indifferent ~1.3x better off.
So the fair premium depends heavily on your timeframe. On longer time horizons SpaceX shareholders should be asking for a discount. On shorter time horizons Tesla shareholders should be asking for a premium.
But everyone is better off with a merged entity.
A 30% premium paid on Tesla's share price to day would effectively split the difference on the 2031 time frame; Tesla acquired at a 50% discount would equilibreate return differentials on the 2036 time horizon.



David Timis retweeted

Tesla just had a HUGE month in Europe!
Almost every country that has reported October vehicle registration so far is up big for $TSLA
The standout is Norway. Tesla had its best October on record there and finished as the #1 brand with 9.8% share, just 55 cars ahead of Toyota
And it did that in a month where Chinese brands hit a record 22.5% of new cars in Norway
Germany, Italy and the UK are the big ones though, and they have yet to report
FSD is being approved across the continent and should drive further Tesla purchases heading into 2027 as the expected full approval happens


David Timis retweeted

$GOOG is a printing machine
The more they invest, the larger their returns
Remember this as the share price drops into the buy zone.




David Timis retweeted
Aggregate free cash flow of $MSFT, $AMZN, $META, and $GOOG has turned negative for the first time in decades.
I think this is a major turning point for market valuations in general.
Let me explain simply:
In the 20th century, most large corporations were capex-heavy industrial businesses, and their continuous capital requirements helped keep valuations lower. The S&P 500 averaged around 15x earnings.
In the 21st century, however, low-capex software and internet companies came to dominate the market, and valuations rose. Since 2010, the S&P 500 has averaged roughly 18–20x earnings.
Now, those large, historically capex-light companies are becoming capex-heavy, much like the industrial companies of the 20th century.
For them to continue being valued at 25–30x earnings, they will have to prove that the margins on their compute infrastructure businesses can be comparable to those of their capex-light businesses, such as software and advertising.
Until we see that happen, their valuations will likely remain depressed, which could lead to a choppy market given the enormous weight these companies carry in the major indexes.
So, prepare for more choppiness until we really see high AI infrastructure margins.
