
Started the Sunday Energy Tidbits research memo in 1998 & still love everything energy. Energy powers the world! Posts are for info only!
Calgary, Alberta
Joined August 2018
- Tweets25.4K
- Following78
- Followers16.4K
- Likes1K






Protein tidbits from Tyson Foods Q4 call.
"Protein is the biggest opportunity in food, a $273 billion retail category, growing faster than overall food. 7 in 10 Americans say they are trying to eat more protein. Younger households spend more than 3x what their parents spend on protein each week". CEO
"I've seen some numbers that says 50% of the protein consumed in the U.S. by 2030 is going to be in chicken." COO
"Yes. I'll talk about pork. Americans are trying to -- 7 out of 10 Americans are trying to eat more pork protein, but pork is the third in that list. And so yes, there is a roughly 10% vertically integrated and it had a huge tailwind for us last year. And it certainly looks like a headwind for us going forward. But let me -- Ms. Heather, let me talk about pork just from a general standpoint. Bellies, we have access to bellies, and by putting it under one president, we're going to put the product in highest and best use. And so turning bellies into Wright Brand or Jimmy Dean bacon, turning hams into Hillshire lunch meat and turning trim into Hillshire sausage is much more important to us over time." COO.
Thx @themotleyfool


All income consumers want more protein but majority of growth for protein in prepared meats is in premium tier prepared meats ie. higher income meat eaters.
Tyson Foods Q4 call Q&A.
"we can produce the best products in the value tier. We can produce the best products in the mainstream tier, and we do that with Tyson, Jimmy Dean, Hillshire, Ball Park and State Fair every day. And we can also produce great products in the premium tier. And by the way, that's where the majority of the growth is across our portfolio. The growth is in the premium tier. We have Hillshire Reserve, Aidells, Wright Brand, Smart Chicken and soon to be Nature Raised Farms for those consumers that want a super premium, high-attribute products. So I think we're really well positioned with the consumer, and we can meet that consumer where they are." CEO
"Yes. 70% of Americans say they want to eat more protein. And so we want to make sure that we have an offering to -- irregardless of your income level. And so this trifurcated consumer, we're going to go to where they are. As a matter of fact, we're already off and running. And so we'll make the product for every consumer out there". COO.
Thx @themotleyfool

All income consumers want more protein but majority of growth for protein in prepared meats is in premium tier prepared meats ie. higher income meat eaters.
Tyson Foods Q4 call Q&A.
"we can produce the best products in the value tier. We can produce the best products in the mainstream tier, and we do that with Tyson, Jimmy Dean, Hillshire, Ball Park and State Fair every day. And we can also produce great products in the premium tier. And by the way, that's where the majority of the growth is across our portfolio. The growth is in the premium tier. We have Hillshire Reserve, Aidells, Wright Brand, Smart Chicken and soon to be Nature Raised Farms for those consumers that want a super premium, high-attribute products. So I think we're really well positioned with the consumer, and we can meet that consumer where they are." CEO
"Yes. 70% of Americans say they want to eat more protein. And so we want to make sure that we have an offering to -- irregardless of your income level. And so this trifurcated consumer, we're going to go to where they are. As a matter of fact, we're already off and running. And so we'll make the product for every consumer out there". COO.
Thx @themotleyfool
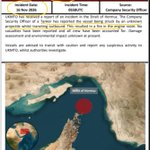
At least so far, the arrival of the 3rd US aircraft carrier in the Persian Gulf hasn't stopped attacks on tankers transiting the Strait of Hormuz.
@UK_MTO #208-26 "...an attack involving a tanker transiting the Strait of Hormuz, disabling the vessel and resulting in an engine room fire...."
#oott


A third US aircraft carrier strike group has arrived in the Persian Gulf region, according to a defense official, bringing the number of such vessels in the Middle East to three bloomberg.com/news/articles/…

"Thanksgiving Travel Expected to Dip Slightly Compared to Last Year.... AAA projects 81.5 million Americans will travel at least 50 miles from home for Thanksgiving between Tuesday, November 24 and Monday, November 30. This year’s domestic travel forecast is slightly lower than last year when 81.6 million people traveled for the holiday. That’s a 0.1% decline which is about 121, 000 fewer travelers. This year’s forecast ends a three-year streak of record Thanksgiving travel that started in 2023. The number of people taking flights and roads trips is a bit lower than last year, but travelers taking cruises, buses, and trains are on the rise." @AAAnews
#oott
newsroom.aaa.com/2026/11/aaa…
1
1,045
Dan Tsubouchi retweeted

BREAKING: Customers are reporting difficulty accessing online accounts at banks including Bank of America, Chase, J.P. Morgan, U.S. Bank and Wells Fargo. apnews.com/article/bank-outa…

Dan Tsubouchi retweeted
Negative near-term China economic recovery indicator.
Negative China economic indicator:
Another brutal month for fixed asset investment, worst month since Covid. Oct -8.1% YoY (est -7.0%), which followed Sept -7.2% YoY, Aug -7.2% YoY, July -6.7% YoY, June -5.7% YoY, May -4.1% YoY, Apr -1.6% YoY. There were two positive months Mar at +1.7% YoY and Feb +1.8% YoY. But those followed Jan n/a, Dec -3.8% YoY, Nov -2.6% YoY and Oct -1.7% YoY.
Fixed-asset investment YoY% change has been weak since Trump Liberation Day.
YoY%
Oct -8.1% YoY (est -7.0%)
Sept -7.2%
Aug -7.2%
July -6.7%
June -5.7%
May -4.1%
Apr -1.6%
Mar +1.7%
Feb +1.8%
Jan n/a
Dec -3.8%
Nov -2.6%
Oct -1.7%
Sep -0.5%
Aug +0.5%
Jul +1.6%
Jun +2.8%
May +3.7%
Apr +4.0%
Mar +4.2% YoY
#oott Thx @business

Dan Tsubouchi retweeted
Negative China economy indicator: Chinese consumers still aren't spending much.
Weak China consumer retail sales in Oct at +0.4% YoY (est +0.8%), which follows Sept +1.1% YoY, Aug at +0.4% YoY, July at +0.6% YoY, June at +1.0% YoY, the brutal May at -0.6% YoY and Apr at +0.2% YoY.
China consumer slowdown began to fall off in the aftermath of Trump Apr 2025 Liberation Day.
Oct +0.4% YoY, Est +0.8%
Sept +1.1%
Aug +0.4%
July +0.6%
June +1.0%
May -0.6%
Apr +0.2%
Mar +1.7%
Jan/Feb no available data
2025
Dec +0.9%
Nov +1.3%
Oct +2.9%
Sep +3.0%
Aug +3.4%
Jul +3.7%
Jun +4.8%
May +6.4%
Apr +5.1%
Mar +5.9%
No Jan/Feb data
2024
Dec +3.7%
Nov +3.0%
Oct +4.8%
Sep +3.2%
Aug +2.1%
July +2.7%
Jun +2.0%
May +3.7%
Apr +2.3%
Mar +3.1%
No Jan/Feb data
2023
Dec +7.4%
Nov +10.1%
Nowhere near pre-Covid steady +8-11%.
#oott Thx @business.

Dan Tsubouchi retweeted
Continued big negative for China consumers.
Chinese consumer's most important asset, their home values, keep going lower.
China New Home Prices down MoM for 41 consecutive months with Oct -0.15% MoM.
China 2nd Hand Home prices down MoM for 42 consecutive months with Oct -0.24% MoM.
MoM % drops increased post Trump Liberation Day.
MoM% change, New Homes vs 2nd Hand Homes:
Oct: -0.15%, -0.24%
Sept: -0.14%. -0.26%
Aug: -0.17%. -0.31%
July: -0.18%. -0.29%
June: -0.15%. -0.32%
May: -0.20%. -0.26%
Apr: -0.19%. -0.23%
Mar: -0.21%. -0.24%.
Feb: -0.28%. -0.43%
Jan: -0.37%. -0.54%
Dec: -0.37%. -0.70%
Nov: -0.39%. -0.66%
Oct: -0.45%. -0.66%
Sept: -0.41%. -0.61%
Aug: -0.30%. -0.58%
July: -0.31%. -0.55%.
Thx @business
#oott


Continued big negative for China consumers.
Chinese consumer's most important asset, their home values, keep going lower.
China New Home Prices down MoM for 41 consecutive months with Oct -0.15% MoM.
China 2nd Hand Home prices down MoM for 42 consecutive months with Oct -0.24% MoM.
MoM % drops increased post Trump Liberation Day.
MoM% change, New Homes vs 2nd Hand Homes:
Oct: -0.15%, -0.24%
Sept: -0.14%. -0.26%
Aug: -0.17%. -0.31%
July: -0.18%. -0.29%
June: -0.15%. -0.32%
May: -0.20%. -0.26%
Apr: -0.19%. -0.23%
Mar: -0.21%. -0.24%.
Feb: -0.28%. -0.43%
Jan: -0.37%. -0.54%
Dec: -0.37%. -0.70%
Nov: -0.39%. -0.66%
Oct: -0.45%. -0.66%
Sept: -0.41%. -0.61%
Aug: -0.30%. -0.58%
July: -0.31%. -0.55%.
Thx @business
#oott
Negative near-term China economic recovery indicator.
Negative China economic indicator:
Another brutal month for fixed asset investment, worst month since Covid. Oct -8.1% YoY (est -7.0%), which followed Sept -7.2% YoY, Aug -7.2% YoY, July -6.7% YoY, June -5.7% YoY, May -4.1% YoY, Apr -1.6% YoY. There were two positive months Mar at +1.7% YoY and Feb +1.8% YoY. But those followed Jan n/a, Dec -3.8% YoY, Nov -2.6% YoY and Oct -1.7% YoY.
Fixed-asset investment YoY% change has been weak since Trump Liberation Day.
YoY%
Oct -8.1% YoY (est -7.0%)
Sept -7.2%
Aug -7.2%
July -6.7%
June -5.7%
May -4.1%
Apr -1.6%
Mar +1.7%
Feb +1.8%
Jan n/a
Dec -3.8%
Nov -2.6%
Oct -1.7%
Sep -0.5%
Aug +0.5%
Jul +1.6%
Jun +2.8%
May +3.7%
Apr +4.0%
Mar +4.2% YoY
#oott Thx @business
Negative China economy indicator: Chinese consumers still aren't spending much.
Weak China consumer retail sales in Oct at +0.4% YoY (est +0.8%), which follows Sept +1.1% YoY, Aug at +0.4% YoY, July at +0.6% YoY, June at +1.0% YoY, the brutal May at -0.6% YoY and Apr at +0.2% YoY.
China consumer slowdown began to fall off in the aftermath of Trump Apr 2025 Liberation Day.
Oct +0.4% YoY, Est +0.8%
Sept +1.1%
Aug +0.4%
July +0.6%
June +1.0%
May -0.6%
Apr +0.2%
Mar +1.7%
Jan/Feb no available data
2025
Dec +0.9%
Nov +1.3%
Oct +2.9%
Sep +3.0%
Aug +3.4%
Jul +3.7%
Jun +4.8%
May +6.4%
Apr +5.1%
Mar +5.9%
No Jan/Feb data
2024
Dec +3.7%
Nov +3.0%
Oct +4.8%
Sep +3.2%
Aug +2.1%
July +2.7%
Jun +2.0%
May +3.7%
Apr +2.3%
Mar +3.1%
No Jan/Feb data
2023
Dec +7.4%
Nov +10.1%
Nowhere near pre-Covid steady +8-11%.
#oott Thx @business.
Trump, Xi, Putin to meet on Thurs Nov 19 in Shenzhen.
China state media
#oott

Dan Tsubouchi retweeted
High jet fuel prices + lessening oil hedge position = European airlines cutting capacity = less air travel than previously expected.
The reduced Europe air travel is due to European airlines taking out capacity right now. There will still be peak Xmas air travel but at lower levels than had been expected.
See my 👇11/08 post. @Ryanair CEO O'Leary on the earnings call warned that all European airlines were cutting capacity on their winter schedules.
Eurocontrol 7-day moving average of arrivals/departures turned negative YoY last week and continue negative YoY after 24 consecutive weeks of positive YoY from 05/21 thru 10/29.
Vs 2025, turned negative last week.
11/12: -2.1% YoY
11/05: -0.2%
10/29: +1.1%
10/22: +0.9%
10/15: +0.6%
10/08: +0.7%
10/01: +2.7%
09/24: +2.9%
09/17: +2.9%
09/03: +3.0%
08/27: +2.4%
07/30: +2.9%
07/23: +2.8%
07/16: +1.9%
07/09: +2.2%
07/02: +3.2%
06/25: +2.2%
05/28: +2.1%
04/30: -0.5%
03/26: +2.3%
03/19: +1.0%
03/12: -1.0%
03/05: -1.3%
02/26: +3.1%
Vs pre-Covid, Europe air travel (arrivals/departures) continues back above pre-Covid.
11/12: -1.1% vs pre-Covid
11/05: +2.5%
10/29: +4.9%
10/22: +3.9%
10/15: +4.1%
10/08: +4.0%
10/01: +4.6%
09/24: +3.2%
08/27: +3.2%
08/20: +3.3%
08/13: +4.9%
08/06: +5.1%
07/30: +4.3%
07/23: +4.1%
07/16: +2.5%
07/09: +2.7%
07/02: +1.0%
06/25; +0.6%
05/28: +3.8%
04/30: +0.5%
03/26: -0.7%
03/19: -2.6%.
03/12: -3.1%.
03/05: -3.5%.
02/26: -1.4%
Thx @eurocontrol
#oott

High jet fuel prices + lessening oil hedge position = European airlines cutting capacity = less air travel than previously expected.
The reduced Europe air travel is due to European airlines taking out capacity right now. There will still be peak Xmas air travel but at lower levels.
@Ryanair CEO O'Leary on the earnings call "Certainly, if you look at the way the European airlines are managing this winter schedule, they all, including us, originally filed our winter schedules. We have since cut back that winter schedule in taking traffic down from 216 million to 214 million. Honestly, every other airline in Europe has followed us. They are all taking out capacity. I think not many of them are as well hedged as we are. Most of the European airlines are hedged up to the end of October, at the end of December. I think it is dawning on them that they are going to have to pay significantly higher prices for unhedged oil, and they are cutting capacity accordingly."
#oott
Ukraine his major petrochemical plant and an oil refinery in central Russia city of Nizhnekamsk.
Thx @AlArabiya_Eng
#oott


Dan Tsubouchi retweeted
Vortexa's 1st estimates of crude oil floating storage for 11/13 as posted early this morning.
Note I didn't look at Vortexa last weekend so don't know how the initial 11/06 estimates were revised this week.
Total -2.88 mmb WoW to 85.50 mmb on 11/13. Floating storage was over 100 mmb consistently thru Aug, the last five weeks have been around or below 90 mmb.
Middle East -1.08 mmb WoW to 20.39 mmb on 11/130. With the continued US/Iran standoff and tankers moving out to some degree via going dark and US escorts, Middle East has been <25 mmb for the last five weeks.
Asia -3.05 mmb WoW to 21.02 .44 mmb WoW to 18.56 mmb on 10/30. Asia hit 66.62 mmb on 07/31, dropped quickly thereafter. The last 11 wks have been below 25 mmb incl 2wks below 20 mmb, which is by far the lowest levels since US attacked Iran.
Note the Sat am estimates are Vortexa's initial estimates at the Fri floating storage and get revised either up or down over the weekend and thru the week.
Thx @vortexa
@business
safgroup.ca #oott

