

Exxi retweeted

White paper is live.
shitcapital.com/whitepaper
There is no token live yet. There will be no surprise launch.

Exxi retweeted

Missed this from Metric last week.
Pretty based, especially because it doesn't necessarily help them.
They show real pool APR, the way pro MMs measure it after arb bots, toxic flow etc.
They built a tool that might make their own pools look bad but is good for us.

Most APR in DeFi counts the fees LPs earn. None of them count what LPs lose when the price moves against them. Metric now does.
Those losses come after the trade, from LVR, impermanent loss and informed traders picking off stale quotes. Market makers measure them on every fill. Most retail LPs find out the hard way, after a “50% APR” pool slowly loses them money.
APR has historically lacked transparency. It shows what a pool earned and leaves out what it gave back, so LPs can’t tell which pools actually work. We built APR Markouts to change that.
After every fill, Markout asks one question. Once the market catches up, did the pool make money on this trade?
Say a pool buys 1 ETH at $2,990 while the reference price is $3,000. Five minutes later ETH is at $3,004, so the pool kept $14. If ETH had dropped to $2,970, it would have lost $20.
Every Metric pool now shows Markout APR, net of fees, the number LPs can trust more. You can view it 1, 5 or 30 minutes after each fill, over 24 hours, 7 days, 30 days or all time. It’s the number a market maker would use to judge a pool, and yes, it can be negative. LPs should always see what they’re getting into.
A pool with a lot of volume isn’t always making its LPs money. Now you can see the difference pool by pool and bin by bin, along with your own share in your positions.
Market makers have always judged pools this way. Now every LP on Metric gets the same transparency.
Live now on Metric.

Exxi retweeted

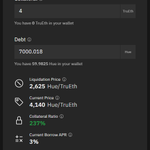
DAI added USDC as collateral so it could increase the supply beyond the user base looking to borrow against their ETH
@SamExotic3 gave details below on what challenges Liquity face
At @polarisfnd we have adopted a different approach
- our own purpose built collateral asset pETH that closely tracks the ETH price while having an important scaling property
- an ETH PSM (not USDC PSM like
DAI introduced) that allows the stablecoin supply to expand/contract 1:1 by arbitragers rather than minters directly
- completely market dependant interest rate that also enables negative effective interest rates. This is important across market conditions
- yield source not driven by minters of the assets alone, connecting ETH yield seekers to stablecoin minters
- many more innovations I won’t list here vs Liquity, Maker and others
Our whole goal at Polaris is to black hole as much ETH as possible into pETH and build a yield bearing, decentralized synthetic asset economy on top of this


Exxi retweeted

hey @bubblemaps
do you remember how you came to exist?
in 2024, I remember when no1 had ever heard of bubblemaps.
@the__solstice shilled 4 coins to over $50m+ at the time: $Neiro, $Ginnan, $Snibbu, and $Mumu
Several of them went to $100m after.
@bubblemaps actually owes your entire business to this man for putting you on the map so you could rug solana:FQgtfugBdpFN7PZ6NdPrZpVLDBrPGxXesi4gVu3vErhY.
would be the 3rd time m claims against @the__solstice and your first two articles were about him.
Coming back in the Big 26 to make the same playbook, hats off fellas. You’re so cool.

1/ An investigation into @The__Solstice, top #3 social trader, and his ties to a massive bundling operation


Comment section an actual goldmine for RH. So many of the most prominent voices chiming in and yet, not a single response to any of them.

hey there, fern here. Normally I just post food pics but today I woke up and wanted to check in and get some feedback as we near 100 days of Robinhood Chain being live.
in addition to my unpaid role as an unofficial pizza influencer, my day job is leading our onchain and DeFi products at @RobinhoodCrypto
listening to the people is key, so I want to know:
what can we do to make the onchain ecosystem work better for you? What do you like? Hate? Anything we’re missing?
what do you want to see from our next 100 days that you havne't seen so far?
and for good measure, here's my pizza from last night to stay on brand.
thanks to everyone supporting what we're doing. It's been an exciting ride so far.

35
Where does $zevio @zeviodotsh get their inference? Openrouter, Orbio, their personal accounts at openai and anthropic?
1
1
1,563
Exxi retweeted

Introducing @papertrade_xyz - a fair-launched, fully-onchain perpetuals exchange built on Hyperliquid by @izebel_eth & @blurr
-1000x leverage
-0 slippage
-No funding costs
-Self-bootstrapping LP
Coming soon. Learn more at: docs.papertrade.xyz

Exxi retweeted

Learn more about PaperDAO here: paperdao.xyz
Learn more about Papertrade here: papertrade.xyz
Follow Papertrade team: teapawt.org/izebel_eth and teapawt.org/blurr
Follow DaosWorld: teapawt.org/daosdotworld

marked safe from converting my deposits 😂 shit was gone in under 20 seconds
This Post is from a suspended account. Learn more
20


Exxi retweeted

A lot of people are saying PONS is the flippers launchpad.
What if the data shows that even flippers lose more often on PONS than on LONG.
You are nearly 2x more likely to win flipping on LONG than on the supposed "flippers launchpad".
More than 1/3 of all positions that were closed within an hour on LONG were positive. On PONS only 1/5 of these made any profit.
The data also reveals the obvious. Holders on LONG are almost 3x more likely to make money than on PONS.
The chances of making money are much worse on PONS in any case.
LONG introduces a new mechanism that incentivizes holders. PONS just build another Pumpfun on Robinhood.


This was fun! Should've read all the answers before choosing one on the 1/14, derp. Well written and easy to read whitepaper @standard_rsv


if you read the Standard Reserve whitepaper, take this exam to prove you did
> 14 questions
> 20s each
score at least 8/14 and you’re officially qualified to be a @standard_rsv banker
standardexam.vercel.app


2
51
Exxi retweeted

important note(and a personal tip)
How we align in with one key idea: largest trad fi players (e.g Robinhood), crypto and retail traders?
We will start seeing LONG pools becoming a deflationary force on stocks(never done before) this is the greatest super power of major like ETH, unlocking this power for stocks will be one of the biggest paradigm shifts in history of finance.
I built my entire career in crypto pitching different models and ideas to non natives (always focused on net new audience + flows) I understand the nuance of how explain crypto without making it sounds like a scam or borderline illegal.
I know it's tempting to think about how LONG markets can potentially "run" the stock but I want to provide a better framing.
Trad Fi stock markets are extremely efficient every drop of order flow is being predicated ahead of time and the large players will simply run models to arb it and preserve price stability above all. They can do the exact same thing with crypto stock pools, But they won't be able to do it over long term horizon once locked stock in LP is large enough.
what they don't yet account for is stock token flows + deep liquidity. The LONG approach is not just a massive 0-1 moment for crypto but it's a 0-1 moment for stock markets as well.
This is who we're going against. And I'm trying to run a very LONG term play here where we increase the liquidity network effects to the point the system as a whole becoming anti fragile. Instead of going into a fight against citadel and Jane street or large cap stocks I want to make it their *interest* to support our market activity.
Our top $NVDA pair had more than $500k worth of stock locked in LP as we grow it at some point we are not just "squeezing" the stocks we create a new asset class that is correlated with the stock but provides better store of value.
The comparative for stock pairs is buying the stock directly, what we are trying to to do with LONG is making assets so deep in liquidity that allocating for them is like buying a stock of Berkshire Hathaway that is famesoly known to hold major stocks for many years, this is simply how LP works in crypto. But it's even better because the LONG assets are not owned by a single entity that cna just exit and sell all stock it's a more high level and complex social belief system.
LONG.

Exxi retweeted

Whats the hype around TEEs? Every serious cryptographer i talk with have some passionate hate for them + they are breakable on the hardware level
Yet we pretend them somehow bring full privacy, for inference demand (openrouter) is also quite low for ‘private’ inference
Privacy is something binary, either you have it or you dont imo


Exxi retweeted

(I recommend reading this for anyone currently invested in the market or interested in learning what's going on)
🦔$2.6 trillion in S&P 500 call options traded in a single session yesterday, the highest single-day notional volume in the history of the index. The chart above shows what that growth curve actually looks like, with daily call volume sitting under $200 billion as recently as 2019 and now running at multiples of that on a regular basis. The combination of zero-day-to-expiration options, retail platforms that gamified options trading, and algorithmic market makers running delta-neutral books has turned the largest equity index in the world into something closer to a leveraged casino than a price discovery mechanism.
My Take
I want to walk through what is actually happening here because most retail traders chasing these calls do not understand the machinery on the other side of their trades. When you buy a call option, a market maker like Citadel or Jane Street sells it to you and then buys the underlying stock to hedge their exposure. As the stock price rises, they buy more shares to stay neutral, which pushes the price higher, which pulls in more retail call buyers, which forces more hedging. This is called a gamma squeeze, and it works in both directions. The same mechanic that drives prices up violently can pull them down even faster when the flow reverses, which is why these moves tend to end in sharp drawdowns rather than gentle corrections.
The piece that worries me as someone who covers this stuff is how much of this volume is concentrated in zero-day options that expire the same session. A retail trader buying a $5 call that expires at 4 PM is taking a position with leverage that would have required a margin account and a series-7 license twenty years ago, and the platforms now make it as easy as ordering takeout. Market makers love this volume because they make money on the spread regardless of direction, but the buyers on the other side are absorbing all the risk in a structure designed to extract pennies from them at scale. If you take nothing else from this post, understand that $2.6 trillion in daily call volume is not a sign the market is healthy, it is a sign that speculation has overwhelmed investment, and historically that pattern resolves in ways that hurt the people who came late to it. I am not telling anyone what to do with their money, but knowing how the machinery works is how you avoid being the exit liquidity for someone else's algorithm.
Hedgie🤗

