





Pinned Tweet
Returns of 19 quarters of small cap investing:
26YTD: 10%
2025 : 123%
2024 : 27%
2023 : 42%
2022 : 66%
A fall from grace as I reported a first negative quarter in my latest post... 🟥🫠


Found a company growing 38% at 9x earnings...
Dug a bit deeper, what do they do...
They lend up 180%(!!) of the value of your car, with a maximum of $150k....
I think they'll actually do well, but man everything goes these days.
If you can't afford a big car, just buy a small one, get a 180% loan and then buy the big one anyway, and get another 180% loan.
By the way max 130% if the car is >10yo.


If we (you and I) started a taxi business tomorrow and bought a car for 25k, we would not feel very levered when taking half or 3/4 of the money through a financial renting or leasing contract with a bank
The bank would ask final claim on the car, in exchange for a low borrow rate.
We would write off the car as fast as we can, to make paper tax losses or at least offset profits and keep more of our operating profits
Our reported profits would look lower than our cash generation and our equity would look lower than our true economic value.
This is what's happening at Alquiber, and that's why I don't see it as a highly levered company.
Theoretically, one could even argue it's a net-net, because it has liquid assets which it could sell in a couple of months, for more than its debt and market cap. 🤔
Alquiber posted earnings this week. The market did not really care about another double digit growth H1, with 25% profit growth. The company has sleepy long term investors
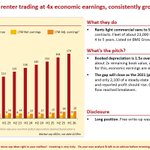
The company looks cheap at 9x reported earnings, but in my modelling in fact trades at 4x earnings. I have written a very free and somewhat boring accounting-nerd article about this about 6 months ago.
Alquiber sold about 8% of their vehicles in the last 12 months, for a gain of about 100% each, representing their full net income.
But... They sell the cars after 4-5 years. In equilibrium state, they will sell about 20% of their car population each year.
The effect of this when it happens, is that reported net income will be 2-3x higher. This would have been 20m for the past 12 months if they did not write down the cars so aggressively.
I think high disposals are coming in the next 1-2 years, as the big post-covid 2021 purchased vans will be sold and their gain will become visible
Meanwhile, I'm happy to hold the shares, see the fleet expand every year and see reported profits edge to an all time high, offsetting the 2023 peaks driven by high 2nd hand car prices, with consistent organic core business growth
I checked for comparable businesses today with high growth, rotating assets, depreciation > earnings, large gain on disposal, but couldn't find any like Alquiber.
The closest was Autohellas but their demand I think is less recurring and profits are less hidden
Discl: Long, dyodd
Deleted the Q2 post a while ago because it could be seen as "fund promotion" and decided to not do a fund as it's much more fun to do a newsletter instead.

Why is consensus not thinking we are close to an improvement with Iran-USA ?
- US is retreating from Iraq
- KSA reportedly is still able to export its oil, partly on land, partly through SOH, weakening Irans position
- Iran asking for peace talks and willing to have them in enemy territory
- Mid terms coming
A deal seems imminent, even though it might not be sustainable long term
Joël Schols of Chess capital delivered a great lecture on net-net investing today, to a very sober community of Belgian value investors #vfb 🍻
@SamHollanders @elvermo


