

Global markets for the smart money.
Joined March 2009
- Tweets43.2K
- Following45
- Followers229K
- Likes276




🏛️ It's central bank week!
Five major policy decisions on the Calendar. No shortage of opinions.
What are you watching most closely?
56%Rate decisions
13%Forward guidance
12%Inflation outlooks
19%Market reactions
52 votes • 1 days🇳🇿 New Zealand banks will be closed Monday, Oct 26, for Labor Day.
Any impact should be modest and mostly limited to thinner NZD liquidity as the trading week gets underway.
⏰ Clocks move back one hour in Switzerland, the eurozone, and the UK on Sunday, Oct 25.
The US follows on Nov 1. For one week, London and New York will be four hours apart instead of five.
Same sessions. Different time gap. Check your trading schedule!
Iran headlines had cooled heading into the US election. So had the comments.
Then came reports of plans to move US embassy staff and families out of the Gulf: 272 comments, this week’s most-discussed story.
More smoke, or is the lull about to end?
forexfactory.com/news/143284…

🇺🇸 60 minutes until Revised UoM Consumer Sentiment.
One more check on consumers' mood, with sentiment near a record low and inflation still on their minds.

🇺🇸 The Revised University of Michigan Consumer Sentiment survey is out soon, expected to hold at 46.3.
The preliminary reading was just 1.5 points above May's all-time low, while year-ahead inflation expectations rose to 4.7%.
A brighter outlook would be a change of pace.

Low firing has been one piece of the US jobs picture. Unemployment claims are due soon, with five straight readings below 200k. The forecast this time is... 200k
UK Retail Sales are due Friday morning in London, with -0.1% m/m forecasted.
Once a high impact release, retail sales have taken a back seat to inflation and wages for now.
Will this release matter for GBP traders? It may take a large surprise to draw significant attention.

🇯🇵 Japan National Core CPI is coming up in Friday’s Tokyo session, with consensus at 2.1% y/y vs. the previous 1.7%.
The forecast implies a return above 2% for the first time since January’s release. With the BoJ increasingly focused on preventing an inflation overshoot, will this release strengthen the case for a faster rate-hiking cycle?

⏳NZ CPI is coming up.
👀 Rate expectations and the kiwi are in focus.
🇺🇸 US Initial Unemployment Claims came in below 200k for five straight releases, but that strength hasn't translated into similarly strong NFP figures.
Claims remain closely watched, but how well do low layoffs reflect the broader jobs picture in this environment?

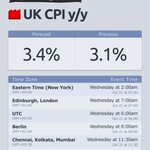
🇬🇧 UK CPI is coming up, with 3.4% y/y forecast.
Yesterday's jobs data reinforced expectations for a BoE hike. Will inflation further strengthen the case?
Follow the data:
forexfactory.com/?utm_source…

🇳🇿 NZ CPI is forecast to rise 0.8% q/q.
With the RBNZ deciding rates just six days later, a hike is the base case, but not fully priced in. An inflation surprise could shift rate expectations and trigger a sharp move in the kiwi.
CPI should move those odds, but which way?
🇬🇧 Did you know UK inflation above 3% requires the BoE Governor to explain the overshoot in an open letter to the Chancellor?
The 3.1% reading released last month prompted a letter from Bailey.
UK CPI is due Wednesday, with 3.4% y/y forecast. Will it surprise on the downside?
🇬🇧 Last month's UK 10-y gilt auction produced a 5.38% yield, the highest since 1999. With global pressure pushing longer-dated yields higher, this next auction will test demand.
For GBP, higher yields may offer little support if they reflect greater concern over UK debt.
🇨🇦Canada inflation data is up next!
Follow the release and market reaction on Forex Factory: forexfactory.com/?utm_source…


🇬🇧Could UK wage growth shake up November BoE rate expectations?
With labor data due soon, the Average Earnings Index is in focus.
Earnings have missed forecasts just once in seven releases, while markets price in a 75% chance of a November rate hike.
Will softer wages change the outlook?
