

Strategic Transaction Advisory. $200MM + in Value Add For Our Clients. https://teapawt.org/t.co/kAFPNqYaaE
USA
Joined June 2024
- Tweets61
- Following13
- Followers66
- Likes126



7Alder retweeted
Semiconductor Series, Part II : Foundries
Refer back to Part I: Raw Materials and Wafer Fabrication Equipment (WFE) for a quick refresher on the players at the very beginning of the semiconductor food chain. Part II of the semiconductor series is going to be about the companies and the factories that make them.
In the olden days, those who designed the chips were also the ones who made them: the fabled IDM model. Since then, industry titans like AMD have either sold or spun-off their foundries, and other players like Texas Instruments and NXP have elected to go with “fab-lite” models. The foundry and chip designer spectrum is largely divided into 3 sections: pure-play foundry, fab-lite, and fabless. Some quick housekeeping, the word foundry and fab-short for fabrication plant- are largely interchangeable, and the word IDM stands for Integrated Device Manufacturer, meaning a company that designs and fabs their own chips.
Starting from the left hand-side with pure-play foundry companies, Taiwan Semiconductor Manufacturing Company (TMSC) is the objective leader of the pack. 90% of the world’s advanced chips come out of TSMC. The chips that go into phones, laptops, VR headsets, datacenters, supercomputers etc. are likely made in a TSMC fab. These fabs are composed of the latest and greatest wafer fabrication equipment (WFE) made by the big 5: Applied Materials, ASML, KLA-Tencor, Lam Research and Tokyo Electron. The job of the foundry, TSMC, is to combine that magical WFE into a functioning assembly line that can churn out the latest chips.
This is an extremely challenging process that even the equipment suppliers themselves do not know how to handle. The foundry is like the structural engineer of a 100+ story skyscraper and the conductor of a 1000 piece orchestra. It must find out how to architect transistors and interconnects such that speed, efficiency, and thermals are optimized, while also tuning every piece of equipment precisely so it operates within a tolerance measured by nanometers.
This is why the job of the foundry is so vital to both its customers, and the nations upon which its facilities lie upon. There are currently only 3 countries with foundries considered bleeding-edge operated by domestic players: Taiwan, Korea, and the United States. Taiwan has TSMC, Korea has Samsung, and America has Intel. These 3 companies all have the capability to manufacture what would be considered the most advanced chips.
Each generation, or “node,” is marked with a name defined in nanometers. The latest node to enter mass production has been the 3nm node. 3nm doesn’t actually mean each transistor is 3nm large, it is just the name of a single generation of node. Similar to how the iPhone goes from iPhone 14 to 15, nodes will jump from 5nm to 3nm and aren’t an indication of transistor size.
Aside from the big 3 foundries TSMC, Samsung, and Intel, the manufacturing capability of competitors drops drastically. The 4th most competitive foundry is China’s SMIC, Semiconductor Manufacturing International Corporation, which is technologically years behind the frontier. To put it into perspective, SMIC’s 7nm generation node is their latest actual node to enter mass production. Meanwhile, TSMC’s 7nm node entered mass production nearly 6 years earlier. To quantify that in terms of performance, we can compare the performance of smartphone chips. Apple’s most recent iPhone chip on TSMC’s 3nm process is >2x as fast as their last iPhone chip on 7nm.
Smartphone CPU performance is likely to be a more accurate representation of performance improvements solely attributable to process node improvements, as smartphone chip design is in a far more mature state than GPU design-where architectural and algorithmic improvements are increasing performance 2x every few months. That being said, using the smartphone chip benchmark, a given chip based on TSMC 3nm is likely to be either twice as fast, or twice as power efficient as a given chip produced from the latest SMIC fab.
At a datacenter level, TSMC process node customers can build out twice the compute capability for the same price, power envelope, and real estate footprint. This advantage is absolutely crucial in a time where the artificial intelligence industry is being driven by logarithmic scaling laws, and where the size of datacenters is being capped by local power draw limitations.
This means that you must increase compute resources exponentially for linear increases in model performance, but you only have a finite allotment of power your datacenter can draw. In the age of AI, power efficiency doesn’t just matter from a TCO point of view, but it is now the main driving force behind how much compute we can throw into training a model. These power limitations imposed by the local utility are the reason why big tech companies have opted to go the private route and invest in or partner with small modular nuclear reactor companies-another topic we have covered in the past!
Shifting back to foundry, it is evident that there is a large difference between a great foundry and a good one. Major supply chains like that of the iPhone or a Hopper GPU are entirely reliant on fabs in Taiwan for manufacturing their chips. Being a country with cutting edge fabs on your territory is crucial from a national security perspective because it insulates your domestic innovation from global conflicts. If Taiwan’s facilities are compromised by an earthquake or a military operation, US chip designers like Nvidia can still turn to TSMC’s USA facilities, or even Intel to continue to pump out competitive chips.
Moving onto fab-lite, there are companies like Texas Instruments (now less so), NXP Semi, and Infineon that employ this business model. Keeping on the bleeding edge of semiconductor fabrication is challenging from both a human and financial capital lens.
Developing the next generation of process node is getting increasingly expensive as TSMC’s 5nm node cost twice as much to develop as their 7nm node did. Without mentioning R&D, the CapEx bill can get into the $20-30 billion mark for just one facility. This is why, for companies whose core business does not revolve around cutting edge nodes, it makes sense to go fab-lite. These companies can still be considered IDMs because they still design and manufacture some of their own chips to an extent. But, any chip they sell that is designed on an advanced node will be manufactured by a third party like TSMC.
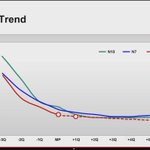
The fundamental reason this operating model works is due to how process nodes age. The bulk of Texas Instruments’ products are manufactured on process nodes in the 45nm-130nm node, process nodes that initially entered mass production 2 decades ago. Even though the next generations of process nodes are getting more expensive to develop, those same process nodes will eventually drop in price and will be able to be made more economically. Over time, fabs can always figure out how to decrease the defect density on a wafer. Here is how it generally trends overtime:
As you can see, fabs consistently improve at mitigating manufacturing defects, which increases yield per wafer, and improves the cost basis. Not only this, but WFE based on previous gen technology is far cheaper to buy off equipment suppliers than when they were cutting edge. This means that for a given node, the cost for building a fab, and subsequently producing that node gets cheaper with time.
A great example of the fab-lite business model is with Texas Instruments’ purchase of Micron’s Lehi Fab, which produces 65nm and 45nm chips. They bought the fab for just $900 million in 2021, while it likely cost roughly ~$4 billion to build. This $4 billion figure comes from the plant’s initial $2.5 billion construction, plus an additional $1.5 billion investment in the early 2010s. This is why IDMs whose products do not need to be manufactured on the latest process node prefer the fab-lite model. With fab-lite companies, it’s not mission critical to be on the latest node.
They can save themselves the capex and outsource to TSMC while they wait for the technology to inevitably become cheap enough to invest in.
This fab-lite model is the strategy that Texas Instruments, NXP Semi, Infineon, STMicro, and many others have committed to. Their products are not in the latest smartphones or the newest Nvidia GPUs, but instead inside your cars, scooters, internet routers, refrigerators, laundry machines, and electrical equipment. These applications don’t need the most power efficient or speedy chip on the market! When was the last time you felt the user interface on your microwave wasn’t snappy enough?
Truth be told, Texas Instruments has generally pivoted away from the fab-lite strategy, but at some point the company was outsourcing production of some 40-50% of chips. There are likely several factors that the management at Texas Instruments has taken into consideration when moving away from fab-lite back to true IDM.
The main reason likely stems from geopolitics and its effect on the semiconductor supply chain. If Texas Instruments fully relied on a foundry like TSMC or UMC, and say Taiwan were to be compromised, then Texas Instruments would likely go down with it.
The US government understands this issue and is certainly front of mind for many in congress which is why they’ve passed a massive subsidy package for domestic semiconductor manufacturing with the US CHIPS act in 2022.
Texas Instruments has already received $1.6 billion in direct funding from the CHIPS Act. The derisking from Taiwan in addition to the government support for domestic fabs are likely two factors influencing the higher ups at Texas Instruments to invest heavily in reshoring semiconductor manufacturing back onto US soil. They actually recently announced an $11 billion upgrade to the Lehi fab they bought from Micron, and have committed another $30 billion to spring up 4 new fabs in Sherman, TX.
So much for fab-lite!


7Alder retweeted
AI in the Healthcare Market
AI is transforming the healthcare industry, offering unprecedented opportunities for innovation in patient care, diagnostics, drug discovery, and operational efficiency in hospital management. As investors navigate this rapidly evolving landscape, understanding key developments, regulatory challenges, and strategic partnerships is essential for making decisions that put them ahead of the market.
One of the primary drivers of AI adoption in healthcare is the formation of strategic partnerships between leading technology companies and healthcare organizations. These collaborations allow healthcare providers to utilize advanced AI infrastructure and accelerate innovation with the potential of creating $150 billion in annual savings for the US healthcare industry by 2026.
NVIDIA, for example, has recently established several collaborations to advance healthcare applications that they discussed at the January 2025 J.P. Morgan Healthcare Conference. One partner is the Arc Institute, a California-based research organization, to develop models that expedite drug discovery, synthetic biology, and disease research. The Arc Institute’s efforts, coupled with NVIDIA’s AI infrastructure, aim to scale the potential of these models to address complex biological challenges across multiple modalities including DNA, RNA, and proteins.
In addition to the Arc Institute, IQVIA, a Fortune 500 healthcare company, is utilizing NVIDIA AI Foundry services to create custom foundation models that accelerate research and clinical development. Similarly, Illumina, a leader in DNA sequencing and informatics technology, is employing NVIDIA’s AI toolsets for analysis of multiomics (i.e. combining genomics, transcriptomics, proteomics, and metabolomics). The Mayo Clinic is set to employ NVIDIA’s advanced DGX Blackwell systems to handle large-scale digital pathology datasets and MONAI platform to perform healthcare imaging.
To keep pace with NVIDIA, other key players in the healthcare industry are forming strategic alliances to drive innovation in the AI subsector. Fortune 500 healthcare company GE healthcare and Sutter Health, a not-for-profit healthcare provider with over 3.5 million patients, have entered a $1 billion partnership called the Care Alliance to integrate AI-powered imaging technologies across PET/CT, SPECT/CT, MRI, and ultrasound. These advancements aim to accelerate appointment scheduling, faster and more accurate diagnostic imaging scans, early diagnoses, greater convenience, and more consistent care.
Following the trend of using a software conglomerate’s AI infrastructure to make healthcare advancements, venture capital firm General Catalyst partnered with Amazon Web Services (AWS) to build solutions that enhance medical imaging and automate provider workflows. This collaboration leverages AWS’s extensive cloud computing capabilities and General Catalyst’s expertise, having closed over 60 digital health deals since 2020. The multiyear initiative will initially support Aidoc and Commure, two of General Catalyst’s AI-driven portfolio companies, in addressing healthcare challenges like staff burnout, labor shortages, and thin margins.
Aside from these partnerships between technology and healthcare companies, independent researchers are using AI to make technological breakthroughs that are redefining the boundaries of medical research and practice. FastGlioma, an AI-based diagnostic system that operates during surgery to detect if any part of a cancerous brain tumor that can be removed still remains in the patient. This technology can perform detections in 10 seconds, outperforming conventional methods in speed and accuracy.
According to Dr. Todd Hollon, a neurosurgeon at University of Michigan Health and assistant professor of neurosurgery at University of Michigan Medical School, FastGlioma has the potential to transform neurosurgery by improving the management of patients with diffuse gliomas. The system addresses a critical challenge in surgery: differentiating between healthy brain tissue and residual tumor. The technology thereby reduces the likelihood of tumor recurrence.
New AI technologies have resulted in increased governmental regulations playing a pivotal role in shaping private investment in healthcare. Massachusetts House Bill 5159, signed into law in January 2025, expands oversight of private equity investments in healthcare by requiring detailed financial disclosures, stricter licensing requirements, and extended review timelines for mergers and acquisitions. The law broadens the scope of transactions subject to regulatory scrutiny, particularly those involving significant equity investors and private equity firms with at least 10% ownership in provider organizations. These measures reflect growing concerns over market consolidation, cost inflation, and the quality of patient care under investor-driven healthcare models.
For investors, these regulations introduce new hurdles in deal structuring because of due diligence and compliance. Beyond longer review periods, investors must navigate stricter financial reporting, heightened regulatory scrutiny of ownership stakes, and increased compliance costs. As a result, private equity firms may need to adjust transaction structures, reconsider valuation models, and explore alternative investment strategies to mitigate regulatory hurdles. Heightened liability under Massachusetts’ expanded False Claims Act means investors must be more vigilant in monitoring portfolio companies for regulatory compliance. While leading white-shoe law firm Kirkland & Ellis says that investors do not need to take immediate action at this time, they recommend that investors consider engaging with legal counsel and regulatory experts given that at least 15 states have introduced similar laws.
Overall, AI in healthcare is expected to grow at a CAGR of 38.1% through 2031 for a market value of $287 billion. This growth is fueled by increasing demand for efficient healthcare solutions and rapid technological advancements. Several key trends are driving this evolution from diagnostics to drug discovery, offering multiple revenue streams for companies that diversify product and service portfolios. Diversification is key in this rapidly evolving sector, so investing across different segments (such as diagnostics, imaging, and workflow automation) can help mitigate risks while maximizing opportunities. Identifying emerging technologies, like FastGlioma, can provide early exposure to transformative advancements that address unmet healthcare needs.
Additionally, successful integration with existing healthcare infrastructure is emerging as a key competitive advantage. Firms that build strong partnerships with healthcare providers and technology companies are better positioned in the market. As regulatory scrutiny increases, ethical AI practices will also become a critical differentiator for investors. Companies that prioritize transparency, data security, and patient safety are more likely to attract investment and comply with evolving legal requirements.
AI is driving innovation in healthcare, creating new opportunities for investment. With evolving regulations, strategic partnerships, and technological advancements, the sector is set for significant growth. Investors who stay informed and align with market trends and ethical considerations can effectively capitalize on this transformation.

7Alder retweeted
The Spindrift Acquisition: Did Gryphon Catch Lightning in a Bottle?
In December 2024, Spindrift Beverage entered into discussions to be acquired by the San Francisco-based private equity firm Gryphon Investors for a sum of $650 million at a ~26x EV/EBITDA multiple.
This prospective deal captured significant attention within the beverage industry, reflecting broader trends in which both established corporations and investment firms seek to capitalize on rising consumer interest in better-for-you drink options. The Spindrift–Gryphon deal stands out for its convergence of brand authenticity, strong financial performance, and a market environment increasingly favorable to transparent, minimally processed beverages.
Spindrift was founded in 2010 by Bill Creelman, who set out to create sparkling waters using only real squeezed fruit for flavoring—a distinct departure from the “natural flavors” commonly used by competitors like hint and la croix. By eliminating artificial or laboratory-derived additives, people say Spindrift’s beverages taste refreshingly tart, creating a perception of authenticity that resonates with consumers looking to reduce their consumption of artificially sweetened drinks.
This straightforward brand identity, rooted in transparency and simplicity, set the company apart in a seemingly crowded lightly flavored beverage marketplace. Over the years, Spindrift’s approach won over health-conscious shoppers who wanted beverages with short ingredient lists, helping the brand gain a loyal following willing to pay a premium for a product they perceived as superior in taste and health.
Since 2021, the company has been trying to carve out a name for itself in the hard seltzers category, leveraging its health-driven approach to establish a unique point of difference in a fast-growing alcoholic beverage segment. The company is literally trying to turn water into wine.
More recently, the company has tried capitalizing on the no-alcohol movement by releasing new drinks like the “Cosnopolitan” and “Nojito”. The sobriety market is fast growing, with the IWSR (International Wine and Spirits Record) estimating that the no-alcohol segment had a 29% uptick in global volume in 2023. Spindrift now operates in the sparkling water, hard seltzer, and cocktail market. Here is how Spindrift as a whole portrays itself on its website.
Financially, Spindrift demonstrated a strong upward trajectory, reporting 2024 annual EBITDA of about $25 million on $260 million in revenue. This figure, alongside double-digit growth in revenue and distribution, was evidence of the company’s ability to compete profitably in the premium sparkling water category.
Moreover, Spindrift’s success occurred against the backdrop of a global bottled water market projected to exceed $550 billion in sales by 2033, supported by an estimated 5.3% CAGR. In a world where “better-for-you” drinks are rapidly becoming the drink of choice for many consumers, Spindrift’s brand reputation and demonstrated profitability were the two pillars that made it an attractive acquisition target for Gryphon.
Gryphon has previous experience in the food & beverage industry, formerly owning brands like Eight O’Clock Coffee and Dessert Holdings. As for the Eight O’Clock Coffee deal, they bought the company in 2004 for $100 million, and then sold the company two years later for more than double that in a $220 million deal with India’s Tata coffee.
Spindrift’s products elicit a rather extreme response from both sides of the spectrum. The ones who love Spindrift are willing to pay top dollar every time for their product, and the people that don’t particularly enjoy Spindrift usually have a visceral disdain for their product.
Take these 4 responses:
“Spindrift is life. Orange-Mango is my shit. Real juice. Unsweetened. I want to buy stock in Spindrift!” - lemon_whirl
“It's so good I want a lifetime supply. I discovered it last week and I'm in love.” - Newtbatallion
“Spindrift tastes like TV static. It's horrible and I have no idea why people like it. Also, the flavors are so muted.” - [deleted]
“I bought 4 cases today because they are BOGO. I just tried the peach strawberry and it is awful! It tastes like rotten fruit.” - Global_Sun_8106
In reality, at the scope Spindrift and Gryphon are operating at, it is perfectly acceptable for your product to only appeal to a select minority of the population. It’s not like either party is expecting the Spindrift brand to become a global phenomenon across all demographics and taste buds. As long as the brand has fans that are fanatics about their sparkling water, the company will continue to extract profits out of them.
The anecdotal reddit evidence shows that different flavored water brands have distinct enough tastes to evoke polarizing opinions. Sparkling water is a commoditized market, but spindrift appears successful in swimming upstream to be a unique player. There will always be concerns they fall back into the sea of other water brands, but within the confines of the commoditized sparkling water market, it’s clear that the brand’s innovation has enabled it to develop a real moat around its product.
Spindrift not being tailored to the general population’s taste buds makes customer acquisition rather expensive, yet this force is balanced out by the product’s stickiness and ability to generate customer loyalty. Even though it may be difficult to acquire new customers in this market, the lifetime value of each of those mouths is likely quite high.
In addition to the fan base, the company’s annual EBITDA suggested that it was on solid financial ground. Spindrift has already achieved a 9.6% EBITDA margin on its business, and is currently growing revenue at an estimated 35% YoY, which means this already profitable business will be even more lucrative for Gryphon as total sales tick up.
One more general note, this isn’t Gryphon’s first foray into the food & beverage industry, and its broader experience in food & beverage products could help Spindrift optimize its supply chain and scale its production more efficiently, thereby elevating margins and expanding the brand’s footprint.
The price tag exceeding $650 million and expensive EV/EBITDA multiple of ~26x underscores the high valuation that successful, mission-driven brands can command in today’s market. This multiple reflects Spindrift’s healthy growth and proven ability to attract health-focused consumers. In the consumer packaged goods sector, brands that differentiate themselves via authenticity, premium ingredients, and strong storytelling can command higher EBITDA multiples than more commoditized competitors. Gryphon’s willingness to pay a premium signals confidence in Spindrift’s long-term viability, as well as the potential for Gryphon-implemented efficiency changes.
The broader context of this acquisition sits within a wave of consolidation and investment reshaping the beverage industry as a whole. In 2024, Keurig Dr Pepper acquired energy-drink maker Ghost for over $1 billion, while Simply Good Foods purchased the protein shake brand Only What You Need (OWYN) for $280 million.
These high-profile deals highlight the intensity of market competition and the strategic pivot among major players to capture emerging categories such as low-sugar, natural, and functional beverages. The Spindrift–Gryphon deal, in that sense, exemplifies how private equity sees robust potential in health-oriented products that have already established themselves in the marketplace.
Beyond the immediate impact on Spindrift, this acquisition has potential ramifications for the sparkling water segment as a whole. Rival beverage brands might respond by innovating more quickly to preserve or grow their own market shares, particularly focusing on flavor variety and ingredient transparency. This shift is not just an empty threat, historical examples like coffee show that consumers don’t only want companies to compete on price, but also on innovation.
In the coffee industry, coffee enjoyers began with instant diner coffee back in the pre-starbucks era. Then, Starbucks and Peet’s burst onto the scene with deluxe beans that were gathered in specific countries. After that, third wave coffee shops like Philz and Blue bottle began offering even more sourcing transparency when it comes to beans, sometimes offering up specific farm names and flavor profile information.
This shift in consumer preferences for coffee is a perfect example of the beverage drinker paying more and more to be aware of what is going into their body. Perhaps Gryphon predicts this same trend will reach flavored sparkling water, and that early disrupters like Spindrift will finally cash in on their quality-over-quantity bet. With Spindrift’s $650 million-plus valuation setting a high benchmark, smaller players could see themselves targeted if they can demonstrate proven traction in health-forward or niche markets.
Concurrently, private label brands produced by large retailers might attempt to replicate Spindrift’s real-fruit approach at a lower price point, though replicating the authenticity and brand loyalty that Spindrift has built could prove challenging considering the incumbent’s established first mover and scale advantages.
The Spindrift acquisition by Gryphon Investors is an intricate bet on consumer tastes, brand positioning, and capital infusion in shaping the modern beverage landscape. The transaction rides the momentum behind the “better-for-you” drinks and the willingness of private equity to invest significant sums in categories showing strong consumer loyalty. While Spindrift’s leadership has successfully grown the brand over the years, Gryphon’s involvement could accelerate that process—so long as the delicate balance between operational efficiencies and brand authenticity is preserved. If Gryphon’s bet on natural and transparently sourced beverages is correct, the global beverage market will follow Spindrift’s lead, heralding a new era of choice for consumers who demand transparency in what they drink.


7Alder retweeted
Lesson from the Red Lobster Acquisition:
Red Lobster is one of the biggest household names to fall victim to the slash and burn ways of Private Equity. The once renowned casual seafood restaurant that invented popcorn shrimp, has now been passed around by multiple private equity funds who each hoped to be the one to restore its former glory. After a tumultuous decade and numerous management teams, things are looking bright for the restaurant chain.
Let's explore the rise, fall, and hopeful rise again of Red Lobster.
After the company was spun-off from general mills in 1995, it remained a part of the Darden Restaurant Group until its sale to Golden Gate Capital in 2014, who acquired the seafood chain for $2.1 Billion. Golden Gate Capital financed the deal via a $1.6 Billion sale-lease back agreement with American Realty Capital Partners, where Red Lobster would sell the land under all 600+ of its restaurants, and then lease it back at a rate that grows 2% every year. Considering Red Lobster’s real estate sold for $1.6 Billion, Golden Gate Capital must have thought the non-real estate parts of the company were worth about $500 Million—which include the restaurant’s net debt position and its economic assets like supplier relationships and brand name.
Red Lobster has always been either a private company, or a subsidiary of a publicly traded one that doesn’t break out its numbers, so exact figures are hard to find, though with some available figures it is possible to triangulate some key numbers. It appears that American Realty Capital Partners advertised the deal at a 9.9% GAAP cap rate, which means that Red Lobster would now pay $158 Million in rent annually to American Realty. Prior to this sale-lease back, Red Lobster was most likely paying just a 1% property tax in order to service its real estate, which would have amounted to $16 Million using the assessed property value from the transaction. This represents an additional $142 Million in annual expenses Red Lobster would have to service in the first year after the sale-leaseback. When accounting for the 2% annual rent growth in the deal, Red Lobster would be paying $170 Million in rent in 2018.
According to Forbes, Red Lobster’s entire revenue as of 2018 was $2.6 Billion. This means that the restaurant chain would have to find an additional 6.5% in margin in order to pay its rent. An additional 6.5% worth of margin is extremely difficult to find in the razor thin margin profile of the restaurant industry, where even the most profitable brands report a 10-15% net income margin.
One should assume that Golden Gate Capital did their due diligence on Red Lobster’s ability to pay their leases. That being said, even if on paper Red Lobster historically had the profit generating capabilities that would allow it to afford its lease payments to American Realty, it doesn’t justify the existential risk to the core business that a sale-lease back entails.
Due to how nearly every Red Lobster was corporate owned as opposed to franchised, if secular headwinds blow the profits out of Red Lobster’s sails, there is nothing in between the debtors of its real estate and the entire company. If Golden Gate Capital could get away scot-free, then they would have extracted $1.6 Billion out of Red Lobster’s business, but if Red Lobster cannot make the payments at any point in time then it would put the whole business in jeopardy.
This is exactly what happened. According to their Chapter 11 filing, the restaurant was hit hard by covid, and their annual guest count today is still only 70% of 2019 levels. This has significantly hampered their profitability, causing a 60% drop in adjusted EBITDA. When you resort to using adjusted EBITDA figures to report your profitability downturn, you know it is practically game over. The company’s 2023 lease payments were $200 Million, and it reported a $76 Million loss in 2023.
The company then filed for Chapter 11 bankruptcy, and in its filings it famously blamed its endless shrimp promotion.
The Endless Shrimp promotion was only responsible for an $11 Million loss, and was likely engineered to generate a loss anyways. If you can get customers in the door with endless shrimp as a loss leader, they are likely to order other more profitable items on your menu. It is from this perspective that the blame on endless shrimp is entirely baseless. Do not blame your loss leader product for bankrupting your company because it generated a miniscule loss in the grand scheme of things.
If Red Lobster didn’t do the sale-lease back, it would have saved $200 Million in lease payments, and reported a net profit of $100 Million—assuming lease payments are substituted by 1% property tax. Without money to pay its creditor, American Realty, the entire business just cannot operate. This is what sent the company into ruin. The sale-leaseback saddled Red Lobster with large lease payments with respect to the core business that it couldn’t pay, causing the entire corporation to fall into Chapter 11 bankruptcy.
Even though the once great Red Lobster is now bankrupt, Golden Gate Capital should have still done surprisingly well on its investment. In an effort to cut costs and exit some of its investment, Golden Gate sold 25% of Red Lobster to seafood supplier Thai Union. From the perspective of Thai Union, they would be able to realize major synergies with the restaurant chain, which justified the $525 Million price tag they paid for just a quarter of the company. These efforts failed, as Thai Union began to be more involved in supplying Red Lobster, their supply chain issues rippled deeper into Red Lobster’s business.
In their bankruptcy filing, Red Lobster blames Thai Union’s supply chain issues and also the pressure it had to ruthlessly promote endless shrimp to customers. It seems Thai Union had a total disregard for the well-being and longevity of Red Lobster, and just used the restaurant chain to pedal more of its own product.
Nevertheless, Golden Gate Capital’s $525 Million exit for 25% of the company already recoups the $500 Million of its own money it spent on the chain. There existed an additional clause for Thai Union to purchase Golden Gate’s remaining 24% of the company, which one can assume was likely in the ballpark of another $500 Million. Thai Union activated this clause in 2020, buying Golden Gate Capital out of Red Lobster. In total, Golden Gate spent $500 Million of its own money to buy the chain, and most likely received ~$1 Billion from Thai Union. The moral of this story must be: if you can find an investor stupider than you are to catch the falling knife, it doesn’t matter if you run the company into the ground.
Red Lobster is now undergoing a major transformation under its new CEO, Damola Adamolekun, who took over in 2024 after the company was pulled out of Chapter 11 Bankruptcy by Fortress Investment Group. Known for successfully revitalizing P.F. Chang's, Adamolekun brings a new strategic focus to the struggling seafood chain. His approach centers on menu innovation, operational efficiency, and leadership restructuring to restore the company’s financial health and brand reputation.
The company will most likely never be able to build back its real estate assets, so it must find a way to exist in its current lease-paying form. Since emerging from bankruptcy, small cost cuts like the reevaluation of endless shrimp will no doubt add up and help the company restore profitability. Adamolekun has also been trying to cut back on the firm’s lease payments by closing underperforming locations.
Red Lobster has reduced active locations by almost 20% after going bankrupt. These new cost cutting measures are designed to allow the company to payback creditors, and stop the franchise from bleeding EBITDA every year. That being said, the lease model will likely stand in the way of Red Lobster being restored to its former glory as a seafood real estate empire.


7Alder retweeted
Nuclear Energy, and How the Mid-Market Can Get Involved On Both Fronts
Nuclear Energy is back in the spotlight after a lethargic 60 years. Big tech’s interest in SMRs, Small Modular Reactors, to fuel their power-hungry data centers has driven a resurgence in interest in Nuclear Energy. Microsoft piloted the case to reopen the infamous Three-mile Island plant and purchased the rights to 100% of its power for the next 20 years.
Amazon led a $500M round of venture capital into SMR company X-energy and partnered up with Dominion Energy to explore using SMRs to power its data centers. Google is also in on the game and teamed up with Kairos Energy to hopefully get SMRs up and running by the decade's end.
The key driver behind this wave of next-gen nuclear energy investment stems from the proliferation of AI. Hyperscalers like Microsoft are expecting unrelenting demand for AI services in the upcoming years, which will rely on millions of power-consuming GPUs to crunch quintillions of matrix operations every second. Current estimates put a single ChatGPT query at using 2.9 Wh of electricity.
Considering how many prompts are thrown around, and the tendency for these models to get larger, more complex, and subsequently more power-hungry to run as we innovate, it’s clear that the local supply of electricity will quickly become a bottleneck.
This is where nuclear saves the day as a green, consistent, and compact source of energy. ESG-aware companies like Google do their best at being sustainable where it's convenient for them, but relying on inconsistent renewable energy sources like wind and solar just doesn’t make sense for their data centers that run 24/7. They’d either need to dip back into a fossil fuel-powered grid or install unheard-of amounts of battery capacity on-site to keep those data centers saturated with power. Not to mention the sheer amount of land the company would need to install solar panels or wind turbines. Nuclear is a solution to all of these problems. These SMRs are small and also don’t care if it’s day, night, sunny, cloudy, or windy out. It’ll be able to generate power consistently.
Even though SMRs are the new kids on the block, we mustn’t forget about the old guard. The US has been using nuclear power plants to generate electricity since the opening of Pennsylvania’s Shippingport Reactor in 1958.
Since then, companies like Constellation Energy, Entergy Corporation, Duke Energy, and TVA have been big names within the space, each operating multiple reactors. Barring Constellation's consolidated holdings of 21 of the nation’s 93 reactors, the industry appears quite fragmented.
This picture painted by data from the Nuclear Energy Institute isn’t as clear-cut as it seems. They count operators like Virginia Electric & Power as separate from the entity in which it is wholly owned by Dominion Energy.
Another operator, Florida Power & Light, is actually owned by NextEra Energy. This begs the question, are the little guys actually little? And are there any opportunities for smaller firms to cash in on legacy nuclear?
The answer to the first question is straightforward. 15 operators have 3 or fewer reactors in their portfolio.
However, after digging into whether any of these “Operators” are independent or small enough for mid-market firms to take a sizable stake in, the answer is unsurprisingly no. Even operators at the bottom of the list like Union Electric and Wolf Creek Nuclear are subsidiaries of larger utilities worth tens of billions. If you don’t have billions of AUM to spare, getting in bed with any of the legacy nuclear operators is nearly impossible. On a forward-looking basis—excluding the advent of SMRs—new legacy-scale power plants like Plant Vogtle are even putting corporations into bankruptcy. Toshiba paid $3.7B to walk away from the project after the plant's overrun construction budget bankrupted its subsidiary Westinghouse Electric.
This is not to say that it’s not possible to get involved in legacy nuclear as a sponsor. Carlyle had its foray into the industry via credit investments in nuclear plants, Brookfield bought a stake in Westinghouse in its emergence from bankruptcy, and Apollo is directly involved in financing the construction of Hinkley Point C, a new reactor for the Hinkley Point Nuclear Plant in the UK.
Even still, it looks like sponsor involvement in legacy nuclear still seems concentrated at the mega-fund scale.
Mid-Market Investment Fronts for Exposure to Non-SMR Nuclear
Picks and Shovels of Nuclear: Uranium
Even though the natural monopoly-like characteristics of the nuclear power industry restrict active sponsor involvement to the mega-fund scale, industries tangential to nuclear power plants exist. Assuming an aversion to the venture-type risk that comes with investing in SMR companies, the construction of new SMRs and legacy-scale plants will likely be a tailwind for Uranium, which is in an industry with lower barriers to entry—on a relative scale of course. There’s even a public company that is carrying out this strategy right now, Uranium Royalty Corporation.
The strategy Uranium Royalty employs is in the name, royalties. Their mission is to gain exposure to Uranium prices without imposing on themselves the operational and execution risk that a company would normally have to take on. They accomplish this feat by buying royalty interests in uranium mines and also trading physical uranium from time to time. The company, worth about $300M, buys royalties in mines owned by other companies, and the upfront price for these royalties can be as low as $300,000.
Those prices are real, the company just signed a $300,000 deal with a collective of mines in Spain called The Salamanca Project in return for a 0.375% net smelter return—meaning they get 0.375% of the project’s net revenue less transportation and refining costs. Currently, they own royalty interests in 19 different mines, owned by various mining companies, across the US, Canada, Spain, and Namibia. The royalties can take form in a myriad of ways: net smelter returns, net profit, gross revenue, gross value, etc. Uranium Royalty Corp has shown that there are no restrictions on where, who, or how you structure a uranium royalty.
This information is all made available through their 40-F, where management discusses why they see upside in risk-adjusted exposure to Uranium, in addition to some other strategies they are looking to employ in the future.
Nuclear Energy and the AI Play: Flow Control
While the uranium industry is quite literally the picks and shovels of nuclear power, another picks and shovels play is the industrial equipment required for data centers. If you’re underwriting a second golden age for nuclear via the effects of AI workloads on the power grid, you must also underwrite the need for industrial equipment at the data center level. In this case, perhaps a flow control company like Pfeiffer Vacuum might be of interest. They specialize in flow control generally but specifically offer solutions for the semiconductor, refrigeration, and energy industries.
These 3 industries are crucial to the data center play. Of course, more AI demand means more data centers, but that comes hand in hand with more chip demand and additional semiconductor fabs to service it. Fabs need flow control equipment for a myriad of mission-critical processes—which you can find on the Pfeiffer Vacuum website.
Refrigeration is another tailwind for flow control at the data center, 100% of the electricity pumped into any chip is eventually expressed locally as heat. Cooling is the utmost priority for anybody who wants their new Blackwell chip to function at anything higher than 1% utilization. The advent of new data centers will no doubt require flow control for both air and liquid refrigeration techniques.
On the nuclear energy front, flow control equipment is necessary in every core function. The centerpiece of how a nuclear reactor generates power comes down to directing steam through a turbine, none of which is possible without specialized flow control equipment. Seeing as though a flow control company like Pfeiffer Vacuum is only partially exposed to the brunt of a possible downturn in data center demand, it opens the door for mid-market players to gain exposure to the AI-Nuclear energy growth trend without taking on VC levels of risk with SMRs. A strategic way to get involved in a company like Pfeiffer Vacuum that is worth $1.5B would either be to acquire a significant minority stake, or more realistically gain exposure via debt instruments like convertible bonds or even mezzanine financings.
Follow & Like if you got this far!

