

Equity Research @Rebellionaire. Primarily covering Upstart, but deep diving other companies too. Posts are not financial advice. #UTPI
Wisconsin, USA
Joined June 2021
- Tweets19.4K
- Following789
- Followers6.5K
- Likes79.1K






Pinned Tweet
$UMAC
Unusual Machines appears on planning to use OSC capital to parallelize their 100,000 motor / month automated line that they plan on having online by year end (4Q26).
Last week, CFO Brian Hoff suggested UMAC seeks 6-8 additional lines which could produce 8-10M motors per year with extra flux capacity if needed (10M motors / 7 lines = 1.4M per line / 12 months = ~119,000 motors per month per line).
Brian also suggested these additional 6-8 production lines would fulfill Group 2 and Group 3 drones - which are larger in size - therefore potentially dragging ASP (average selling price) higher on components.
Not financial advice - but I took a swing at modeling out what the Defense ONLY portion of Unusual Machines' motor business could look like with an OSC capital infusion.
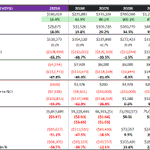
By Q3 2028, this model assumes UMAC has 8 automated motor equipment lines up and running, kicking 9.6M motors per year at an ASP of $57.
We learned from Allan that in 2Q26 UMAC made and shipped just under 50,000 motors in the quarter. Further, 13% of 2Q26 revenue was attributable to their largest product. Assuming that's motors, you arrive at an ASP of ~$43.47 ((0.13 x $16.7M) / 50,000).
That's why this model starts at ~ $43 ASP in 2Q26 before being dragged up ~33% in totality by the end of 3Q28 on the assumption of additional lines being used for Group 2 and 3 drones. To state the obvious, there's a lot of guesswork here. On 9.6M motors at a $57 ASP, you land at ~$550M run rate on motors alone in 3Q28.
Gross Margins are assumed at 38% throughout - the midpoint between 2Q26's ~35% and UMAC's 40% LT target. That yields ~$208M of annualized gross profit in 3Q28.
CapEx for the tangible, physical equipment of each line is estimated to be ~$4M, with the rest (overhead, salaries, raw materials) assumed to be financed by the OSC.
The model is far from perfect - but Cumulative Gross Profit less CapEx is treated as cash generation and added back to implied Enterprise Value along with 2Q26 Net Cash.
OpEx as a % of Revenue is assumed to be ~19% for this production line - a majority of UMAC's overhead runs through COGS (which improves as employees become more efficient). D&A assumed at 1% of revenue.
That leaves us with an implied 20% EBITDA Margin on the motor business (38% Gross Margin - 19% OpEx as a % of revenue + 1% D&A add back). Applying an assumed 25x EV/EBITDA multiple on the implied 3Q28E EBITDA (with 8 automated lines up and running) spits ~$2.7B in implied Enterprise Value. 25x in my view is justified as by this time UMAC will be growing very fast - with drone delivery and potentially robotics as additional growth tailwinds.
After adding back Net Cash, the Cumulative Gross Profit less Capex and subtracting Working Capital OpEx (estimated a 1x annualized revenue) leaves ~$2.67B in implied equity value in the Defense Motor business alone.
That suggests UMAC's Defense ONLY Motor business may be worth $38.30/share.
Of course - there are SO many assumptions going into this (plus the $ figure isn't discounted) and the math almost certainly doesn't reconcile 100%. But - I think this analysis is directionally correct.
In my opinion, the drone industry is at the beginning of the S-Curve and Unusual Machines is ready to ride it with the help of some OSC capital.

Henry retweeted

Unusual Machines $UMAC lands $16.9M drone component order from PowerUS
stocktitan.net/sec-filings/U…

Henry retweeted

This video has aged very well. We will always be willing to change our mind when new information comes to light.
But the harder thing can be to actually make a change in the portfolio when the relative opportunities have shifted. Rebellionaire helps clients make those tough decisions in real time.

What are Rebellionaire's SpaceX vs Tesla Growth Expectations?
SpaceX could be generating 1.5x Tesla's profits by Q1 2027, with 6x the revenue growth.
And by Q1 2028, SpaceX could see ~600% profit growth.
This is bull-case Tesla vs base-case SpaceX and it changes everything about the merger.
The numbers shocked us.
What do you think?
*Timestamps*
0:00 Intro
1:10 Tesla Q1 2027 Bull Case
5:03 SpaceX Q1 2027 Projections
9:28 Tesla vs. SpaceX: The Problem
11:58 Wall Street's SpaceX Blind Spot
15:42 SemiAnalysis & 2028 Outlook
17:19 Changing Views on the Merger
21:21 Still Tesla Fans
Data centers & #AI have a massive PR problem🛑
Memphis, Tennessee is the latest battleground. The City Council just passed a 135-day PAUSE on new data center development.
The catch? Locals wanted a 12–18-month moratorium - which City Council struck down.
Catch all this and more in under 6 minutes @Rebellionaire 👇
Local opposition is becoming a real bottleneck for AI data centers.
Memphis shows why.
On October 20 its city council tied 6-6 on an extended moratorium but passed a 135-day pause on new construction.
Henry's view: if city councils side with the communities, it could be a real risk to the data center build-out.
What do you think?
*Timestamps*
0:00 Local Opposition Is a Major Bottleneck
0:40 SpaceX's Colossus Cluster in Memphis
1:27 Memphis Weighs a Moratorium
2:10 Chaos at City Hall
2:43 Residents' Concerns Are Reasonable
3:40 The Moratorium Fails on a Tie
4:23 Memphis Passes a 135-Day Pause
4:46 Local Opposition Is a Risk
@HenryInvests
$SPCX
Rebellionaire clients and employees own SPCX and NVDA stock.
Henry retweeted
Four of the nine Gauntlet II winners are Unusual Machines $UMAC customers

Drone Dominance Program Gauntlet II orders are in the works.
Perennial Autonomy received the top award for the Deep Strike mission area, and Neros Technologies took top marks in the Close Quarters Battle mission area. Each received the maximum initial order of 8,000 units.
Other top performers included Hyperscale, Skycutter, Swarm Defense Technologies, ORQA US, XTEND Reality, Vector and ModalAI. Each received orders from the 60,000 pool based on performance.
Congratulations to all the winners. Now, it’s time to deliver.
View the full leaderboard here: dronedominance.mil/leaderboa…

$SPCX
Let's say SpaceX truly has ~15GW online end of 2027.
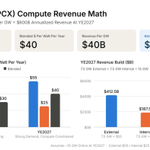
Pricing: External "slightly above high end of $30-$50 per Watt" - call it $52 per Watt per Year on external compute today, ~$55 per Watt YE27 (strong demand, compute constrained).
External compute is ~50% of the mix, other half used for Internal which let's assume monetizes at $25.0 per Watt per Year as Grok / Grok Bot scale by YE27 (Still less than half the return of selling external compute).
That's a blended ~$40.0 per Watt per Year at YE27 (($55 x 0.5) + ($25 x 0.5)). In other words- $40B in revenue per GW.
15 GW x $40B per GW = $600B annual revenue.
🤷♂️ the math works, don't even ask me about 20GW!

How much demand for AI hardware / optics / networking does SpaceX $SPCX create alone if they bring online 13 GW of compute next year?
Elon is highly confident of this. OpenAI and Anthropic are expected to add 14 to 15 GW each in 2027. SpaceX right up there.
Demand is insane.

ELON MUSK TARGETS 13 GW OF AI COMPUTE BY 2027, WITH 440,000 NVIDIA VERA RUBIN GPUS IN A SINGLE TRAINING CLUSTER
Musk says SpaceX is on track to bring roughly 200,000 $NVDA GB300 GPUs online per month for the remainder of 2026, with deployments continuing at a similar pace next year, primarily using Vera Rubin.
The company expects to have 2.5-3 GW of compute online by the end of 2026, with another 10 GW potentially coming online in 2027.
Musk also plans to have a 440,000-GPU Vera Rubin training cluster operational by the end of Q2 2027.
To support the expansion, SpaceX is targeting an additional 20 GW of power and cooling infrastructure next year.
Musk said there is a “non-zero possibility” of exceeding 20 GW of operational AI compute in 2027, although he acknowledged the probability remains small.


Upstart $UPST 8-K: Up to $200M Revolver to fund initial capitalization of Upstart Bank.
~$200M or so will be used to open Upstart Bank, purchase loans from Upstart Network, who will then take that $ and pay off the revolver. Priced at SOFR + 300bps.
@paulxgu
ir.upstart.com/static-files/…
Rumble's $RUM pivot to AI Compute is (surprisingly) very real - they've signed a $13.7B deal with Anthropic.
@Rebellionaire took a deep look at Rumble back in August and thought they had a great chance at landing a large deal with a hyperscaler.
We didn't end up investing, but the research process here was fascinating and thorough. What an interesting business!
Rumble's pivot to AI compute looks real.
So does the bill for building it.
In our best case, its 2027 revenue could reach about three times Wall Street's August estimate.
We still didn't invest.
Henry's view: Rumble may need to raise billions to build it out, a lot for a company worth about $3 billion.
What do you think?
*Timestamps*
0:00 Rumble Is Pivoting to AI Compute
1:22 Free Speech Meant Owning Data Centers
2:45 Tether Paired Rumble With Northern Data
5:46 Quake AI's Revenue Math Is Aggressive
7:19 Best Case Near 3x Wall Street
8:35 If Rumble Traded Like a Neocloud
9:30 Why We Passed: Funding the Build-Out
@HenryInvests
$RUM
@chrispavlovski check us out... this is pretty good coverage on $RUM. Always open to a Q&A chat!
Henry retweeted
Rumble's pivot to AI compute looks real.
So does the bill for building it.
In our best case, its 2027 revenue could reach about three times Wall Street's August estimate.
We still didn't invest.
Henry's view: Rumble may need to raise billions to build it out, a lot for a company worth about $3 billion.
What do you think?
*Timestamps*
0:00 Rumble Is Pivoting to AI Compute
1:22 Free Speech Meant Owning Data Centers
2:45 Tether Paired Rumble With Northern Data
5:46 Quake AI's Revenue Math Is Aggressive
7:19 Best Case Near 3x Wall Street
8:35 If Rumble Traded Like a Neocloud
9:30 Why We Passed: Funding the Build-Out
@HenryInvests
$RUM
".. At the moment, we have more compute capacity than we have demand" - this is objectively not true.
Unless of course AI is at large engaging in an industry-wide psyop (including in private settings & conferences).
The concerns surrounding AI returns not justifying the level of CapEx is more reasonable and balanced, although I also disagree with that.

“.. At the moment, we have more compute capacity than we have demand, and we have a lot of the tokens and processing power being given away in freemium solutions,” he told @CNBC. “Everyone in the AI race is running for a last-man standing position.”
cnbc.com/2026/10/19/gartner-…

Henry retweeted

🎯 $UMAC | Unusual Machines says it completed the Upgrade Energy acquisition, adding drone batteries and power systems to its component lineup.
FACTS
• The target is DroneNX LLC, operating as Upgrade Energy.
• The company said the deal expands its portfolio to include batteries alongside motors, headsets and other drone components.
• Ahead of closing, Unusual Machines said it had begun scaling battery production and hiring at Upgrade Energy's 18,500-square-foot facility in Torrance, California.
• It also plans battery pack operations in Orlando, Florida.
WATCH
Financial terms and expected contribution were not disclosed. The Orlando buildout and production-scaling comments are forward-looking.
Source: suite.accessnewswire.com/new…
Henry retweeted

1 thing I'll always respect is work ethic, especially from the younger generation here on X.
There are some young bucks putting in serious hours who don't get nearly the recognition they deserve. Age means absolutely nothing in this business; results are all I care for.
A few young bucks I keep up with weekly:
@Nickstro_
@vstocks7
@YousufTrades
@insidegadsmind
@luke_vol
@ashtradin
@HenryInvests
Keep grinding, lads.
Am I missing anyone?
Drop some recommendations below, I'd love to find more young traders to connect with.