

PM at Diamond Capital Management
Joined September 2021
- Tweets4.3K
- Following598
- Followers6K
- Likes4.6K


"When we analyze companies, we don't talk to CEOs. ... We talk to purchasing managers. Purchasing managers tell you what is happening right now with supply chains and orders." - Stan Druckenmiller
Well, right now, purchasing managers are unanimous...
The manufacturing sector is poised to *accelerate*


It's hard to imagine core inflation durably accelerating with the labor market so soft (recall: AHE +3.0% YoY in September, lowest level since 2021)
Wage growth accounts for 58% of the observed variation in core inflation and 77% of services inflation ex. energy
To know where core inflation is heading, watch the labor market...


I know no one wants to hear this... But we are still mid-cycle
Not late-cycle
Do you know what that means for growth, inflation, stocks, etc?

CapU, low
Shipment volume, low
Hiring, low
RE tx volumes, low
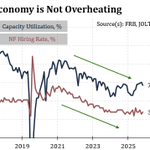
US economy is not overheating. Evidence that current inflation is mostly oil, for now

Economically, today is nothing like 2022 and markets are unlikely to trade as such for any extended period of time.
In late 2021, the whole US economy was capacity constrained - manufacturing capacity, labor markets, energy, etc.
This was reflected in a million different data points - capu across industries, the unemployment rate, wage growth, rig count, and of course inflation
In late 2021, core inflation was running 6-7% annualized with fed funds rate near zero. In other words, the Fed was wayyy behind the curve.
Today, core inflation is 2.5-3.5% with a fed funds rate between 3.75-4.00%. Additionally, capu is low, the hiring rate is at recessionary levels, housing is completely stuck and there is very little evidence of broad overheating
Can rates reprice slightly higher from here? Or stocks a little lower? Of course. Is $TLT going to be cut in half again? No shot. Are stocks going to trade 30% lower? Very, very improbable unless economic conditions change dramatically
Most likely stock market just need a short period of time to digest the move in rates.
FYI I know Jim is a (great) trader and not implying today is the same as 2022. But there are a lot of bad macro takes out there.
Mike Singleton, CFA retweeted
It's been a choppy September (not a surprise seasonally) and especially hard on rate-sensitive stocks ($IWM down 4.3% MTD)
But the seasonal bottom is approaching... Sep 29... And Q4 through mid-term years is historically strong (+330 bps vs all calendar quarters)
Will this time be different?

Lots of discussion about when rates stop going up, and the answer (though trite) is "when bonds become attractively priced"
And there's evidence we're getting there. Nominal yields >5% and term premia rising across the curve
TIPS stand out as especially interesting here, especially if you're worried about deficits/inflation...
Lock in 2.5-3.0% real return? Not bad.

Economically, today is nothing like 2022 and markets are unlikely to trade as such for any extended period of time.
In late 2021, the whole US economy was capacity constrained - manufacturing capacity, labor markets, energy, etc.
This was reflected in a million different data points - capu across industries, the unemployment rate, wage growth, rig count, and of course inflation
In late 2021, core inflation was running 6-7% annualized with fed funds rate near zero. In other words, the Fed was wayyy behind the curve.
Today, core inflation is 2.5-3.5% with a fed funds rate between 3.75-4.00%. Additionally, capu is low, the hiring rate is at recessionary levels, housing is completely stuck and there is very little evidence of broad overheating
Can rates reprice slightly higher from here? Or stocks a little lower? Of course. Is $TLT going to be cut in half again? No shot. Are stocks going to trade 30% lower? Very, very improbable unless economic conditions change dramatically
Most likely stock market just need a short period of time to digest the move in rates.
FYI I know Jim is a (great) trader and not implying today is the same as 2022. But there are a lot of bad macro takes out there.

It's been a choppy September (not a surprise seasonally) and especially hard on rate-sensitive stocks ($IWM down 4.3% MTD)
But the seasonal bottom is approaching... Sep 29... And Q4 through mid-term years is historically strong (+330 bps vs all calendar quarters)
Will this time be different?
In today’s rapidly evolving landscape, we need to stop using AI to write—full stop. It’s not about efficiency. It’s about authenticity. So let’s delve in, embrace the messy, and unlock the transformative power of sounding human. Because writing isn’t merely a tool for communication—it’s the heartbeat of genuine connection.


Mike Singleton, CFA retweeted

For a university founded in 1808, Emmitsburg’s @MSMU has surprisingly few #books telling its story. That bothered alumnus John Singleton, Class of 1986, enough that he wrote one himself. catholicreview.org/new-book-… #Colleges #LocalNews #WesternVicariate
