

Numbers that explain AI & markets. Daily data cards and satisfying Shorts. No hype, no advice.
Global markets · US/EU/Asia
Joined August 2024
- Tweets17.7K
- Following4.1K
- Followers2.2K
- Likes12.7K




Pinned Tweet
Bottom line: AI infrastructure demand continues to outstrip memory and packaging supply, extending the pricing cycle into 2027.
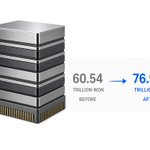
SK hynix Q3 operating profit: 83.33 trillion won at 80% margin.
• Hyperscaler 2026 capex guidance: Amazon ~$220B, Alphabet $195-205B, Microsoft ~$175B, Meta $130-145B. Combined midpoint ~$732B.
• TrendForce sees conventional DRAM contract prices rising 10-20% QoQ in Q4.
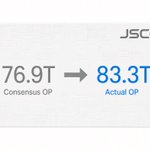
Bottom line: SK hynix Q3 operating profit beat consensus by roughly 6.4 trillion won on sustained AI memory pricing.
83.3 trillion won actual versus 76.9 trillion won consensus.
First quarterly revenue above 100 trillion won and 80 percent margin as HBM4 volumes ramp.
Yonhap
(Public figures compiled. Not a buy or sell recommendation.)

One $12 lunch a week adds up to $6,240 in 10 years. Pack it or buy it?
That's $52 a month and $624 a year before you even notice.

TQQQ +3.81% vs QQQ +1.27% yesterday: 3x did 3.00x
QQQ +1.27%
QLD +2.45% (1.93x)
TQQQ +3.81%
JEPQ +1.15%
QDTE +1.34%
QQQI +1.20%
GPIQ +1.22%
Clean up day: leverage landed on target, covered calls stayed within 0.12 pts of QQQ.
Close-price tracking. Not financial advice.


Bottom line: Broadcom residual value support backstops the $43.5 billion senior slice of a $63 billion Anthropic chip lease financing.
Deliveries of the accelerators and networking gear begin in 2027 through an SPV that owns the hardware.
Anthropic rents the capacity instead of buying it, moving residual risk onto the supplier’s balance sheet.
Reuters
(Public figures compiled. Not a buy or sell recommendation.)
Bottom line: Export-model estimates put Samsung ahead of SK hynix in third-quarter HBM revenue for the first time.
8.7 billion dollars for Samsung versus 7.6 billion for SK hynix.
The 1.1 billion gap arrives the same week both companies report record memory profits.
Company disclosures will test whether the long SK lead has actually flipped.
Source: Korea Herald
(Public figures compiled. Not a buy or sell recommendation.)
🤖 Made with AI


More than half of 2027 and 2028 capacity is already locked under 5-year LTAs with deposits.
That turns HBM from a cycle trade into a backlog trade. Only the remaining <50% still floats on spot pricing.

SK HYNIX:
- HAS SIGNED LTAS WITH 14 MAJOR CUSTOMERS, INCLUDING LARGE GLOBAL CSPs.
- THE STANDARD CONTRACT TERM IS FIVE YEARS, WITH DISCUSSIONS UNDERWAY WITH SOME CUSTOMERS TO EXTEND EXISTING CONTRACT TERMS.
- PRICING GENERALLY REFLECTS MARKET CONDITIONS WITHIN A RANGE AGREED UPON WITH EACH CUSTOMER.
- THE AGREEMENTS INCLUDE DEPOSITS AND OTHER MECHANISMS TO ENSURE CONTRACT FULFILLMENT.
- VOLUMES CURRENTLY SECURED UNDER LTAS ACCOUNT FOR MORE THAN 50% OF TOTAL CAPACITY IN EACH OF 2027 AND 2028.
Bottom line: SK hynix third-quarter operating profit consensus is 76.96 trillion won.
76.96 trillion won represents a 27 percent sequential increase from the 60.54 trillion won reported in the second quarter.
The implied 78 percent operating margin on near-98 trillion won revenue shows pricing power still outweighs volume growth into the print.
Source: Newsis
(Public figures compiled. Not a buy or sell recommendation.)
🤖 Made with AI


TQQQ +3.81% vs QQQ +1.27% yesterday: 3x did 3.00x
QQQ +1.27%
QLD +2.45% (1.93x)
TQQQ +3.81%
JEPQ +1.15%
QDTE +1.34%
QQQI +1.20%
GPIQ +1.22%
Clean up day: leverage landed on target, covered calls stayed within 0.12 pts of QQQ.
Close-price tracking. Not financial advice.

S-1 math: $131.7B of cash and short-term investments vs $265.6B of fixed or minimum compute commitments.
The pile covers roughly half of what's already promised to the clouds. IPO proceeds close that gap before they fund anything new.

