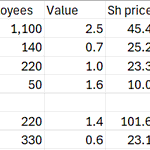$ABEO Just thinking what results in the upcoming earnings call might lead to a more optimistic view. What do we need? 1 patient treated? 3 treated? 30 more identified? Additional treatment centers?
Clearly, very little belief currently that the path to profitability is there.
Market reaction leaves me thoroughly puzzled. What did the buyers today expect that didn’t materialise? It could have been worse, sure, but for me the Q3 results confirmed my assumed bear thesis. Anyone here can clarify the disconnect?
$ABEO update ahead of Leerink slightly more positive than I expected: “Since resuming manufacturing in late Jan, multiple biopsies … collected, a patient has completed treatment …, and ... ongoing manufacturing runs. Additional biopsies are scheduled for … this quarter.
$QURE valuation - my napkin approach: I assume they will have to do a confirmatory study. $4b sales before read-out, risk weighted $6b sales afterwards. Odds of approval around 2/3. Discounted to today makes $2.7b mc. There is a bit of pipeline as well, so ~$3b.
$QURE val update: FDA not constructive. I’d be slightly more optimistic than the market now with $700-900 market cap as fair value based on some potential for a quicker than 3 yr resolution.
$QURE: That was quicker than anticipated but who could have guessed VP was so fed up with his job. Huge regulatory gamble still but clearly better odds than before, plus MHRA interest to shine. $1.3 to $2b mc fair value right now but some hope of short term speculative overshoot.
$IONQ$RGTI$QBTS$QUBT$OKLO$SMR
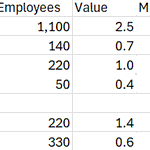
To illustrate that there is still plenty of room for these companies to fall, here's my quick valuation guide adding liquid assets and giving a value of $1m for each employee.
Please let me know of any companies with a higher overvaluation.
$IONQ$RGTI$QBTS$QUBT$OKLO$SMR
I've updated the table with the missing Q3 for $QUBT. They managed to raise a staggering $500m in Q3 plus $750m after Q3 (=eternal runway). It's still a bad investment but it's a much less attractive short now, and I covered.
Not sure what to make of the answers to Adam’s tweet below. I think it’s undeniable that we’re currently not longer in deep value territory.
Does the easiness by which everyone dismisses that speak to the coming of easy money for biotech or is it indeed some kind of top signal?