




🚨 $CIFR — THE MARKET IS MISSING AN IMPORTANT DISTINCTION.
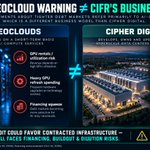
Elon Musk warns that tighter debt markets could wipe out smaller AI-only neocloud operators.
But Cipher Digital operates a DIFFERENT business model.
✅ Develops and owns hyperscale data centers
✅ $16.6 BILLION in contracted HPC revenue
✅ 700 MW of contracted HPC capacity
✅ 17.3-year weighted average lease term
✅ Recently priced $850M in 0% convertible notes
Here's the opportunity:
If financing becomes increasingly selective, companies with secured power, long-term customers and access to capital could gain a significant competitive advantage.
Smaller operators may struggle to expand. Meanwhile, established infrastructure developers could benefit from reduced competition and greater scarcity value.
$CIFR is not immune to financing, execution or dilution risks, but Musk's warning doesn't automatically undermine its business model.
In fact, it could reinforce the long-term bull thesis.
VERY BULLISH on $CIFR over the long term. 🚀
#CIFR #AI #DataCenters #HPC

🚨 AI DATA CENTER BOOM IS FAR FROM OVER.
Bank of America projects global data center spending to surge:
2026: $1.0 TRILLION
2028: $2.1 TRILLION
2030: $2.93 TRILLION
That's a massive opportunity for AI infrastructure, power and cooling.
Bullish long-term for $CIFR $MOD $VRT $IREN $CRWV $APLD $NVDA $AVGO.
The buildout is just getting started. 🚀
reuters.com/business/data-ce…


My entire feed is suddenly predicting a bear market, Black Monday, a flash crash or the AI bubble bursting.
The speed at which conviction turns into panic is incredible. A few brutal sessions and suddenly everyone is convinced the whole investment thesis is dead.
I’m skeptical when falling share prices become the main evidence that AI demand has disappeared.
The questions that matter: Are customers cutting spending? Are orders getting cancelled? Are earnings expectations deteriorating? Can these companies finance and deliver their projects profitably?
Those deserve scrutiny. Repeating “oversupply” under every red chart isn’t analysis.
Semis, networking, cooling and powered data centers serve different parts of the same buildout. Their risks differ, but a sector selloff doesn’t automatically invalidate every business.
I’m staying bullish on AI infrastructure long term while watching execution closely. Nobody knows where the bottom is—but panic alone won’t tell you where fair value is either.
$NVDA $MU $AVGO $CRDO $IREN $CIFR $APLD $MOD
$CIFR convertible offering terms are out:
✅ $850M raised at 0% interest
✅ 35% conversion premium ($15.31)
✅ Capped-call protection up to $28.35
⚠️ 40.7M shares expected from the separate 2030 notes exchange
Dilution is real, but so is the value of securing long-term, interest-free capital for AI infrastructure.
Bullish on the long-term setup. $MOD

$CIFR Retail investors are just panic selling at this point.
I actually think Tyler's move is bullish. He's securing financing to support the company's long-term growth, even if it comes at the cost of short-term share price pressure.
The market is reacting emotionally, but I believe this decision will reflect positively on the share price over the medium to long term.
Short-term pain, long-term gain. I'm staying bullish on $CIFR. 🚀
🚨 BIG CONVICTION IN $CIFR
Mike Alfred's reported $211M portfolio:
🥇 $CIFR – 39.57%
🥈 $IBIT – 17.65%
🥉 $IREN – 16.25%
🔹 $OPEN – 10.36%
Nearly 40% of his portfolio is in Cipher Mining, with another 16% in IREN.
That's over 55% exposure to just two Bitcoin mining / AI infrastructure plays.
He's also reportedly on $IREN's Board of Directors.
Bullish signal for $CIFR? 👀🚀
#CIFR #IREN #Bitcoin #AIInfrastructure
$CIFR


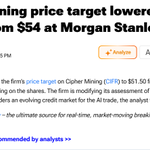
Morgan Stanley just posted a $51.50 price target for $CIFR, maintaining its OVERWEIGHT rating!
That's nearly 4x the current share price!
With billions in contracted AI data center revenue and strong long-term demand, $CIFR looks massively UNDERVALUED at these levels.
Don't miss this opportunity!
$CIFR $IREN

$MOD still looks like one of the more under-the-radar ways to play the AI infrastructure buildout.
Data center cooling demand remains strong, while power availability — not lack of AI demand — is increasingly becoming the bottleneck for new capacity.
The main near-term headwind is macro: the 10Y around 5.3% is tough for valuations.
For me the setup is simple: strong underlying demand + expanding cooling capacity, with rates being the key risk to watch.
Long $MOD.
AI demand keeps showing up in the numbers. Micron’s customer supply commitments rose to $32B from $22B in June.
Meanwhile, October Fed hike odds fell to roughly 20% from 70% this week.
My take: an improving backdrop for AI infrastructure, but higher bond yields still matter. Watching cooling, power, optics and compute.
$MOD $IREN $CRDO $FN $NBIS $AAOI $APLD $BE
The AI infrastructure story is moving deeper into optics. 👀
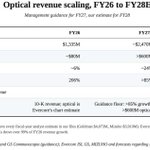
$CRDO FY26 revenue: $1.34B
FY27 growth guidance: >85%
FY27 optical revenue guidance: >$600M
The really interesting part: CRDO is no longer just an AEC story. Optical DSPs, silicon photonics and complete optical solutions are becoming a second major growth engine.
The chart below extrapolates that optical revenue could eventually approach $1.45B in FY28 — that part is an estimate, not management guidance — but the direction of travel is clear.
And this trend doesn't stop with CRDO.
If AI clusters keep moving toward 800G → 1.6T → higher-speed optical connectivity, the entire photonics ecosystem should see increasing demand:
$CRDO — optical DSP / SiPho / connectivity
$FN — advanced optical manufacturing & packaging
$COHR — lasers, transceivers, optical components
$LITE — optical components & lasers
$AAOI — datacenter optical transceivers
$GLW — fiber & optical infrastructure
$MRVL — optical DSP / interconnect silicon
$AVGO — networking + optical connectivity silicon
For $FN specifically, this is why I keep watching it closely. While CRDO monetizes the technology, Fabrinet can benefit from the manufacturing complexity and sheer volume of optical hardware required across multiple hyperscalers and vendors.
AI compute gets the headlines.
But moving all that data is becoming one of the biggest bottlenecks.
And optics may be one of the strongest AI infrastructure themes into 2027–2028.
$CRDO $FN $COHR $LITE $AAOI $GLW $MRVL $AVGO

🚨 BULLISH INFLATION DATA FOR STOCKS 📈
The Fed’s preferred inflation gauge just came in cooler than expected:
🔹 Core PCE MoM: +0.2% vs +0.3% expected
🔹 Core PCE YoY: 3.0% vs 3.3% expected
🔹 Headline PCE YoY: 3.4% vs 3.7% expected
Treasury yields dropped and stock futures immediately moved higher. The probability of an October Fed hike also fell following the report.
After weeks of the market worrying about sticky inflation, rising yields and another Fed hike, this is exactly the type of macro print growth & AI stocks needed.
Cooling inflation → less pressure on the Fed → lower yields → better environment for long-duration growth stocks.
Bulls finally got some good macro news. 🐂📈
$QQQ $SPY $NVDA $MU $CRDO $FN