

Looking for niche market leaders with long investment runways. Not financial advice. Always do your own due diligence.
Joined January 2021
- Tweets395
- Following361
- Followers9.7K
- Likes2.3K





This time around, sell-side analysts are stubbornly holding onto their target prices for memory producers. For Kioxia $285A.T, the gap between its closing price and the consensus target price has widened to 220%. Someone needs to start working on a new story right about now.

$255A.T GLTechno raised full-year guidance today, and the stock is selling off (again). Sure, at 9 P/E, market expectations must be off the charts, and 15%+ operating profit growth is terrible. For context, the semi order backlog was up 130% YoY and 51% QoQ last quarter.


$255A.T GLTechno had arguably the best quarter among my holdings, yet the stock fell 4% after the results came out last Friday and finished down 11%. The semiconductor business is firing on all cylinders: sales are accelerating, margins are expanding, and orders are booming. The order backlog is up 130% YoY and 51% QoQ, with a book-to-bill ratio at 1.7. Applied Materials $AMAT is placing massive orders for GLTechno’s quartz glass components to service installed equipment and build new tools. In turn, GLTechno plans to double its flame-processing capacity in Japan starting in January 2027. As a bonus, the analytical instruments business is also performing well, fueled by robust sales of water-testing consumables.
At 12 P/E, I think GLTechno has the highest risk-adjusted upside across my AI-related positions and buy candidates. It deserves a higher portfolio weight.


Chances are Korea will be ripped to pieces in the short term. What are you looking to buy? Aside from direct AI beneficiaries, I’m thinking defense (Hanwha Aerospace $012450, MNC Solution $484870, Firstec $010820), power equipment (Hyundai Electric $267260, Hyosung Heavy Industries $298040), and ships (HD Korea Shipbuilding & Offshore Engineering $009540, Hyundai Marine Solution $443060). Give me what you got.
Monolith Capital retweeted

1) Aichi Electric $6623.T with a blow-out FY27Q2 report (sales +26%, OP +69%) last night + upped FY27 guidance for 2nd quarter in a row. AI beneficiary still at a deep value price (0.9x TBV, 4.4x EV/EBIT, 8.3x P/E with 26% of market cap in net cash+investments)


How are you doing, ladies and gentlemen? The loud cries of despair here suggest some of you are having a near-death experience. Hold strong, don’t panic. We’ll get through this patch of bad news, just like we did countless times before. See you on the other side, champions.

$6643.T For a final surprise, Togami sharply increased its profit guidance for Q2 today after hiking product prices earlier this year. This company has become dirt cheap, despite excellent execution and improving shareholder returns. Easy double. (allegedly)

Togami Electric ($6643.T) is off to a good start this year: sales increased 12% while operating profit jumped 40% in Q1. Rising demand for electrical distribution equipment and higher prices for key products are driving earnings growth, as Japan upgrades its power grid. The revised guidance is conservative – I think operating income will turn out 15-20% higher than expected. Management should raise dividends from today's sub-30% payout and accelerate buybacks, as cash continues to pile up and now equals ~28% of market cap. I believe Togami is significantly undervalued and see it doubling in the next 24 months. I will maintain my current position.


$6135.T Makino also crushed it: revenues rose 19%, operating profit jumped 60%, and orders increased 26% last quarter. Order growth surpassed sales growth across all regions, with aerospace, semiconductor, automotive, and medical applications boosting demand for complex machining. Management raised the full-year OP forecast by 32%. At ~12 P/E, Makino is too cheap for what it offers. I'm holding.


The world is ending, but FUSO Chemical ($4368.T) keeps printing. Last quarter, revenue rose 20%, and operating profit surged 41% YoY, driven by strong silica demand, price revisions, a weak JPY, and fixed-cost leverage. Remarkably, the electronic materials business generated an incremental OP margin of 70%, despite higher depreciation charges on new silica facilities and a small QoQ sales decline. Management again raised revenue and profit guidance for this year, citing resilient demand for semi materials.
I don’t think this gravy train will stop until TSMC factories go dark. FUSO supplies leading-edge CMP process consumables, which grow with wafer output and new CMP applications. FUSO is the largest position in my portfolio. The company trades at ~15 P/E, despite 20%+ earnings growth and high incremental ROIC. I see about 50-60% upside today.


$4368.T FUSO Chemical trades at a discount to CMP slurry formulators (Fujifilm, Entegris, Qnity Electronics, Anji Microelectronics), even though its competitive advantage is arguably stronger and more durable. FUSO has effectively monopolized the ultra-high-purity colloidal silica market and has become a critical supplier to leading-edge chip production lines globally. Strong performance figures sustained over multiple quarters, recent silica price hikes, and investor outreach should improve the company’s perception over time.


$6777.T Great to see Santec’s advanced optical instruments finally being specified for high-volume manufacturing equipment, rather than just R&D labs. GMT Global ($4573.TW) lists Santec’s tunable lasers and power meters in a standard configuration of fiber-array and lens-coupling stations used to make transceivers and optical components. GMT achieved explosive growth this year, with cumulative sales up 208% through September.
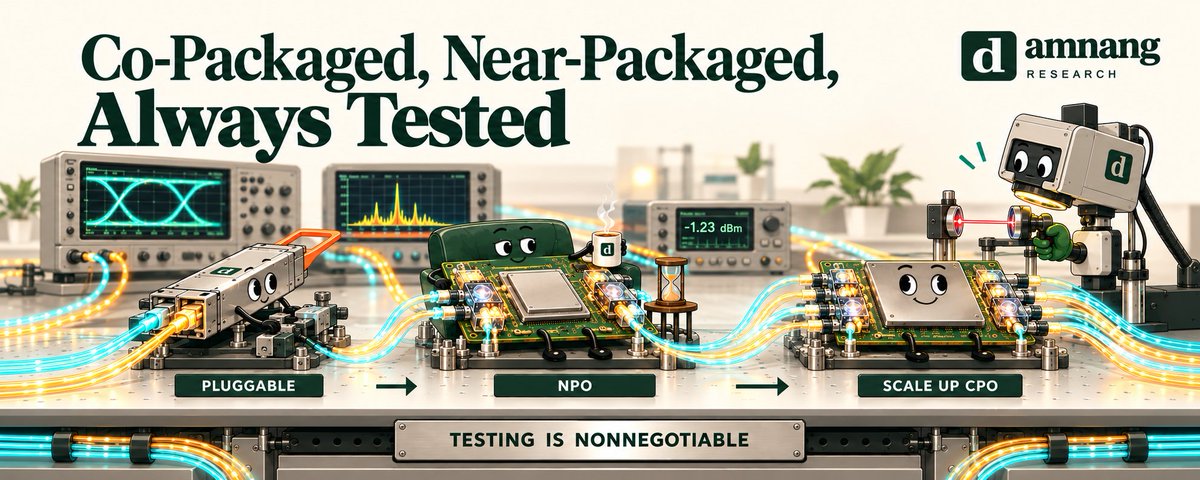
In August, Santec told me that “our measurement instruments in this area remain primarily focused on R&D.” I hope to see a more detailed management update on design wins at the upcoming results. After all, Advantest ($6857.T) and Teradyne ($TER) are already shipping automatic testing stations for silicon photonics too.


The demand signals for Okamoto Machine Tool Works ($6125.T) are improving. Shin-Etsu Chemical ($6063.T) reported strong results today and is already talking about capacity expansion. Last quarter, leading wafer producers mainly focused on upgrading existing production lines.

The bottom is likely in for Okamoto Machine Tool Works ($6125.T). Capital spending on 300mm wafer manufacturing has already turned a corner: Okamoto posted a 370% YoY jump in wafer polisher orders last quarter, as SUMCO, Shin-Etsu, and GlobalWafers reported tight 300mm wafer capacity and planned production line upgrades. The company’s grinders for packaging applications have also stirred up interest, thanks to Mitsui’s commercial push in Taiwan.
I expect these two product families (wafer polishers and grinders) to power a strong earnings recovery starting this year. With demand stabilizing, the machine tool business should no longer depress margins after hitting its lowest profitability in 15 years. I believe Okamoto’s current valuation offers at least 50% upside. I bought a few thousand shares today.


$ANT Anthropic is making $ 250bn+ non-cancellable compute commitments with Google, Amazon, and Microsoft through 2033, and semis trade like we are about to drive off a cliff next year

$6492.T I already closed my position, but for those still involved, Okano has again raised this year's guidance. Additional inspection and decommissioning work at Shimane Unit 2, Fukushima Daiichi, and Kashiwazaki-Kariwa Unit 7 led to the positive earnings revision.

$6492.T I sold Okano Valve today for a 60% gain in six months. Thanks to @scg_oz astute comments, I revisited my valuation assumptions and realized they were too aggressive. I went through Okano’s numbers before the Fukushima disaster, made a few adjustments, and updated my earnings estimates. As a result, I now think Okano is worth around ¥17,000 per share instead of ¥22,000, when I implicitly assumed 9-10 reactors would be online by 2031. I believe 6-7 reactors is a more reasonable forecast today. I also don’t expect international expansion and next-generation reactors to move the needle soon, given regulatory hurdles. More inspection and restart work could create additional upside, but I wouldn't bet on it. Altogether, I think Okano is close to fair value today. Thanks everyone for the critical feedback, keep it coming!

$6135.T Makino was pitched today at the Sohn Tokyo Investment Conference. With Japanese machine tool exports at record levels, the company has strong momentum while its valuation remains reasonable. New orders and backlog are the key variables to watch in the upcoming results.

$6135.T In a March interview, Makino's sales executive said: “We’ve heard about Starlink-related components, so that might be a positive development for our company as well.” I checked, and he is right - SpaceX likely uses Makino's machines to make Starlink satellites.
SpaceX manufactures Starlink satellites at the dedicated facility in Redmond, Washington. GPT 5.5 helped me unearth local county permit records, which show new foundations for relocated machinery and related fire-alarm alterations in early 2025 under the project name "SPACEX SE03 - MAKINO EXPANSION AND HITL".
In addition, SpaceX is looking for experienced machinists for the Redmond facility to operate multi-axis CNC machines, including 5-axis mills and 6-axis lathes.
This convinced me that Elon is also a fan of Makino's gigantic "mother machines".


Tourists are getting liquidated while TSMC $TSM bulldozes ahead. Do investors really think this train will abruptly stop? The AI demand is strong, supply struggles to keep up, company fundamentals are solid, and semi valuations are attractive. End of story.

TrendForce analysts finally came across Santec $6777.T The “eye diagram measurements” instruments have nothing to do with the optical testing, though. They belong to Santec’s medical diagnostics business, MOVU, which competes with Carl Zeiss in the pre-cataract surgery market.

One of the main reasons I invested in Santec $6777.T was its highly lucrative medical business – MOVU. I generally understood where the optics are going, but couldn’t imagine the speed and scale of transition.
On the other hand, Santec’s success in the eye diagnostics market in partnership with Alcon $ALC was evident, but not everyone paid close attention. Two years ago, I thought investors failed to price in the upcoming launch of ARGONAUT – the new multi-modal eye imaging system that would supplement the ARGOS biometer. The irony is that the ARGONAUT is still awaiting FDA approval, while Santec’s share price took off without it. We might finally see the ARGONAUT later this year, though. On the recent earnings call, Alcon’s management indicated that Unity DX whole-eye analyzer (Alcon’s branded version of the ARGONAUT) is about to launch.
Considering Santec's rich valuation, I don’t think this will move the share price much when it happens, but it could still be a nice surprise.


$6777.T Santec will be added to the TOPIX at the end of October. This will be a material liquidity event, given Santec's free-float market cap is only ¥128bn. My napkin math shows that theoretical index demand should be around 15% of the company's float at today's prices.

$295310.KQ HVM is rushing to meet SpaceX orders with additional melting and forging capacity. KIS is also reporting that HVM completed material testing for gas turbines made by a domestic power equipment manufacturer. The producer in question is almost certainly Doosan Enerbility ($034020.KS), which is aggressively expanding gas turbine production in Korea and localizing the material supply chain. This revenue opportunity will likely be small for HVM in the near future, but it opens up new markets and reinforces the company’s manufacturing capabilities.


Sold Sphere ($347700.KQ) at a small profit to double down on HVM ($295310.KQ). HVM is rapidly expanding output of advanced metal alloys to support Starship production. Orders from SpaceX are rising faster than sales, boosting near-term visibility. Now all we need is daily Starship launches by August 2027, as Musk promised. Easy-peasy 👍

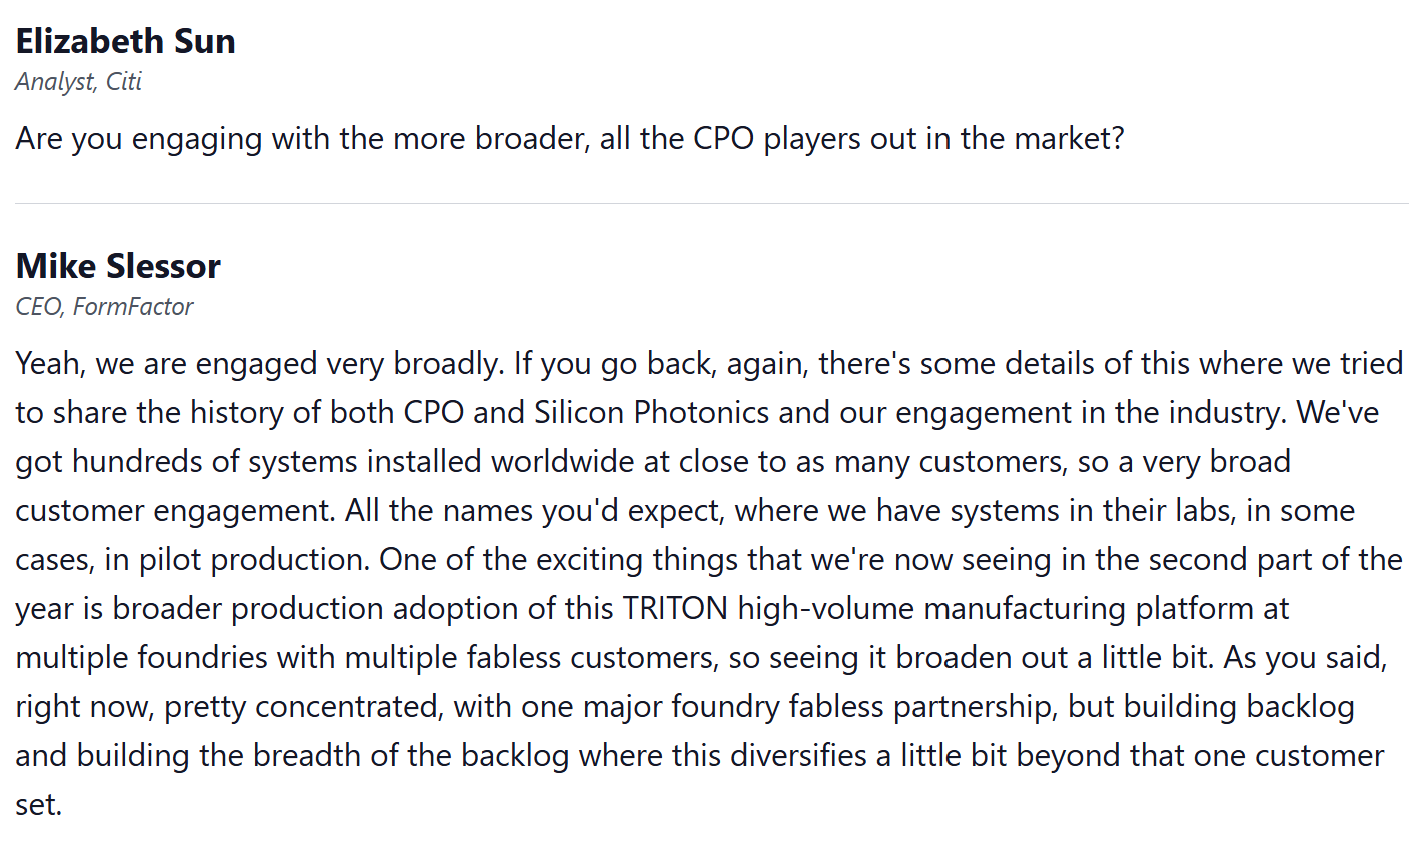
Are you sure about Advantest ($6857.T)? In the April earnings call, management said it received its first high-volume ATE order for silicon photonics (V93000-TRITON platform). Then in September, Advantest’s partner FormFactor discussed broader production adoption of the TRITON platform at multiple foundries. Finally, ficonTEC’s parent company, RoboTechnik, mentioned in the September prospects that it has shipped silicon photonics testing equipment to Customer Q, who “is a manufacturer of semiconductor automatic test equipment, headquartered in the United States. Shares of its parent company are listed on the Tokyo Stock Exchange.” I assume it is Advantest.




$4368.T FUSO Chemical trades at a discount to CMP slurry formulators (Fujifilm, Entegris, Qnity Electronics, Anji Microelectronics), even though its competitive advantage is arguably stronger and more durable. FUSO has effectively monopolized the ultra-high-purity colloidal silica market and has become a critical supplier to leading-edge chip production lines globally. Strong performance figures sustained over multiple quarters, recent silica price hikes, and investor outreach should improve the company’s perception over time.
$4368.T FUSO Chemical reported strong Q1 numbers across the board: revenue up 22%, operating profit up 32%, and net income up 115% (incl. government subsidies). This time, both the semiconductor materials and life sciences businesses contributed to earnings growth. Higher sales volumes of ultra-high-purity colloidal silica, price revisions announced earlier this year, and weak JPY were the key drivers. The life science business (food acids) finally began to recover with operating profit up 47%. The unchanged guidance implies a surprisingly weak Q2, which I think is too conservative. To meet overwhelming compute demand, chip foundries worldwide are ramping up wafer output and consuming increasing volumes of CMP slurries as they bring more production lines online. If anything, I expect an acceleration in FUSO’s silica sales over the next few quarters. Add to that 5-10% price hikes + moderating depreciation charges from the recently launched silica reactors, and you get 25%+ annual OP growth in the next three years. I think the company's valuation today leaves about 30-40% upside.

$6492.T I sold Okano Valve today for a 60% gain in six months. Thanks to @scg_oz astute comments, I revisited my valuation assumptions and realized they were too aggressive. I went through Okano’s numbers before the Fukushima disaster, made a few adjustments, and updated my earnings estimates. As a result, I now think Okano is worth around ¥17,000 per share instead of ¥22,000, when I implicitly assumed 9-10 reactors would be online by 2031. I believe 6-7 reactors is a more reasonable forecast today. I also don’t expect international expansion and next-generation reactors to move the needle soon, given regulatory hurdles. More inspection and restart work could create additional upside, but I wouldn't bet on it. Altogether, I think Okano is close to fair value today. Thanks everyone for the critical feedback, keep it coming!
I think Okano Valve Manufacturing (6492.JP) is an exceptional investment opportunity. It is the cleanest and cheapest way to invest in the nuclear renaissance I have found. I’m grateful to @JimJimmeny11 for the idea. Okano is a highly specialized manufacturer of high-temperature, high-pressure valves for nuclear and thermal power plants, with almost 50% of revenue from maintenance services. It holds a near-monopoly position in the Japanese market, protected by decades of operating experience and impassable qualification barriers. Okano is entering a multi-year earnings upcycle as Japanese utilities recommission reactors and replace aging valve infrastructure, driving revenue growth off a depressed base with significant operating leverage. I expect the recent disruptions to energy supply will break remaining political resistance to nuclear restarts and compress the launch timeline. Despite strong demand tailwinds, the firm’s valuation doesn’t price much growth. On my FY2026 numbers, P/E is 13, and EV/EBITDA is 8. Investors evidently do not consider international expansion or next-generation reactors as valuable options. Like Togami Electric Manufacturing (6643.JP), Okano’s risk/reward ratio is heavily skewed today, so I made a large investment last week under ¥10,000 without overthinking it.

