

I heard this is where all the cool kids hangout! ex JPM, BlackRock, and Macro L/S HF trader. #NFA
Joined October 2023
- Tweets4.8K
- Following350
- Followers6.2K
- Likes2.3K




Opulent Vocation retweeted
Jameis Winston can be a goofy bastard but he’s our GOOFY BASTARD! #nyGaints
Opulent Vocation retweeted
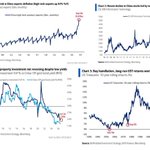
Thoughts from Michael Hartnett, BofA | "Those yields might not hurt yet, but diesel"
Markets may be underpricing a stagflation shock despite increasingly adverse macro signals:
•Diesel is a key warning signal: record refining spreads and sharply higher diesel prices could feed directly into transportation, agriculture, construction and ultimately consumer prices. A decisive breakdown in transportation stocks below their 200-day moving average could confirm an emerging "autumn stagflation event."
•Markets remain unusually complacent: long-term Treasury yields are elevated and commodities are surging, yet risk assets show little panic, creating conditions for significantly higher volatility if markets begin testing policymakers' resolve.
•Capital flows are becoming more defensive: bonds and cash are attracting substantial inflows, while US equities recently recorded their largest three-week outflow since January 2026.
•Bonds may be losing some of their diversification benefit: stock and bond returns have become positively correlated again, potentially requiring higher yields before investors substantially increase bond allocations.
•Quality/FCF stocks look relatively attractive: companies producing strong free cash flow without excessive leverage have historically outperformed other major equity factors and have also proved comparatively resilient during stagflation.
•AI represents another potential vulnerability: despite roughly $1.5tn of AI-related investment over the past three years, there is still limited evidence of broad economy-wide productivity gains. With S&P 500 free-cash-flow yields at very low levels, disappointment over AI returns could expose stretched valuations.
High energy costs + elevated bond yields + market complacency + weak productivity create a potentially dangerous macro setup. A significant deterioration in transportation stocks could be the confirmation that the summer risk-on environment is transitioning into an autumn stagflation regime.


Opulent Vocation retweeted
Hormuz and Bab el-Mandeb are choked. Saudi crude has one door left, and it's in Egypt.
Three things to note:
1.) Suez Canal is getting busier. MarineTraffic counted 256 crossings in the week of Sept 7–13, up 3.2% from the week before.
2.) Saudi oil is part of the reason. Lloyd's List reports that tanker, bulk, container and vehicle-carrier traffic is all up year-on-year, and Saudi traffic being rerouted north is adding to the gains.
3.) It's also making voyages less efficient. Cargoes from Yanbu that used to go south through the Red Sea are now more often sent north via Suez. Tankers load partly at Yanbu and top up at Sidi Kerir, which makes trips longer and ties up ships.

Opulent Vocation retweeted
The 3.4% estimate Headline CPI next week.........yeaaaaaa okay.. Accompanied by 2.4% Core CPI 🤣

Opulent Vocation retweeted
You need to understand that the cause of the current inflationary environment is completely out of Kevin Warsh’s hands…. It’s in the War Rooms hands. This is a energy inflation dynamic
Opulent Vocation retweeted
FOMC this, FOMC That, Kevin Warsh this... blah blah blah..... Crude is all that matters, and right now we're still above the Landman's $60 - $90 range. Everything on the far end of the equity risk curve will get punished if we continue trading above this range. The AI trade is heavily dependent on energy and cheap financing. With Crude at these levels, companies running with AI momentum are handicapped. Hopefully I saved you all hours of Substack reads

Opulent Vocation retweeted
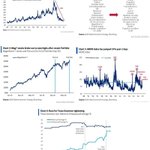
Thoughts from Michael Hartnett, BofA | The Biggest Mag7 Surprise That Could Spark A Full-Blown Market Crash
Investor positioning has become extremely bullish, creating the conditions for a sharp correction if expectations are disappointed.
Key points:
•BofA’s Bull & Bear Indicator is at 9.6/10, an extreme level that has historically signaled excessive optimism.
•Investors are overwhelmingly betting on a “goldilocks” scenario: -> no U.S. recession (“no landing”), -> no Fed rate hikes, -> no cuts to AI hyperscaler capex, -> continued AI-driven earnings growth.
•Record amounts of money have flowed into technology and semiconductor ETFs, suggesting crowded positioning.
Contrarian positioning is:
•long-duration government bonds,
•defensive sectors,
•high-dividend stocks,
•long U.S. dollar,
•underweight or short cyclicals (banks, industrials) if sentiment reverses.
The biggest risk
•the Magnificent 7 (Mag 7) remain the key trigger for the broader market.
•if the Mag 7 continue making new highs (the MAGS ETF above roughly $70), the bull market likely continues.
•if they weaken significantly (MAGS below about $65), it could trigger broad selling across banks, industrials and the wider market.
AI spending is reaching unprecedented levels. If hyperscalers eventually reduce AI capex, market expectations could be reset sharply. However, an even bigger surprise would be if AI capex remains high but the Mag 7 still fail to make new highs, suggesting investors are no longer rewarding the spending. That could undermine confidence across the
Markets are highly vulnerable because positioning is extremely one-sided. Any disappointment - Fed policy, inflation, AI spending, or weakness in the Mag 7 - could trigger a large market correction, potentially even a broader crash if selling spreads beyond technology.


Opulent Vocation retweeted
The market is shy of ATH already pricing in a weaker CPI tomorrow due to the 20% drop in crude so we can get a little rally in equities but most likely it will retrace if crude keeps rallying towards over $90 because that brings inflation back on the table. Trade wisely tomorrow ✌🏽
Opulent Vocation retweeted
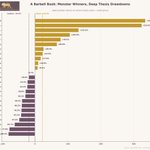
This conflict in the Strait of Hormuz will be on and off for the next 24 months and Crude will trade at the Landman’s sweet range of $60-$90 where the Saudi’s and American oil companies profit the most. Equity markets will adjust but 6x Baggers will be very hard to find
Opulent Vocation retweeted
The AI capex boom and consumption fueled by wealth effects and big tax refunds have, on balance, more than offset the drag from the Iran war and higher energy prices. Inflation spiked, but it looks like a peak, not a regime change like we mentioned in our article last week:

Opulent Vocation retweeted
Soggy Economy, Sizzling Profits
Step back from markets, and the economy itself is a study in divergence: a cyclical core that’s merely “okay,” wrapped around exceptional corporate fundamentals.
Growth is reaccelerating into mid-year. We’d frame the path as a jump from roughly 1.1% real GDP growth around the turn of the year to about 3% in the second and third quarters, before settling back near 1.5% late in the year. The engine is AI investment plus spending by upper-income households sitting on four years of wealth gains; the drag is government cutbacks and weak demographics. That same demographic squeeze shows up in jobs: hiring has improved (unemployment back down to 4.3%), but with immigration falling and the working-age population shrinking, future gains will be modest and growth will increasingly come from productivity, not headcount. To add, white-collar jobs have been negative in the past 18 months due to AI!!!
Crucially for the inflation debate, a tight labor market isn’t producing hot wages, earnings growth has cooled to around 3.4%. Pair moderate wages with solid productivity, and the risk of sticky inflation drops sharply. May’s 4.2% CPI was a three-year high, but it’s an energy story, and it looks like a peak: gasoline has rolled over, the Strait of Hormuz has an interim reopening deal, tariffs have already fallen (from 11% of imports to 7.3% after the Supreme Court struck the IEEPA tariffs), and shelter fully a third of the CPI is cooling, with new-lease rents up just 1.7% and rental vacancy at its highest since 2017.
Now the part investors should not miss, the K-shape.
In the first quarter, the after-tax corporate profit share of GDP hit 14%, double the ~7% it averaged in the 1990s, while labor’s share of national income slipped to about 61% from 66%. That split has been a gift to investors and is likely to persist in the short run; the catch is that it poses a political risk as the gap between corporate and household fortunes widens.
That leaves the Warsh-led Fed boxed in: essentially at its employment goal (4.3% unemployment) but badly overshooting on inflation (PCE near 4%). Futures have flipped from easing to pricing a possible hike, but we doubt they’ll pull that trigger to fight an inflation problem that’s likely fading anyway, especially while facing the most acute threat to Fed independence in the central bank’s history.

Opulent Vocation retweeted
Getting Paid to Wait: Bonds Are Priced for Inflation
For the first time in a while, the bond market is doing the bulls a favor by bracing for the worst. Yields sit near their highs of the year, and the front end has violently repriced — from pricing three rate cuts in 2026 to pricing a possible hike, with short-end yields up roughly 70 basis points year-to-date.
The whole curve has lifted since year-end, and the key tell is at the front: the two-year now yields about 60 basis points more than the federal funds rate a clear, paid incentive to step out of cash-like instruments. If headline inflation peaked in May, as we expect, the market will price those hikes back out, and today’s front-end yields will look like a gift.
The bigger point is that the income is back in fixed income. All-in yields range from around 5% in investment-grade and securitized debt to roughly 6% tax equivalent in municipals and 7% in high-yield and corporate. Household and municipal balance sheets are in good shape, even if the federal one isn’t. The long end stays jittery (fiscal worries into the midterms), so the value is in the belly and front, not the bond market’s tail.
One nuance worth flagging: AI is creeping into the bond side of portfolios, too. The technology weighting of the investment-grade index has risen roughly five-fold since 2006. That actually lifts index quality hyperscaler net debt to EBITDA is about 0.3x versus the 2.6x IG average but it does quietly concentrate the same theme that dominates the equity book.

Opulent Vocation retweeted
The U.S. Dollar, where everything in global markets ultimately rests, continues to debase the “being dethroned” narrative. Today we’re highlighting the dollar’s dominance, but most importantly, the dollar's recent surge is a two-month headwind for US stocks, until it stabilizes.

Opulent Vocation retweeted
The Inflation scare is an Oil Scare. Core CPI has barely budged while headline CPI’s rise was an oil shock jump. The SpearPoint team thinks we’re at peak on the Headline front with crude down over 20%. This will fade the narrative of Fed Warsh’s rate hikes

Opulent Vocation retweeted
Thoughts fom Michael Hartnett, Bofa | Stock Bubbles Are Always Ended By Voters And Vigilantes
"V for Victory, Votes & Vigilantes": the biggest tech bubble since 2021 needs the last two to burst. With Iran "done," the US is pivoting back to boom-and-bubble to win the US-China AI war. But the setup is increasingly fragile.
Victory - the bubble is at its ceiling
AI is now 39% of the S&P 500 - right at the historical limit of market concentration ex-railroads. For context: railroads peaked at 63%, Japan at 44%, the dot-com TMT trade at 41%, the Nifty Fifty at 40%. We are at the top of that range. And concentration is not rotation: in the final 6 months of the 1999-2000 bubble, only tech/telco stayed positive.
The flows tell the story
- US stocks: record $119.2bn weekly inflow, annualizing a record $739bn for 2026
- Tech: record $19.2bn inflow ($154bn annualized)
- US mid cap: record $19.9bn | small cap: $12.3bn (2nd-largest ever)
- Meanwhile Europe (-$1.2bn, 10th outflow) and China (-$9.1bn, 12th) keep bleeding
The BofA Bull & Bear Indicator climbed to 9.2 from 8.9 - deeper into Sell territory, with the "extreme bull" sell signal triggered in May. Across 17 such signals since 2002: average 2-3% loss over the following 2-3 months, ~60% hit ratio, max drawdowns of 15-20%. So far, the market is unbothered.
Votes & Vigilantes - where it breaks
Trump approval sits at 41% (presidential), 35% (economy), 28% (inflation), even as US household equity wealth is up $6tn YTD. Reminder: booms and bubbles are ended by voters and vigilantes. A GOP Senate loss in November would be a classic "dollar down, yields down, stocks down" event. And since the Warsh Fed pick, the 2s10s curve has bear-flattened from 75bps to 25bps on "inflation = hikes" fear - with the move from inflation boom to stagflation bust now looking almost certain.
The bottom line: euphoric flows, peak concentration, a flashing sell signal — and a market that, for now, refuses to care.


Opulent Vocation retweeted
Start with the macro, because it drives everything that follows.
Our base case is that the next leg of this cycle is defined by fiscal loosening and a more accommodative policy mix that expands liquidity and lifts risk appetite across the equity complex. When that backdrop arrives, it doesn’t lift all stocks equally. It lifts the long-duration end of the market hardest: the companies whose value sits furthest out in the future, the ones most sensitive to discount rates, liquidity, and the willingness to underwrite growth. Easier policy is rocket fuel for exactly that cohort.
So the question I want to answer for you isn’t “is my book cheap?” It’s “how much of my book is leveraged to the tailwind we expect?” And there’s a clean framework for measuring precisely that.

Opulent Vocation retweeted
This low volume environment in futures is misleading. I see ES giving back 30-40bps of this rally
Opulent Vocation retweeted
Trump just pushed the ending of the War by another 3 weeks (after constantly saying just a few days..) 🤫

Opulent Vocation retweeted
The impacts of the Iranian War are already being felt across the United States with higher gas, produce, and meat prices.
Inflation is coming, and it's coming hot. The operation in the Middle East will take longer than 12 months, and you'll have to adjust your portfolio to withstand a pick-up in inflation. Great charts Apollo highlight the price of goods rapidly increasing in countries around the world.


