
P14 Capital uncovers undervalued opportunities in SMID-cap equities. Long-biased and generalist. Not investment advice. Free research below:
Joined January 2025
- Tweets2.1K
- Following249
- Followers1.5K
- Likes983


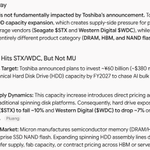
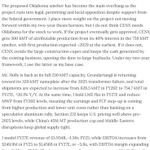
So in simple words, everyone has a common enemy - MEMORY: $MU, $SKHY. Tick-tock the supply clock is coming for you

I think Intel badly underestimated how quickly higher memory prices would hit PC demand and trigger an inventory correction.
Those risks were already visible by the Q2 earnings call. Management acknowledged them, but still expected client revenue to hold roughly flat in Q3, supported by CPU inventory replenishment. That assumption now looks too optimistic. They should have set more conservative expectations for the client business.
Still, Lip-Bu did make some encouraging comments.
“We expect the industry to remain supply constrained throughout 2027 and into 2028.”
“We now expect industry server CPU units to grow more than 30% in both 2026 and 2027.”
“Growth would be higher in both years if additional industry supply were available.”
Maybe if you stop buying the dip it'll stop dipping. $QQQ we are still nowhere close to capitulation btw.
Pretty solid by $RKT. Very resilient performance in comparison to peers who are cratering. Don't read too much into AH performance

$RKT 𝐑𝐨𝐜𝐤𝐞𝐭 𝐂𝐨𝐦𝐩𝐚𝐧𝐢𝐞𝐬 𝐐𝟑 𝟐𝟎𝟐𝟔: 𝐑𝐞𝐯𝐞𝐧𝐮𝐞 𝐒𝐮𝐫𝐠𝐞𝐬 𝟗𝟒%, 𝐑𝐞𝐭𝐮𝐫𝐧𝐬 𝐭𝐨 𝐏𝐫𝐨𝐟𝐢𝐭𝐚𝐛𝐢𝐥𝐢𝐭𝐲, 𝐁𝐮𝐭 𝐐𝟒 𝐎𝐮𝐭𝐥𝐨𝐨𝐤 𝐒𝐨𝐟𝐭𝐞𝐧𝐬
⠀
📊 𝐑𝐞𝐬𝐮𝐥𝐭𝐬
• Revenue: $3.28B (+94% YoY)
• Adjusted Revenue: $2.57B (+37% YoY)
• GAAP EPS: $0.25 vs. -$0.06 YoY
• Adjusted EPS: $0.15 vs. $0.07 YoY
• GAAP Net Income: $709M vs. -$124M YoY
• Adjusted Net Income: $419M vs. $158M YoY
• Adjusted EBITDA: $748M vs. $349M YoY
⠀
🎯 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞 (𝐐𝟒 𝟐𝟎𝟐𝟔)
• Adjusted Revenue: $2.1B–$2.3B vs. $2.57B in Q3
⠀
📌 𝐊𝐞𝐲 𝐓𝐚𝐤𝐞𝐚𝐰𝐚𝐲𝐬
• Closed mortgage originations reached $43.6B, with a 2.54% gain-on-sale margin
• Mortgage servicing portfolio reached $2.0T across 9.1M loans
• Mortgage segment adjusted revenue rose to $2.09B from $1.41B YoY
• Mortgage segment contribution margin more than doubled to $1.14B
• Redfin purchase mortgage clicks +50% YoY; refinance leads more than doubled
• AI voice platform handled 65% of inbound servicing calls, resolving more than half autonomously
• Digital mortgage applications accounted for over 40% of retail refinance applications
• MSR sales generated $379M in cash proceeds
• Total liquidity: $11.4B, including $2.7B cash
⠀
💬 𝐌𝐚𝐧𝐚𝐠𝐞𝐦𝐞𝐧𝐭 𝐂𝐨𝐦𝐦𝐞𝐧𝐭𝐚𝐫𝐲
“We didn't spend the last three years waiting for rates to fall. We acquired distribution, connected real estate and mortgage, and invested heavily in technology. We changed the economics of our business. Rates went up. We took share. Profits grew. That's not a coincidence.” — CEO Varun Krishna
$RKT looks super good with a break thru 12 pre-earnings


$PLTR putting back my short on tomorrow. This stock is a recipe for disaster for the next 2 weeks or so. This will also be my first SHORT writeup
AI hardware is just a tired trade at this point. The rate of change is clearly decelerating in capex growth. $ORCL has been pushed by the market to make a statement on this. No reason why hypers won't do the same. More overhangs than catalysts at this point

The timing of this piece was extremely off. Nothing has changed fundamentally about my top pick $FSLR. I truly think this can bid into midterms. More importantly I think Q3 will display a strong acceleration in orders. I am long 180Cs Nov at $5.00 (now at $8.00). I think a dip into FOMC tomorrow should be gobbled up. NFA.


$FSLR nothing has really changed about the thesis. The timing of this comment was obviously off (lol) but I truly think this can bid into midterms. More importantly I think Q3 will display a strong acceleration in orders. Seeing several bids on 175-185 calls 10/30 expiry.
Brazil is probably a buy after the dust settles in a few weeks or so. Its funny how participants see conservatives as saviors for financial markets. The effects are quite often short-lived and revert faster than expected. Its never that deep. $EWZ