

A community where pros & traders of all levels team up with one common goal of crushing the markets. Focused, noise-free collaboration. NO BS ALLOWED
Everywhere
Joined July 2021
- Tweets2.5K
- Following113
- Followers4K
- Likes2.6K




Desk summary: McElligott, Repricing the Left-Tail...Fast (22 Oct, 11:15am)
Vol regime flip
Equity vol, skew and vVol jumping on outright hedge buying after weeks of being ignored.
Spot is accelerating through the MegaCap Tech / Nasdaq negative-gamma flip (QQQ ~$715), so dealer hedging now adds to moves.
Spot/vol correlation has flipped back to negative: spot down, vol up.
Prints: SPX Jan 5900P paid 18.3 on 1.3k; VIX Nov 25C 0.85 bid on 18,150; Dec 7400P paper buys 2k at $84.50.
Rates working as the hedge again
USD rate vol bid into the duration rally, UST yields at fresh 1-month lows.
Big bullish futures and vol buying in 5s and 10s (FVH 106C 15k and 20k, TYZ 107C/107.5C, TY wk5 strangles 20k). Front-end vol up most (1m x 2y +11.2).
Short-term bond/stock correlation reversing, so USTs hedge risk assets again.
Why: the AI trajectory rethink
Both YTD leaders are getting hit together: Tech -2.9%, Energy -1.7%. That's the Semis/Energy barbell (+60% YTD, 3 Sharpe) being de-risked.
Catalysts: the Anthropic ARR disappointment and IPO-viability questions, Gartner on CoreWeave and neoclouds, weak AI-ecosystem IPOs, LRCX guide, and a broad sense that capex is flattening versus lofty estimates. That's despite META staying full tilt on capex, and META's big equity secondary shows hyperscalers are in effect selling calls on themselves.
AI financing costs are turning non-linear as credit spreads widen, with lots more debt, loans and equity issuance coming.
Macro read
Earlier this week he called the UST squeeze a positioning and PnL-monetization move, not yet a growth scare.
Now he says the market is clearly repricing the left side of the 2027+ US growth distribution, because the AI-capex trickle-down that kept nominal GDP running at 6–10% is in doubt.
Desk takeaway
Below QQQ ~715 expect bigger moves with vol bid. Hedges and duration are working, and AI infrastructure and neocloud names are the epicenter. Size longs in semis, energy and neoclouds accordingly.


This week on the floor: LRCX 4X swing, META verticals, SPX puts 2.7 to 14, TSLA 8X call out
Four process trades: a semis swing that went 3X then 4X, a META call setup managed into a vertical, a fast SPX put trade, and TSLA cheapies taken all the way to 8X.
Four names carried the desk this week across semis, mega-cap tech, the index, and EVs. The habit stayed the same: have a reason, size it, and take profits on the way up.
*$LRCX — the swing that kept paying*
Joeeydee opened Tuesday's session with *this lrcx looks the one*. Minutes later highyield6 had *LRCX 300s are 3X*, and harvey marked the level: *LRCX thru 327 can see 335*. By Thursday morning the swing was still working: *4X on LRCX swing OCT 300s*.
*Member takeaway:* a swing with room to run pays best when you know the levels and let it work.
*$META — support, size, then a vertical*
Research's morning GEX walls put META at *750 call / 715 put*. In the afternoon Dershil called *META bidding*, then *Added META 730C and 750C for tomorrow binary size*, noting *support at 717 and the 10dsma + looks like their competition rushed to market*. He *Averaged up META* and *Added NW Meta 800C 2.8*.
Into the close he managed it: *down to 1/3rd META 730C little over 2x, short 760C against the 750C leg for a vertical spread 0.38 cost basis, Holding 3/4ths 800C oct 9th*. The day ended with *META rippperrrrr*.
*Member takeaway:* a level plus a catalyst got the trade on. Trimming at 2x and turning a leg into a vertical kept the risk in check.
*$SPX — in, 2X trim, 4X, done in 23 minutes*
Friday at 11:02 AM highyield6 posted *i added spx puts*. At 11:09 he had *SOLD 80% the SPX puts at 2X*. By 11:21 it was *SPX puts 4X*, and at 11:25 the recap was *spx went 2.7 to 14*.
*Member takeaway:* selling most of the position at 2X locked in the win, and the runner did the rest.
*$TSLA — relative strength, cheapies, 8X out*
highyield6 flagged *tsla in play* at the open and *tsla RS all day* by late morning. In the afternoon Dershil *Filled some tsla 372.5c cheapies .25*. Into the close he posted *TSLA 5x*, then *All out tsla 372.5 8x*.
*Member takeaway:* a cheap entry on a name showing strength all day, and a clean full exit.
That's the Power Trading Room loop again: marked levels, sized entries, and exits taken into strength. More from the floor next week.

Desk — Citadel Rubner GMI: 2H September Getting Closer (18 Sep)
Frame: Roadshow AI sentiment flipped sharply negative. Sep weakness not done — path into month-end still lower. But positioning/sentiment cleaned up fast → use further weakness to add core longs; full Q4 playbook coming.
Under the hood: SPX −1.8% MTD / −3.2% from Aug 13 high understates damage — 9/11 sectors lower MTD; only Energy + Comm Svcs up. Concentration (top 10 ~40%) cushioned the index. Rotational, not disorderly.
Vol: Index hedges finally bid — SPX 1m skew 62nd %-ile (from ~5th at Sep start); NDX 70th; RUT 83rd. Sector skew still cheap (Tech 40th). Spec upside cooled (call IV>ATM 60%→45%; fully inverted skew 24%→13%). VIXEQ/VIX normalizing — less single-name leverage than July.
Retail: Disengaged not liquidated — semis retail gross −46% vs Jun peak; still net better-to-buy semis on call/put direction.
Into month-end supply > demand:
Vol-target still ~86% exposure (high since Mar); CTAs still long (z +2.4→+1.1) — room to sell.
Q3 SPX +1% / bonds −2.2% → pension sell-eq/buy-FI potential; plans ~112% funded.
Triple witching Fri: ~$7T US equity options (~25% of total) expires.
Buybacks blackout: 10% weight today → 61% by Sep 30; majority closed until Nov 1.
Seasonality: Midterm years historically −~1.1% from here to Sep 30, then +5.6% Sep 30→YE.
After Sep: Tech/AI excess (semis vol round-trip, lev semis AUM ~½ Jun peak, equip/infra −30–55%) + conversation euphoria→fear. Oct+: seasonality, buybacks reopen Nov, cleaner positioning, retail seasonality, Q3 earnings (Q2 ~33% EPS growth).
Bottom line: Cautious through Sep; constructive Oct/Q4. Add on weakness.
Nomura McElligott — THE STRAW THAT STIRS THE DRINK (15 Sep 7:14am ET) Desk Note
• Crude = straw that stirs the drink — bonds/stocks/gold/credit/crypto bleeding overnight; hiding places: USD, energy eq, commodity carry, rates trend, long vol
• Energy/petrochem shock 2.0: shortages increasingly “terminal”; China now rebuilding crude inventories (not emptying) with Iran to squeeze US/EU
• World short energy / refineries / VLCCs; Trump diesel tweets; CBs only have demand-side hikes vs supply shock
• Patient zero: EU diesel cracks dragging EUR swaption vol toward early Iran-war highs
• Neg convexity: high-strike payers, CMT range accruals → skew/vol-of-vol; VIX call buying (125k Nov 31 @$0.94, 126k Nov 34 @$0.89, 128k Oct 28 @$0.92) = energy pocket if risks accelerate
• Needs energy extremes first (hypothetical US energy export ban left-tail) → rate vol → asset beta; without that, AI slowdown dismissive as now-catalyst
• Dario/Sam/Elon weekend = regulatory capture / TBTF; POTUS “whoever wins AI wins”
“ Success is no accident, it is hard work, perseverance, learning, studying, sacrifice and most of all, love of what you are doing or learning to do”
-Pele
Another great week in the books!
Some highlights from callouts in room:
🔥DOCN common 20pts hy6
🔥DOCN calls up to 800% hy6 miracle
🔥IWM puts 400%
🔥AAPL multiple layers 400-600% TJ
🔥AAPL calls 300% Binman
🔥SPCX odte 4X TJ

This is how the room works.
--Weekend: our research seat posted the full GS Communacopia speaking schedule. DigitalOcean ($DOCN) was on the Tuesday open slot.
--Monday: HY6 and the floor marked DOCN as a name to watch into the agentic/AI infra tape.
--Tuesday: calls and commons were added by members and some added on before they spoke.
--Automated desk reminder at presentation time. Stock ripped — calls went 400%+ in the room .... Not a tip service.
--A process: calendar → research → call → timing → execution. Want in? thepowertradingroom.com

$IWM worst down day in almost 2 months. Some went home w IWM 294 puts yesterday and long AI 🤷🏻. These went +400%

Desk summary — Nomura McElligott Cross-Asset (9 Sep)
Sales note — not Nomura Research
Tape / macro
Modest risk indigestion after US strikes on Iranian oil tankers → oil up, rates higher, curves bear-flattening
Theme of the past week: back to High Sharpe & Trend — nascent re-acceleration after sputtering
Strong 1w contributors: “New 60/40” Long Semis / AI Energy, 50% CTA Trend / 50% Equities, AI Enablers vs Hyperscalers
CAM Daily Trend: positive PNL from Rates (CTA Short G10 Bonds ~2%ile, STIRs ~3%ile) + EMFX (Short Dollar ~8%ile); Equities modest pullback on chop — contrarian flag: crowding risk in bond shorts / USD shorts
Equities / positioning
Prior narrative for soft tape: Sep seasonality / midterm drawdown analogs, rates oversupply, hawkish CB impulse off commodities + Iran/SoH; GS PB Eq HF Net 2%ile / Gross 27%ile (1Y)
Nets looked to bottom Thu into +1.1% SPX — forced some add-back
Friday + post Labor Day lean into concentrated AI names unwound in summer: ~$1.1B $delta / $5.8mm $vega call buying in total options premium cited
AI / Tech vol buyer back (feeds Spot Up / Vol Up + dispersion / short corr)
Need more skew steepening before large hedge thesis; CTA Trend churn in sideways equities → local proximity to futures deleveraging triggers = synthetic negative gamma into weakness
Desk summary — GS Coppersmith - US Equities AI back in focus Astra Communacopia 6 Sep 2026
Lee Coppersmith | GS FICC & Equities
Bottom line
AI/Astra + Communacopia matter more for stocks near-term than the inflation print. Light positioning, semis vol crushed, flat skew → prefers right-tail option expressions; hedge via SPX ex-AI (SPXXAI) downside / long Broad AI (GSTMTAIP) vs short SPXXAI.
Setup
OpenAI Astra + Communacopia + micro updates; SPX 1w straddle ~1%
Communacopia kicks Tue 9:30am PT with OpenAI; 40 cos; AI spend/returns/competition into 2027+; GS still sees compute demand > supply into 2028
Macro / RAI
Further risk appetite needs lower rates more than stronger growth — growth PC near post-COVID highs, monetary PC still negative
Goldilocks path: lower energy + Hormuz reopen + US inflation progress; less room for growth misses / geo shocks
Earnings / vals / positioning
YTD EPS strength Tech/AI-capex led; investors less willing to pay up for cyclical AI earnings as leverage rises; higher long-end hits non-Tech multiples
Strategy: lower equity Sharpes ahead, unless lower rates + resilient growth
US fund L/S: gross 208.5 (27th %ile 1y), net 48.4 (4th %ile) — light vs 2m ago
VXSMH semis IV ~65 → 36 since July; put-call skew on avg SPX stock still flat near 3y lows
Tech L/S Momentum pair ~−50% from late-June highs (even after Fri ~+7% bounce)
Micro / flows
MU, SNDK, EWY, DRAM starting to break above summer downtrends
Korea: last 4w equity flows supported by buybacks despite net selling elsewhere
Other
Brazil: RSI 76; ~7% more to Apr highs ~200k; Flávio Bolsonaro 45% vs Lula 44% runoff (PoderData/Aya)
Desk read
Own upside convexity into Communacopia/Astra week; hedge rotation risk in ex-AI. Light books + crushed AI/semi vol = asymmetric setup if catalysts land.

What a week. Too many wins to post, here’s just a few callouts from yesterday and today to highlight an incredible week of great teamwork:
🔥CBRS 195C 1.45 to 19! 1300% hy6
🔥MU Calls 600% Dersh
🔥BE calls 500-800% -miracle hy6
🔥HOOD 920% -John
🔥CRCL calls 400%+ -bin
Nomura / McElligott — “TAIL / DOG” (Sep 1, 11:25am). Sales note, not research.
McE: Eq vol collapse has gone “epic.” IWM 3m ATM iVol at 0.2%ile. Dealers/MMs choking on PnL. Long optionality + long skew bled out. Hedge demand dead (clients de-grossed). Skew at 2%ile. If the rates grind accelerates, dealers are short a mountain of high-strike payers. Negative convexity setup.
Thread
1/ McElligott TAIL/DOG (1 Sep):
Eq vol capitulation is “epic.” Yesterday looked like outright stop-outs. IWM 3m ATM iVol at the 0.2%ile. Options MMs and dealers choking on losses. Anyone long optionality / long skew has been bled dry. Expect headlines on crystallized trading losses.
2/ The tape is weird.
Index vol Z-scores smashed lower over the past 2 weeks even with spot down.
VIX 1m beta to SPX (inverted): 4%ile
VIX 1m correl to SPX (inverted): 2%ile
August: ~2x realized vol on rally days vs down days (SPX 97%ile since 1986).
3/ Why no one is hedging:
Clients are netted-down and de-grossed. Not enough beta on the books to need real downside.
SPX 3m skew and put skew both back at the 2%ile.
“Who needs to hedge if you don’t have nets / gross?”
4/ Why vol keeps getting supplied:
Structured notes / exotics dumping limitless vega (and feeding dealers vanna + skew)
The big 1Y Tech/AI vol buyer is publicly “gone” — those positions flipped from demand to supply
Retail + lev ETF speculative flow dried up after the July momo unwind. The negative-gamma accelerant is absent
Dispersion PnL cratered to the 5%ile → QIS-type books getting derisked
5/ Rates rhyme with equities.
Massive demand for intermediate high-strike payers (plus CMT range-accrual notes) has payer skew rich and vol-of-vol “bonkers.”
But swaption vol itself isn’t exploding — because the rates move is just a slow grind on low realized. Same story as stocks.
6/ The actual tail:
If that rates grind accelerates, dealers are short metric tons of those high strikes. Hard to find willing wing sellers to cover until the payers get monetized.
That’s the negative-convexity setup he’s flagging. Vol is cheap. Positioning is one-way. Amplification risk is the point.
Rubner / Citadel Securities — “September Setup: The Asymmetry Has Changed” (Aug 31).
Same Rubner you’ve been tracking. Core line: still constructive longer-term, near-term R/R flipped. Don’t chase into the event window; use strength to cut and buy cheap puts.
What already happened
• SPX +~22% / ~$12tn off the Mar 30 low.
• Q2 EPS ~+33% y/y — strongest outside post-recession. 88% beats, median +7%; steepest estimate revisions since at least 2000. That tailwind is behind you.
• Vol crushed after the July reset: VIX 14.4 (2nd-lowest since Dec ’25). SOX 1m ATM vol 46, –40% from peak in ~30 sessions. SPX skew 1st %ile of the past year. VVIX 1st %ile since Jan ’25. RUT IV at 5-year lows. 1m 25d puts cheapest since Dec ’24.
Flows that carried August — fading
• Retail: still net buyers (net notional 65th %ile) but gross participation 35th %ile. September is the worst month in his 2017–25 sample for retail net and for buying SPX down days (half the all-month average).
• Buybacks: >$1.1tn authorizations, 67% outside Tech. Window shrinks hard — blackouts accelerate ~Sep 12.
• Systematics: CTA / vol-control / risk-parity already rebuilt SPX and RTY. No spare dry powder like July.
• Lev ETFs: AUM –$70bn / –31% from June peak; Tech –38%, Semis –50%. The squeeze fuel is gone.
• Pensions: Milliman 100 funded 112%, highest since 2001 → Q-end de-risk / immunize = mechanical equity sell, duration buy.
• MF: September weakest month for equity purchases since 1984 (median 1.79% of AUM).
The September mechanical
• $9.6tn US options expire by Sep 18 (35% of total). $6.2tn on the 18th alone (23%) — could top June’s $7.7tn record. That’s the fade of dealer long-gamma support into OPEX / FOMC week.
• Calendar from here: NFP Sep 4, PPI 10, CPI 11, FOMC 16, plus that expiry. Two-sided, less obvious right tail.
• Seasonality: September weakest month since 1928 (SPX down 55% of years, avg –1.1%, typical drawdown –4.7%). Back half avg –0.91% — worst two-week stretch of the year. Midterm Septembers worse: avg –1.5%, drawdown –6.2%, then October repair into Election Day.
Desk translation
This rhymes with the BofA seasonality note and McElligott “spot-up/vol-up is over” tape: vol already wrung out, CTA long, buybacks going dark, OPEX + FOMC + CPI stacked in the same two weeks.
Trade: not a structural short. Rubner’s explicit expression is sell strength / add inexpensive 25d protection rather than chase. Small-cap, financials, regional banks, consumer — IV still cheap if you want event convexity. Watch Sep 12 buyback blackout, Sep 16 FOMC, Sep 18 $6.2tn expiry. Mid-Oct is where he wants to get long again if September does the seasonal work.
Same setup we flagged on the conference calendar: next week is CEO color, the week after is the actual vol event.
BofA Systematic Flows Monitor
28 August 2026
Headline
Stretched Treasury shorts + elevated equity longs = CTAs made money this week. Hawkish Jackson Hole (Warsh) kept the rates short intact and pushed cover levels further away.
Rates / FX
• UST futures still stretched short. Front-end sell-off after Warsh flattened the curve and moved short-cover triggers out, especially at the front end.
• Next move for CTAs in bonds is more vol-driven resize than an imminent cover.
• FX: USD firmed on Warsh, but trend signals next week lean dollar-selling vs EUR, GBP, AUD, CAD. Opposite vs JPY — CTAs could buy USD/JPY after three down weeks in the yen.
Equities
• CTA equity longs still elevated after a catalyst-heavy week.
• NVDA earnings supported large caps / NDX; hawkish Warsh hit RTY (–1.4%).
• Slow CTAs: positioning particularly extended (already long).
• Fast CTAs: can still add SPX, NDX, Nikkei on flat-to-up paths.
• RTY is the weak link: –1.4% left the index only ~1.4% above the nearest stop. Closest index to a trend-driven unwind.
Gold
• Sold >3% Friday on Warsh, but still above the 12m MA — trend not broken.
• Medium/long CTAs still short; fast CTAs on the sidelines. Model does not yet show CTA buying. Fresh long buying needs another push higher.
SPX options / gamma
• Realized vol stayed subdued into Jackson Hole.
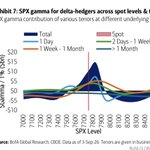
• SPX hedger gamma 83rd %ile, finishing 28-Aug at $8.4bn.
• ~$3.1bn of gamma expired Friday.
• Into Labor Day week: hedgers still net long ~$4.3bn across remaining expiries — pin / low-vol supportive into 7-Sep, not a dealer-short gamma tape.
Flow risk if equities drop
Cover page snapshot: systematic strategies could sell on the order of ~$163bn in a down market (CTA + risk-parity + vol-control combined). Same architecture as the 21-Aug note: selling accelerates on roughly –3% SPX / –5% NDX / –5% RTY.
Tape implication: rates shorts are comfortable; equity CTA length is the fragility — especially RTY. Large-cap trend is still a tailwind unless spot breaks. Labor Day week is a long-gamma, low-realized setup unless a macro shock hits.