

Data-driven insights & expert commentary on the oil & gas industry. U.S. Frac Spread Count, Frac Job Count, EFRACS Analytics console and more!
Serving The Globe
Joined May 2013
- Tweets6.8K
- Following1.2K
- Followers3K
- Likes96


The future of oilfield services may increasingly depend on how companies allocate capital beyond the oilfield itself.
Liberty Energy's Q3 2026 outlook illustrates this emerging shift.
In Primary Vision's Q3 2026 Perspective, we examine Liberty Energy's completions outlook, power agreement execution and prospects for stronger shareholder returns.
Could diversification into power infrastructure fundamentally change how investors value pressure pumping companies?
[Liberty Energy, Q3 2026 Earnings, Pressure Pumping, Hydraulic Fracturing, U.S. Shale, Frac Activity, Oilfield Services, Completion Activity, AI Power Demand]

105
Primary Vision's market data was featured in OilPrice.com's latest coverage, “U.S. Oil, Gas Drillers See Minor Uptick as Oil Prices Crash.” The divergence raises an important question about how quickly changes in oil prices translate into changes in drilling and completion activity.
[Primary Vision, OilPrice.com, Media Coverage, U.S. Oil and Gas, Rig Count, Frac Spread Count, U.S. Shale, Oil Prices, Drilling Activity, Completion Activity]

123
Can a change in Washington influence U.S. oil production more than a change in oil prices?
As of November 10, WTI stands at $85.74 per barrel, while Brent trades at $91.12. The decline in crude prices comes as markets reassess geopolitical risks and the possibility of easing tensions between the U.S. and Iran.
Political leadership can influence drilling access, permitting and regulatory costs. Yet the decision to deploy capital, complete wells and bring additional barrels online ultimately depends on the economics facing producers.
Our Monday Macro View examines the relationship between political developments, commodity prices and the operational decisions shaping U.S. shale. As we approach 2027, which will have greater influence on American shale activity: Washington's energy policies or the economics of producing the next barrel?
[Primary Vision, Monday Macro View, Oil Prices, WTI Crude, Brent Crude, U.S. Energy Policy, U.S. Midterm Elections, U.S. Shale, Frac Spread Count, Frac Job Count]

195
Stronger utilization and lower debt are encouraging signs but can KLX Energy Services sustain its recovery when activity slows?
For KLX Energy Services, Q3 2026 raises an important question about whether recent operational improvements can translate into lasting financial strength.
In our latest Q3 2026 Take Three, Primary Vision examines the operational and financial factors shaping KLX Energy Services' outlook.
[KLX Energy Services, KLXE, Q3 2026 Earnings, Oilfield Services, Wolf Pack Integration, Fleet Utilization, Operating Margins, Seasonal Slowdown]

1
221
For Weatherford International, Q3 2026 brings attention to how effectively the company can convert its international project pipeline into revenue and stronger financial performance.
In our latest Q3 2026 Perspective, Primary Vision examines the three questions shaping Weatherford International's outlook.
[Weatherford International, WFRD, Q3 2026 Earnings, International Oilfield Services, Project Awards, Contract Execution, NCS, Venezuela, Revenue Growth]

151
Improving utilization is one thing. Turning it into sustained profitability is another.
For ProFrac Holding, Q3 2026 raises an important question about the outlook for pressure pumping. With utilization expected to improve in Q4, can stronger demand translate into better pricing through 2027?
ProFrac's performance also depends on whether Flotek can continue offsetting weakness in Proppant Production, and whether the company can maintain positive free cash flow while managing debt and capital spending.
In our latest Q3 2026 Take Three, Primary Vision examines these three factors shaping ProFrac's outlook.
[ProFrac Holding, Q3 2026 Earnings, Pressure Pumping, Fleet Utilization, Flotek, Proppant Production, Pricing Power, Free Cash Flow, Capital Expenditure]

152
Physical crude oil prices have fallen much faster than futures in recent weeks, narrowing a gap that had reached record levels. But as the oil market adjusts to changing conditions, another important question emerges: what is happening further upstream?
The widening and subsequent narrowing of the gap between physical crude and futures prices shows how differently parts of the oil market can respond to changing conditions.
Primary Vision's Frac Spread Count™ and Frac Job Count provide two important perspectives: how many crews are active and how many completion jobs are being performed. Both datasets are now LIVE on EFRACS, giving market participants a closer look at the operational side of the supply equation.
[Physical Crude Oil Prices, Oil Futures, Crude Oil Market, Oil Price Volatility, Oil Supply and Demand, U.S. Shale, Upstream Oil and Gas]

183
For an integrated oil major, financial resilience increasingly depends on how effectively it manages its portfolio, not simply how much oil it produces.
BP's Q3 2026 outlook brings this question into focus.
The question is whether operational improvements and a more focused portfolio can deliver sustained financial strength when market conditions become less favorable.
In Primary Vision's Q3 2026 Take Three, we examine the three questions that could shape BP's next chapter.
[BP, BP Q3 2026, Oil and Gas Earnings, Integrated Oil Majors, Refining Margins, Castrol Divestment, Portfolio Optimization, Balance Sheet]

141
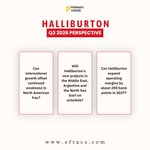
Can international expansion compensate for a prolonged slowdown in North American fracking? For Halliburton, the answer may depend on how effectively overseas opportunities translate into project execution, stronger margins and sustained profitability.
In Primary Vision's Q3 2026 Perspective, we examine Halliburton's growth prospects and its ambition to improve operating margins by approximately 200 basis points in 2027.
[Halliburton, Q3 2026 Earnings, Oilfield Services, International Expansion, North American Fracturing, Operating Margins, Middle East Energy]

185
U.S. drilling activity remains on hold, even as the oil market continues to navigate elevated prices and geopolitical uncertainty.
Primary Vision has been featured in OilPrice.com’s latest coverage, “U.S. Oil, Gas Drillers Still on Hold,” examining the state of American drilling activity.
According to Baker Hughes, the U.S. rig count remained unchanged at 603 this week, although it stands 57 rigs above the same period last year.
The contrast raises an important question about the industry's response to stronger oil prices.
Will sustained higher oil prices eventually encourage another expansion in U.S. drilling, or has capital discipline fundamentally changed how shale producers respond?
[Primary Vision, OilPrice.com, Media Coverage, U.S. Rig Count, Baker Hughes, Oil and Gas Drilling, U.S. Shale, Oil Prices, Drilling Activity, Capital Discipline]

147
Oil prices are opening the week lower as renewed diplomatic efforts ease some of the geopolitical risk premium built into crude markets.
As of November 2, Brent stands at $108.5 per barrel, while WTI is trading at $99.52. Murban crude remains elevated at $114.8, reflecting the continued importance of Middle Eastern supply to international markets.
The distinction is important. Diplomatic developments can change market expectations almost immediately, but restoring confidence in physical supply routes, shipping security and future availability takes considerably longer.
As the week begins, markets face a familiar dilemma: how much of the current oil price reflects actual supply constraints, and how much reflects the possibility of further disruption?
What will determine the next move in crude prices: progress in diplomacy or conditions in the physical oil market?
[Oil Prices, Brent Crude, WTI Crude, Murban Crude, Oil Market Update, Iran Negotiations, Strait of Hormuz, Geopolitical Risk, Global Oil Supply]

227
For Nabors Industries, the outlook for 2027 brings several competing forces into focus. Improving international oilfield activity could support demand for drilling services, while geopolitical uncertainty and a higher debt burden could complicate the conversion of that demand into stronger financial performance.
In Primary Vision's Q3 2026 Take Three, we examine the questions shaping the outlook for Nabors Industries and what they could mean for its performance heading into 2027.
[Nabors Industries, NBR, Q3 2026, Oilfield Services, Drilling Services, International Drilling, Oil and Gas Investment, Energy Markets, Geopolitical Risk]

134
For ProPetro Holding, the approach to 2027 raises an important question about the economics of growth in oilfield services.
Primary Vision's Q3 2026 Take Three examines these competing priorities and the questions they raise for ProPetro's financial outlook.
[ProPetro Holding, PUMP, PROPWR, Q3 2026, Pressure Pumping, Hydraulic Fracturing, Frac Pricing, Oilfield Services, Data Center Power]

162
Europe's energy vulnerability is once again coming into focus as rising oil and diesel prices raise concerns about a potential fuel crunch.
Primary Vision's Global Markets and Product Strategist, Osama Rizvi, was featured in Yahoo News, discussing the implications of higher fuel prices and Europe's exposure to disruptions in global energy markets.
The concern extends beyond the price of crude oil. Diesel is essential to freight transportation, industrial activity and supply chains, meaning sustained price increases could place additional pressure on businesses and consumers across Europe.
[Primary Vision, Yahoo News, Osama Rizvi, Oil Prices, Diesel Prices, European Energy Crisis, Fuel Supply, Energy Security, Oil Markets, Diesel Market, Global Energy Markets, Supply Chain Disruptions, Energy Geopolitics]

160
For Baker Hughes, this raises an interesting question about the relationship between traditional oilfield activity and the emerging infrastructure needs of the global economy.
Our latest Q3 2026 Take Three examines Baker Hughes' expanding IET backlog, its exposure to LNG and AI power demand, and the financial considerations shaping its international outlook.
[Baker Hughes, BKR, Q3 2026 Earnings, Industrial and Energy Technology, IET, LNG Infrastructure, Artificial Intelligence, AI Power Demand, Data Centers, Energy Infrastructure]

141
For NOV, this distinction is becoming increasingly important as the oilfield equipment industry prepares for 2027.
Our latest Q3 2026 Take Three examines NOV's order execution, regional demand outlook and the relationship between manufacturing activity and cash generation.
[NOV Inc, National Oilwell Varco, Q3 2026 Earnings, Oilfield Equipment, Oilfield Services, Manufacturing Efficiency, Order Backlog, Backlog Conversion]

198
For companies such as Patterson-UTI Energy (PTEN), the challenge heading into 2027 is understanding how improvements in drilling and completion productivity are reshaping the relationship between equipment demand, pricing and profitability.
Our latest Q3 2026 Take Three examines the questions shaping Patterson-UTI Energy's outlook as the industry prepares for another investment cycle.
Will the next phase of oilfield services growth be determined by how much equipment companies operate, or how much economic value they can generate from each asset?
[Patterson-UTI Energy, PTEN, Q3 2026 Earnings, Take Three, Oilfield Services, U.S. Shale, Contract Drilling, Pressure Pumping, Hydraulic Fracturing]

158
The real test of an offshore investment boom is how much of it translates into profitable growth. This creates an interesting advantage for companies such as TechnipFMC (FTI).
For TechnipFMC, the outlook for 2027 therefore rests on several interconnected developments: whether increased project activity can sustain subsea margin expansion, whether its opportunity pipeline converts into firm orders, and whether stronger cash generation can support both future investment and shareholder returns.
Our latest Q3 2026 Take Three examines these questions through TechnipFMC's subsea business, order outlook and free cash flow expectations.
[TechnipFMC, FTI, Q3 2026 Earnings, Take Three, Offshore Oil and Gas, Subsea Engineering, Subsea Production Systems, Offshore Investment, Project Backlog, Subsea Orders, Offshore Project Sanctioning, Capital Expenditure, Energy Security, Operating Margins]

1
156
A recovery in oilfield activity does not necessarily guarantee a recovery in profitability.
For companies operating across multiple oilfield service segments, the relationship between customer spending and financial performance is becoming increasingly complex.
RPC (RES) offers an interesting example.
For RPC, the coming quarters will test how effectively the company can convert improving activity into sustainable financial performance.
Our latest Q3 2026 Take Three examines the interaction between segment growth, operating cost pressures and working capital as RPC prepares for 2027.
[RPC Inc, RES, Q3 2026 Earnings, Take Three, Oilfield Services, Coiled Tubing, Nitrogen Services, Snubbing Services, Pintail Wireline, Well Intervention]

147
For SLB, the road to 2027 presents an interesting contradiction.
International oilfield activity could strengthen as producers reassess investment priorities and Middle Eastern markets gradually recover. At the same time, the rapid expansion of data center infrastructure is opening another avenue for growth.
Both developments offer commercial opportunities. Both also demand capital.
And that is where SLB's investment story becomes particularly interesting.
For SLB, the challenge is to capture opportunities in both conventional energy and emerging infrastructure markets without compromising the financial flexibility needed to navigate future investment cycles.
Our latest Q3 2026 Take Three examines three questions that could determine how this balance evolves through 2027.
Could SLB's biggest challenge in 2027 be deciding which growth opportunities are worth pursuing, rather than finding opportunities in the first place?
[SLB, Schlumberger, Q3 2026 Earnings, Oilfield Services, International Oil and Gas, Middle East Recovery, Data Center Solutions, AI Infrastructure, Kelvin Acquisition]

177