

100X Gemseeker l Follow me to discover top-tier projects before 99,9%.
Joined November 2016
- Tweets1.8K
- Following225
- Followers5.7K
- Likes4.6K





Pinned Tweet
There’s a reason ethereum:0x643c4e15d7d62ad0abec4a9bd4b001aa3ef52d66 made @citrini basket.
Given more % portfolio weight than $UNI & $ONDO, same as $LINK, at 18x, 9x & 36x smaller mc.
15.3x P/S: cheaper than $DRV (60x), $AAVE (44x), $HYPE (22x).
Only $AERO screens cheaper, and that’s funded by emissions. Ranked #2 on P/S among all DeFi projects in the entire basket.
ethereum:0x643c4e15d7d62ad0abec4a9bd4b001aa3ef52d66 outpaces top runner $DRV on buybacks, revenue and earnings at ~55% smaller FDV.
@maplefinance is on its way to becoming one of the biggest DeFi x RWA protocols. Should be an easy 3-5X on current fundamentals in this cycle in liquid size.
I’m releasing a big RWA tokenization comparison soon: revenue, growth and revenue trajectory and more important economic metrics of all big competitors.
Had some delays, but it’s coming this week.
You’ll see why ethereum:0x643c4e15d7d62ad0abec4a9bd4b001aa3ef52d66 is the big winner in its niche as well.
Dips are for adding. We’ll see $1B+ within no time.


Godlike retweeted
There’s a reason ethereum:0x643c4e15d7d62ad0abec4a9bd4b001aa3ef52d66 made @citrini basket.
Given more % portfolio weight than $UNI & $ONDO, same as $LINK, at 18x, 9x & 36x smaller mc.
15.3x P/S: cheaper than $DRV (60x), $AAVE (44x), $HYPE (22x).
Only $AERO screens cheaper, and that’s funded by emissions. Ranked #2 on P/S among all DeFi projects in the entire basket.
ethereum:0x643c4e15d7d62ad0abec4a9bd4b001aa3ef52d66 outpaces top runner $DRV on buybacks, revenue and earnings at ~55% smaller FDV.
@maplefinance is on its way to becoming one of the biggest DeFi x RWA protocols. Should be an easy 3-5X on current fundamentals in this cycle in liquid size.
I’m releasing a big RWA tokenization comparison soon: revenue, growth and revenue trajectory and more important economic metrics of all big competitors.
Had some delays, but it’s coming this week.
You’ll see why ethereum:0x643c4e15d7d62ad0abec4a9bd4b001aa3ef52d66 is the big winner in its niche as well.
Dips are for adding. We’ll see $1B+ within no time.
$LINK & $SYRUP will be two of the biggest winners of this RWA cycle.
I’m preparing a deep financial valuation comparison between $SYRUP, $ONDO, $AAVE, $PENDLE & ethereum:0x58d97b57bb95320f9a05dc918aef65434969c2b2 for later this week.
Once you see the numbers, you’ll understand why.

Godlike retweeted

🔥 I’m starting to build a @maplefinance| $SYRUP position around here.
The reason is pretty simple:
1/ Maple’s business has kept growing, but the token has mostly traded like a lagging governance asset.
That setup is starting to change.
@maplefinance currently has:
- ~$4.8B AUM
- ~$22M revenue over the last 12 months
- ~$1.47M monthly protocol revenue
- ~$38M treasury
- ~$297M $SYRUP market cap Maple Finance
And now there is an actual mechanism connecting that business back to the token.
MIP-021 makes buybacks rules-based:
- < $1.5M monthly revenue -> 10% buybacks
- $1.5M-$2M -> 20% buybacks
- $2M -> 30% buybacks
July and August already bought back ~1.53M $SYRUP combined.
2/ But imo distribution is the bigger catalyst.
syrupUSD assets are already spreading across Robinhood, Arc, Solana and other chains, while the CCIP 2.0 upgrade is making cross-chain movement faster and preparing native mint/redeem beyond Ethereum.
So the thesis is not complicated:
More syrupUSD distribution -> more AUM -> more revenue -> larger buybacks + treasury -> stronger value capture for $SYRUP.
At ~$300M mcap against a ~$4.8B asset-management business, I think this is worth taking a position on.
Now I want to see whether distribution finally makes the token catch up with the business.
Some chads are bullish at $SYRUP: @game_for_one @rektdiomedes @qthomp @RWAgemdigger @CryptoNewton @ourcryptotalk @Axel_bitblaze69 @CryptoPrestito @kenodnb

$LINK vs ethereum:0x643c4e15d7d62ad0abec4a9bd4b001aa3ef52d66 l similar breakout setup loading… 👀
Two giants in the making. One is still lagging behind — for now.
$ONDO $CC $PLUME $BP


Wondering how long until $SYRUP catches up to ethereum:0xfaba6f8e4a5e8ab82f62fe7c39859fa577269be3
$SYRUP: $255M mcap
ethereum:0xfaba6f8e4a5e8ab82f62fe7c39859fa577269be3: $2.7B mcap
10x cheaper, yet Maple has:
• More AUM ($4.8B vs ~$3.6B)
• More 30d fees ($8.7M vs $7.4M)
• 63% utilization of RWA vs 2.27%
• $3.2M in Q3 protocol revenue vs $0
• TVL SYRUP about to go ATH
2.4x fees vs 30x. Do the math.
@maplefinance biggest catalyst could be scaling syrupUSDC into Revolut’s 70M+ user base potentially early next year. Already done it on Robinhood this year with syrupUSDG.
That would give Maple access to one of the largest retail distribution channels any DeFi credit protocol has ever had.
Tokenization has been getting solid bids across stocks + crypto lately.
Outside my current RWA stack $HOOD $CRCL $LINK $DUAL $SECZ, I’ve added one high-potential name that still has no awareness on X:
$FIGR
Figure is one of the fastest-growing names in the entire listed blockchain/RWA industry.
An exceptionally high ~39% net margin, second only to $HOOD at ~44%. But Figure’s margin expanded ~2x faster YoY, while net income grew +192% vs +48%.
What caught my attention most is the business model.
Figure gives banks and lenders the infrastructure to originate, fund and sell tokenized loans much faster and cheaper.
A home-equity loan costs Figure roughly $730 vs ~$11K industry average (~15x cheaper) and takes around 10 days vs ~42 days (~4x faster).
Instead of competing with institutions, Figure sells them the rails into a rapidly growing ~$2T/year lending market.
And the demand with adoption is already showing:
489 origination partners, +102 in one quarter.
$4.3B quarterly loan marketplace volume, including $2.8B through its institutional Figure Connect marketplace, +132% YoY overall.
65% runs through Figure Connect, which grew ~75% QoQ.
The earnings are scaling with it:
YoY: revenue 2x, EBITDA 2x, net income 3x, EPS 4x.
QoQ: EBITDA +40%, net income +93%, EPS ~2x.
Already profitable with roughly $1.5B cash reserve, ~18% of market cap. No dillution needed.
High margins. Triple-digit growth. Strongly growing Institutional distribution. And still barely talked about.
Should do very well over the next 2–3 years as tokenization adoption scales.


🇺🇸 JUST IN: CFTC Chairman Selig says US markets must prepare for "mass tokenization" as blockchains and AI are "adopted at scale."
Selig told the US Treasury Market Conference that "the next decade will likely bring more change to financial markets than the previous several decades combined."
The CFTC expanded eligible collateral to include stablecoins in February and is looking to drive further adoption across exchanges and clearinghouses.


Godlike retweeted
1% of $DUAL's total supply just got absorbed off the market in less than 2 months.
From actual enterprise demand. VISA and SMT had to acquire it just to pay fees for one client on Dual's L2 mainnet. That client is FIFA World Cup.
Let that sink in.
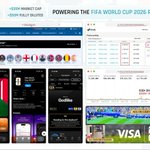
FIFA's main World Cup loyalty program is running live on Dual. Every FIFA Rewards token minted forces someone to acquire $DUAL. The math is verifiable onchain:
→ 20M+ FIFA Rewards tokens minted in 2 months
→ Every mint costs $0.02 in $DUAL fees
→ $400K+ in real protocol fees from token minting alone
→ 1% of $DUAL total supply absorbed from the market by VISA and SMT to pay them
Then theres the Points side. 3M+ users, each holding FIFA Points valued at ~$0.001 each (simple to do the math)
Thats nearly $3M in circulating tokenized loyalty value on Dual right now, from one program.
Heres the part that should genuinely change how you think about this.
Those 3M+ users? They dont know theyre on-chain. FIFA Rewards is on the front of FIFA.com, in the main nav next to Tournaments and Watch. The FIFA Rewards mobile app is #1 on the App Store right now. Banner placements at every match. Physical activations across every venue around the stadiums. Millions of casual football fans, tapping, earning, redeeming. All of it settling to Dual. Not one of them typed the word "wallet."
This is the actual "onboarding the next billion" story that every L1 has been trying to tell for 5 years. Except Dual is just quietly doing it. No cringe onboarding funnels, no seed phrase tutorials, no gas token popups. A stadium full of football fans on-chain and none of them care because they dont have to.
No other chain can handle this scale of enterprise deployment. No other protocol has the wallet infrastructure to onboard millions of Web2 users without breaking UX. This is what an entire decade of enterprise R&D actually buys you.
And it gets better.
Dual Network did more usage in the past 6 weeks than in the previous 4 YEARS of BlockV combined. 4 years of the previous brand, eclipsed in 6 weeks after the rebrand. The relaunch as Dual just flipped a switch on something that was already battle-tested, and the growth curve is vertical.
FIFA is client #1. First one live on Dual mainnet.
Behind it is a full pipeline of multi-billion dollar corporations. VISA (worlds largest payment network) and SMT (worlds largest engagement marketing company) are effectively doing enterprise BD for Dual. Every ranked Fortune 500. 150M+ merchants. Every loyalty program they onboard has to acquire $DUAL to settle on the L2.
VISA is doing BD for a $35M cap chain. how is this not priced in yet.
The World Cup campaign alone generated 5 billion views on Duals engagement solution. Same infra VISA is using for its own clients. This isnt X shilling. Pitch-side visibility every match, physical placements around every stadium, on the homepage of FIFA.com right now.
rewards.fifa.com, go look for yourself.
Now compare to the rest of RWA.
ONDO, CFG, MORPHO all growing, none converting usage into direct token demand at this scale. $SYRUP did $244k in buybacks in a single month at roughly 4x $DUALs market cap. Meanwhile Dual absorbed 1% of supply from real enterprise activity on a single client and generated $400K+ in fees in the same window. On a demand-per-market-cap basis this is the most undervalued protocol in the entire RWA sector.
Setup on the table:
→ 6 weeks of Dual > 4 years of BlockV
→ $400K+ in real fees from a single client
→ 1% of supply absorbed by enterprise buyers
→ 3M+ users onchain, none of them know it, none of them care
→ #1 app on the App Store settling into Dual
→ $3M in circulating tokenized loyalty value
→ VISA + SMT doing the enterprise acquisition
→ Fortune 500 pipeline behind FIFA
→ Trading at 4-5x lower cap than RWA competitors
This is a pivotal moment. FIFA is the trigger, not the ceiling. Big partnerships are already lined up behind this, and every one of them stacks on top of what FIFA is already doing.
In a normal market this 10x's without breaking a sweat.
First client is FIFA and it already did all this in 2 months. Imagine the tenth.
The full breakdown of the team (Tether founders), the tokenomics, the VISA relationship, the $1T loyalty market thesis and why Dual sidesteps the Clarity Act yield ban is dropping in the next post.


⚽️ Very exciting to see SmartMedia Technologies, a Dual enterprise partner, powering FIFA Rewards.
“FIFA's official rewards platform designed to bring fans closer to the game.”
#FIFAWorldCup

$CRCL + $LINK, $AAVE & $SYRUP are starting to move nicely on this OCC approval.
I said it earlier: next cycle will be dominated by RWA once the Stablecoin Clarity Act is approved.
The biggest bottleneck is the passive yield products that stablecoins can't provide in the USA. $DUAL will be the only one providing a solution, together with VISA and @SmartMedia_Tech.
$DUAL Loyalty token = generated through activity/engagement + price stability like a stablecoin (without being one) + payment utility across global merchant rails + yield for treasury programs + an engagement network layer.
All the right RWA metrics for @DualOrg are going vertical now. TVL is growing rapidly, and 1% of supply has been bought back within 2 months.
There will be a moment when crypto outperforms stocks again. The next few months will be crucial for accumulating inside the right narratives.
$DUAL + $CRCL will be my Stablecoin Clarity Act regulatory framework play.


Circle has received final OCC approval to establish First National Digital Currency Bank, N.A., a national trust bank operating as Circle National Trust.
A major U.S. regulatory milestone that strengthens USDC infrastructure through federally regulated custody, with reserve management planned as a future capability.
“Federal oversight of our trust bank sets a new standard for transparency, governance, and scale for Circle’s infrastructure and unlocks a new phase of adoption, where leading financial institutions can build on public blockchains with clarity and confidence.” - @jerallaire
circle.com/pressroom/circle-…

1% of $DUAL's total supply just got absorbed off the market in less than 2 months.
From actual enterprise demand. VISA and SMT had to acquire it just to pay fees for one client on Dual's L2 mainnet. That client is FIFA World Cup.
Let that sink in.
FIFA's main World Cup loyalty program is running live on Dual. Every FIFA Rewards token minted forces someone to acquire $DUAL. The math is verifiable onchain:
→ 20M+ FIFA Rewards tokens minted in 2 months
→ Every mint costs $0.02 in $DUAL fees
→ $400K+ in real protocol fees from token minting alone
→ 1% of $DUAL total supply absorbed from the market by VISA and SMT to pay them
Then theres the Points side. 3M+ users, each holding FIFA Points valued at ~$0.001 each (simple to do the math)
Thats nearly $3M in circulating tokenized loyalty value on Dual right now, from one program.
Heres the part that should genuinely change how you think about this.
Those 3M+ users? They dont know theyre on-chain. FIFA Rewards is on the front of FIFA.com, in the main nav next to Tournaments and Watch. The FIFA Rewards mobile app is #1 on the App Store right now. Banner placements at every match. Physical activations across every venue around the stadiums. Millions of casual football fans, tapping, earning, redeeming. All of it settling to Dual. Not one of them typed the word "wallet."
This is the actual "onboarding the next billion" story that every L1 has been trying to tell for 5 years. Except Dual is just quietly doing it. No cringe onboarding funnels, no seed phrase tutorials, no gas token popups. A stadium full of football fans on-chain and none of them care because they dont have to.
No other chain can handle this scale of enterprise deployment. No other protocol has the wallet infrastructure to onboard millions of Web2 users without breaking UX. This is what an entire decade of enterprise R&D actually buys you.
And it gets better.
Dual Network did more usage in the past 6 weeks than in the previous 4 YEARS of BlockV combined. 4 years of the previous brand, eclipsed in 6 weeks after the rebrand. The relaunch as Dual just flipped a switch on something that was already battle-tested, and the growth curve is vertical.
FIFA is client #1. First one live on Dual mainnet.
Behind it is a full pipeline of multi-billion dollar corporations. VISA (worlds largest payment network) and SMT (worlds largest engagement marketing company) are effectively doing enterprise BD for Dual. Every ranked Fortune 500. 150M+ merchants. Every loyalty program they onboard has to acquire $DUAL to settle on the L2.
VISA is doing BD for a $35M cap chain. how is this not priced in yet.
The World Cup campaign alone generated 5 billion views on Duals engagement solution. Same infra VISA is using for its own clients. This isnt X shilling. Pitch-side visibility every match, physical placements around every stadium, on the homepage of FIFA.com right now.
rewards.fifa.com, go look for yourself.
Now compare to the rest of RWA.
ONDO, CFG, MORPHO all growing, none converting usage into direct token demand at this scale. $SYRUP did $244k in buybacks in a single month at roughly 4x $DUALs market cap. Meanwhile Dual absorbed 1% of supply from real enterprise activity on a single client and generated $400K+ in fees in the same window. On a demand-per-market-cap basis this is the most undervalued protocol in the entire RWA sector.
Setup on the table:
→ 6 weeks of Dual > 4 years of BlockV
→ $400K+ in real fees from a single client
→ 1% of supply absorbed by enterprise buyers
→ 3M+ users onchain, none of them know it, none of them care
→ #1 app on the App Store settling into Dual
→ $3M in circulating tokenized loyalty value
→ VISA + SMT doing the enterprise acquisition
→ Fortune 500 pipeline behind FIFA
→ Trading at 4-5x lower cap than RWA competitors
This is a pivotal moment. FIFA is the trigger, not the ceiling. Big partnerships are already lined up behind this, and every one of them stacks on top of what FIFA is already doing.
In a normal market this 10x's without breaking a sweat.
First client is FIFA and it already did all this in 2 months. Imagine the tenth.
The full breakdown of the team (Tether founders), the tokenomics, the VISA relationship, the $1T loyalty market thesis and why Dual sidesteps the Clarity Act yield ban is dropping in the next post.
⚽️ Very exciting to see SmartMedia Technologies, a Dual enterprise partner, powering FIFA Rewards.
“FIFA's official rewards platform designed to bring fans closer to the game.”
#FIFAWorldCup
Tagging a few chads that might be interested in $DUAL @DualOrg
@sjdedic
@0xdetweiler
@EricCryptoman
@Anbessa100
@CryptoWizardd
@WAGMONSTR_
@jkrdoc
@platacrypto
@crypticd22
@spyzer
@BernieOnChain
Godlike retweeted

$DUAL is quietly becoming one of the most undervalued RWA plays. 👀
✅️ SmartMedia Technologies, a Dual enterprise partner is powering FIFA Rewards.
3M+ users onboarded through the FIFA campaign.
✅️ $400K+ in protocol buyback fees generated in just 2 months.
✅️ Nearly 1% of the circulating supply already bought back.
✅️ Enterprise pipeline powered by VISA + SMT with access to Fortune 500 companies and 150M+ merchants.
@DualOrg is undervalued ✍️

For now I’m holding:
• $DUAL — connector for Visa on-chain largest loyalty program run on OUSD through 120M+ merchants.
• $LINK — main connector for RWA (oracles + CCIP, institutional data feeds)
• $EDGE — connector for machine economy x402 infra blockchain
• $TAO — main connector for decentralized intelligence
I’ll share more insights in the coming weeks on why $DUAL and $EDGE remain solid lower-cap plays with serious multiple potential.
Both survived the recent massacre where many legitimate projects disappeared, got rugged, were exploited or "hacked", or simply failed to gain traction, including a significant portion of my own portfolio such as $XMW.
EDGE + DUAL been building both for (9+) years, showing real resilience, a growing revenue, and user real-world adoption, making them suitable for becoming top performers in the next cycle in most likely Q4.
I’ve been less active publicly lately, as the stock market gotten most of my interest due the PA being way more bullish
Crypto hasn’t offered many good entry opportunities over the last months, but I believe we’re starting to see new long-term setups emerging.
Core narratives for this next cycle I'll be watching:
1) RWA + Stablecoin Clarity Act (USDC + OUSD)
2) Agentic economy x402
3) Robotics: On-chain ID/Wallets/M2M (Physical AI/DePAI)
$Virtual robotic eco szn
Still holding $ROBOT — added $HEXAR. ($1.7M MC)
> Universal agentic diagnostic + repair system for machines (robots → autonomous cars). > Founder: ex @Jaguar Land Rover (@PrajwalGote19), 8+ yrs in autonomous systems.
> Pilot is planned with a company called
@StarshipRobots & already in contact with multiple top universities around the globe.
> been working on an AI demo for over 8 months & supported by the European lead of
@virtuals_io. Can see them pushing their token heavily.
@0xdetweiler done an interview with the founder of Hexar. I'd recommend checking it out.
xitter.cf/0xdetweiler/status/198…
Linkedin Founder Hexar: linkedin.com/in/prajwal-gote…
DYOR


Robot models don't have the benefit of internet scale data that LLMs do
Tesla, Google, Meta are all massively ramping up creation of proprietary robot training data
Token incentives could potentially create the largest open source robot training data set
Cool work by @virtuals_io
Godlike retweeted

1X announced the preorder of their humanoid home robots yesterday, starting at just $20K or $499/month.
The announcement generated major hype across the robotics space, and the crypto x robotics sector reacted instantly. $PEAQ for example as the top robotics coin currently outperforming everything else while the broader market is tanking.
People need to start realizing that even if this future feels dystopian, it’s much closer than most imagine or would even like it to be.
It’s now a full-on race between leading robotics manufacturers like Figure, Apptronik, 1X, Unitree, and others, all pushing to deliver affordable humanoids for everyday life and become the first movers in this new era.
In my opinion, this announcement was just a small teaser of what’s coming from the robotics scene in the next months and years.
And honestly, announcements like this create a flywheel effect, competitors feel the pressure to accelerate their roadmaps and drop their own big reveals even faster.
For most people, the crypto x robotics market is the best way to actually bet on this transformation even if, for now, it’s largely a narrative play.
A 10-20x market cap expansion in crypto × robotics within the next 6–12 months wouldn’t surprise me at all.


