

Founder of Pari Passu, research firm that provides all-encompassing coverage of the most consequential restructuring transactions. Join our free email list!
Join 25k+ investors/bankers 👉
Joined April 2022
- Tweets6.7K
- Following566
- Followers52.9K
- Likes5.3K





Pinned Tweet
How a 2021 software buyout became one of the largest private equity losses ever recorded
Thanks to everyone for playing.
Getty Images is going back private.
The company went public in 1996, with a nice 30-year run.

Getty Images has filed for prepackaged Chapter 11 bankruptcy in Delaware as part of a Koch-backed take-private restructuring.
The plan includes up to $533mn in equity investment from the Getty family and Koch Equity Development, the retirement of $270mn in unsecured notes, and extensions to secured debt maturities.
Koch will also provide up to $143mn in bankruptcy financing. Existing shareholders will be wiped out, with the new investors owning 100% of the reorganized company upon emergence.

>lead product for news feed and creator monetization at meta and X
>spend years seeing exactly how things grow in the feed
>cofounder scaled facebook groups to 1bn+ users
>build nectar
>$40mm+ raised, backed by Anthropic's Anthology Fund
I spent way too much time doing busy marketing work while building Pari Passu, no alpha in that - great to see this!
🤝 Paid partnership

Engineers stopped writing every line of code and started directing agents.
Growth and marketing teams are in that moment now.
Meet the next chapter of Nectar: the agentic growth stack. One platform replacing 5+ legacy tools. Agents that work every message, creator outreach and creative research about your brand, and tie it all back to revenue 🍊
Hertz, the next non-sub (JV) dropdown?
- Hertz has Oro Mobility in its own subsidiary
- Oro Mobility is Hertz’s side business that runs vehicle fleets for ride-hailing and robotaxi companies like Uber, a great asset
- Certares and Knighthead purchase 50% of voting units and 16% of common equity of that entity, the entity is therefore a JV (see next tweet)
- Hertz also agrees to retire $51mm of 2L due 2029 from Certares and Knighthead at 60% discount (which likely bought this debt before at even greater discount)
- Debt is retired at a discount, a JV is ready with unencumbered assets, Certares and Knighthead make a gain on the flip, everyone wins, right? Sorry to whoever sold their 2L to Certares and Knighthead ha!
The next step?
- Class, you now have a nice entity with unencumbered assets, a ParentCo which needs to extend its maturities. What do you suggest doing?
- Raise debt against those assets, a beautiful non-subsidiary dropdown. Maybe, yes!
Read our primer on Non-Subsidiary Dropdowns to learn more, awesome work from our legal analyst!


NON-SUBSIDIARY DROPDOWN PRIMER | PUBLISHED
This week, we are passing the pen from our financial analyst to our legal analyst to put the Xerox transaction structure under the microscope to understand how the Non-Subsidiary Joint Venture works, and where it sits alongside other landmark dropdown transactions.
We do this by looking at the history of both asset dropdowns and non-subsidiary LMEs (yes, Xerox was not the first, actually!), before running through a simple hypothetical transaction to demonstrate how the Xerox-style non-subsidiary dropdown works step-by-step and its use case: to get around popular asset dropdown blockers.
From there, this write-up takes an analytical and critical turn.
We think there are some features of the non-subsidiary dropdown that everyone is missing.
So we want to bring them to your attention and contribute to the wider discussion around these transactions. Our first claim is that it is too narrow to equate non-subsidiaries with minority-owned joint venture corporations. If we start from first principles, we can see that a joint venture corporation is a means to accomplish a non-subsidiary dropdown, but it is conceivable that there are other ways to achieve this.
Next, we claim that it is worthwhile to explore other options, as joint venture corporations do come with significant legal disadvantages for the borrower. In light of these disadvantages, we propose two alternative non-subsidiary structures, using US and UK law, that a borrower can use to avoid giving the incumbent lender majority voting power / an equity position in the entity with the valuable assets.
We then conclude with some thoughts on recent market developments and how to think about Xerox Blockers given what we’ve learned today.
We are incredibly excited to bring this analysis to you! Read below


Going a level deeper and quoting our legal analyst
"At this stage, it’s worth getting granular about what a ‘Subsidiary’ actually means. For the purposes of credit documents and, by extension, LMEs, this is principally a contractual question: the documents themselves define which entities are classified as a Subsidiary.
In Xerox, the legalese largely boils down to identifying whether Xerox owns or controls more than 50% of the votes that can be used to choose the people who manage the entity. This would typically be ordinary shares in a company. If Company X controls more than 50% of the votes attached to equity interests entitled to elect Company Y’s directors, managers or trustees, Y falls within the Subsidiary definition and is a subsidiary of X. But if X owns 50% or less, Y may sit outside it. This creates a potential fourth recipient of dropdown assets: a ‘Non-Subsidiary’ (Non-sub), neither an NGRS nor an Unsub and therefore outside restrictions drafted solely by reference to those categories."
In Hertz, the same logic applies, see definition below.


I hear a lot of pushback from SMBs saying they don’t need AI because their industry has high moats.
To me, that’s like saying we won’t make a website or use the internet because we have a high moat.
Sure, that moat might give you some runway, but it won’t adapt; you’ll eventually fall behind.
And once you’re behind, you’ll never recover as the gap is only getting larger.

POV: A Gen Z learns what it takes to earn multiples of the average household income in your early 20s in your first job after college

I hear a lot of pushback from SMBs saying they don’t need AI because their industry has high moats.
To me, that’s like saying we won’t make a website or use the internet because we have a high moat.
Sure, that moat might give you some runway, but it won’t adapt; you’ll eventually fall behind.
And once you’re behind, you’ll never recover as the gap is only getting larger.
🤝 Paid partnership

In September 2021, Clearlake Capital acquired Springs Window Fashions for approximately $3.4bn or almost 11x EBITDA
The deal was done in the middle of a zero-interest-rate environment and strong discretionary consumer spending, when many people had the time and cash to spend during COVID.
In this case specifically, people were stuck at home during lockdowns, which encouraged many to update and renew major home design components, a dynamic called “nesting purchases”.
However, inflation and rapid rate hikes pushed up costs while freezing the housing market, so existing home sales and remodeling activity dried up and consumers pulled back on big-ticket home spending. Revenue declined through 2024, margins compressed, and the business started burning cash. By late 2024, SWF had run through most of its liquidity and needed a transaction to keep operating.
The company completed an LME in 2024 that addressed liquidity and extended maturities; however, ongoing housing market pressures prolonged distress, and we expect a second transaction within the next 12 months.
On Friday, we will dive into the company history, business overview, break down the first LME, and understand where we are today, subscribe now to get in your inbox on Friday


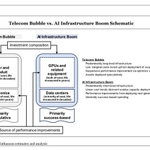
The graphic below is something everyone should understand
1) In the AI Capex cycle, the majority of the infrastructure is short-lived vs. long-lived for Telecom cycle
2) In the AI Capex cycle, the costs are linear vs. high upfront and low at the margin for the Telecom cycle (making a bubble easier to form)
3) In the AI Capex cycle, spending tends to be more success-based than in the Telecom cycle

If you are confused about what this technology is, that makes two of us.
After spending some time, this is how I think about it.
When you ask an AI a question, two things happen:
1) Understanding your question. This is like a researcher reading your request and figuring out what you need. It takes a lot of raw thinking power, and standard AI chips (GPUs) are great at this part.
2) Writing the answer, one word at a time. For each word, the researcher has to run back to the shelves to look something up before writing it. They aren’t slow at thinking here. They’re slow because they keep waiting on the trip to the shelves. That trip is the “memory” part.
Positron’s chips are built to make those trips much quicker, so answers come out faster. Standard chips rely on a particular kind of fast memory that’s currently in short supply, and @positron_ai ’s design doesn’t depend on it.
@general_compute’s idea is to use both kinds of chips: the thinking-focused ones for understanding your question, and the shelf-focused ones for writing the answer. Then they sell the whole thing to companies as one service.
This matters most for AI agents, which are programs that make dozens of AI requests in a row to finish a single job. If each request is a little slow, the delays stack up, like a chain of errands where every stop takes a bit too long and the whole trip drags.
🤝 Paid partnership

Our heterogeneous cloud just got better. We're announcing a cluster scale deployment of @positron_ai as our next partner.
We believe demand for fast inference will outstrip supply for the next decade. Our bet on Positron is another step towards getting fast inference for opensource models into builders' hands.
Hardware goes live Q1 2027.
Thanks to @mitesh711, @trsohmers and the whole Positron team! We're excited for this partnership.
LFG!
All of the robotics companies are purely focused on performance, but they forget that trust and perception matter just as much.
I would never want a scary humanoid in my bedroom, no matter how good it is.
This company actually considers the experience of living with a robot, and I am convinced this will be much more appealing to consumers.
🤝 Paid partnership

Simple representation of myself trying to get differentiated information
> You send an email asking for some experts
> You go back and forth to find someone that works and a time
> You speak for 60 min
> Most of them are useful, and you really get value out of 15min
> 1 call = $1,000+ = just a few core insights
> Scale over 50 names, multiple calls for names, and you see why pods create dedicated teams
Qualitate is trying makes easier and change the equation. One centralized repository with thousands of expert calls on the core insights that matter.
How painful is it to switch? Will you switch? And why?
🤝 Paid partnership


We just raised $25M from Insight Partners to replace Gartner, McKinsey, and GLG.
RIP the Quadrant, the 80-page consulting deck, and the $2000 expert network call.
Our revenue run-rate is up 10x+ this year.
100+ investment firms and enterprises use Qualitate to inform decisions with firsthand evidence.
Here's how:
qualitate.io/book-a-demo
"Hello everyone
Please go load up on Tesla
Our Monte Carlo simulation gives a 53% to 66% CAGR through 2031!"


What could @Tesla be worth in 2031? ARK’s long-awaited valuation just dropped.
ark-invest.com/articles/valu…

In my years on the buyside, I have experienced first-hand the democratization of institutional investing to retail investors. This said, these opportunities are still hard to find, which is why I am excited to partner with Lightstone Group in bringing you their first retail vehicle.
Backed by Lightstone Group’s nearly four decades of experience and $12bn+ in assets under management, Lightstone DIRECT gives accredited investors access to our proprietary deal pipeline, previously available only to institutions. With a 26% IRR across 55 realized deals since 2004, they bring a proven track record of performance. As a vertically integrated sponsor, they manage every operation in-house and invest at least 20% of their own capital in every deal.
If you are an accredited investor looking to deploy capital directly in real estate deals, you can sign up for free on their platform. After signing up, you will receive access to their proprietary deal flow.
lightstonedirect.sjv.io/9Lbk…
🤝 Paid partnership

On the topic of personal finance, Agent is a modern tax strategy firm purpose-built for investment professionals.
You will receive a dedicated expert tax advisor (yes, human) who will leverage technology to proactively plan, prepare, and optimize your taxes.
Tax is everyone’s biggest expense, and this is a great service to minimize tax leakage. Click below to learn more with a free consultation and mention Pari Passu to get $100 off.
agent.tax/?utm_source=pp&utm…
🤝 Paid partnership
