

Former sell-side analyst. Research on technology, industries and capital cycles. Connecting business fundamentals with market expectations.
Joined January 2026
- Tweets2.9K
- Following92
- Followers3.3K
- Likes4.6K



Pinned Tweet
$AAOI
Tonight's $550 million filing marks $AAOI's fourth at-the-market equity program in nine months ($2.25 billion total). Each round in 2026 has brought heavier drawdown pressure and weaker post-offering relief:
1. ATM ($500M, Feb 26–Apr 2): Initial $250M rode a Q4 beat, yet the standalone March 12 expansion to $500M ($106.19 close) knocked shares down 8.8% Day 1 and 20.3% to $84.59 before a 114.7% post-completion squeeze.
2. ATM ($600M, May 14–Aug 17): Filed at $203.57 right off the $233.67 high. Shares fell 6.5% Day 1, plunged 62.4% intra-window to $76.52, and ended the program down 23.9% with the cycle peak permanently locked in.
3. ATM ($600M, Aug 21–Oct 1): Filed at $124.82. Shares dropped 13.8% Day 1 and 23.7% to $95.29; completion sparked only a four-day pop to $130.16 before a 65.3% slide to $45.22.
4. ATM Outlook ($550M, filed Nov 17 at $45.22, $43.25 AH): Raising $550M at $45.16 requires 12.18 million shares (+13.4% dilution)—nearly matching the 13.80 million shares across the first $1.70B combined—with zero earnings catalyst until February. Active placement supply should cap bounces near $45–$50 and drag shares 15%–25% toward $34–$38 (roughly 1.3x the $27.69 post-ATM tangible book floor), leaving any tradable relief bounce until the completion release clears the overhang.


$AAOI
With $AAOI already crushed 81% from its $233.67 peak to $45.22—and sliding toward $43 after hours—management just filed a new $550 million at-the-market stock offering, its fourth in nine months. Dropping another massive equity tap right into a bruised tape hits shareholders where it hurts most.
The dilution math turns punishing at depressed prices: raising $600 million at $183.06 this summer took 3.28 million shares, whereas $550 million at the $45.16 filing price requires 12.18 million new shares, a 13.4% share-count expansion. Applied Optoelectronics spent $1.19 billion across nine-month operating and investing cash outflows, carried $928.8 million in September 30 CapEx commitments, and just paid $102.25 million cash for three Houston plants to meet hyperscale 1.6T obligations.
Hyperscalers lock in contractually capped optical pricing while public shareholders foot a $2.25 billion 2026 ATM bill.


$AAOI
Shares of $AAOI slipped to $43.25 after hours following its $550 million equity ATM filing, stinging investors who trusted management's explicit assurance from twelve days earlier.
On the November 5 Q3 call at $46.89, CFO Stefan Murry told analysts Applied Optoelectronics was leaning more on debt than equity, while CEO Thompson Lin highlighted a new $200 million bank revolver and floated $400 million to $500 million in U.S. loans alongside internal profits. On that same call, the CFO projected higher 2027 CapEx moments before the CEO contradicted him live in Q&A, and twelve days later AOI launched up to $550 million in stock sales against $928.8 million in non-cancellable purchase commitments.
Management's financing guidance carried a twelve-day shelf life once real factory bills came due.

$AAOI
Tonight's $550 million filing marks $AAOI's fourth at-the-market equity program in nine months ($2.25 billion total). Each round in 2026 has brought heavier drawdown pressure and weaker post-offering relief:
1. ATM ($500M, Feb 26–Apr 2): Initial $250M rode a Q4 beat, yet the standalone March 12 expansion to $500M ($106.19 close) knocked shares down 8.8% Day 1 and 20.3% to $84.59 before a 114.7% post-completion squeeze.
2. ATM ($600M, May 14–Aug 17): Filed at $203.57 right off the $233.67 high. Shares fell 6.5% Day 1, plunged 62.4% intra-window to $76.52, and ended the program down 23.9% with the cycle peak permanently locked in.
3. ATM ($600M, Aug 21–Oct 1): Filed at $124.82. Shares dropped 13.8% Day 1 and 23.7% to $95.29; completion sparked only a four-day pop to $130.16 before a 65.3% slide to $45.22.
4. ATM Outlook ($550M, filed Nov 17 at $45.22, $43.25 AH): Raising $550M at $45.16 requires 12.18 million shares (+13.4% dilution)—nearly matching the 13.80 million shares across the first $1.70B combined—with zero earnings catalyst until February. Active placement supply should cap bounces near $45–$50 and drag shares 15%–25% toward $34–$38 (roughly 1.3x the $27.69 post-ATM tangible book floor), leaving any tradable relief bounce until the completion release clears the overhang.
4
1,120
$NVDA
Q4 will include an extra week. NVIDIA expects strong AI infrastructure demand and the continued Vera Rubin ramp to drive sequential revenue growth.
Quote: Now let me turn to the outlook for the fourth quarter. Please note we will have an additional week in Q4. Total revenue is expected to be $130 billion, plus or minus 3%. We expect sequential growth to be driven by robust demand for AI infrastructure the continued ramp of Vera Reuben.
2
1
412
$NVDA
NVIDIA reported 5x the power efficiency, 15x the reliability and 10% lower latency compared with pluggable optics.
Quote: NVIDIA Photonics, CPO switches connecting more than 10,000 GB300 GPUs. Compared with pluggable optics, NVIDIA Photonics switches delivered 5x better power efficiency, 15x higher reliability, and 10% lower latency.
1
380
$NVDA
The figure covers Hopper data center products licensed for sale to China. The guidance remarks are too fragmented to confirm how NVIDIA treats these sales in Q4.
Quote: Q3 sales of licensed Hopper data center products to China was 2.4 billion.
$NVDA
AI Clouds, Industrial and Enterprise revenue rose 18% from the prior quarter to nearly three times its year-earlier level. NVIDIA attributed the quarterly growth to Vera Rubin shipments to leading neocloud providers and frontier AI labs starting to build their own data centers.
Quote: AI Clouds, Industrial and Enterprise, or ACIE revenue, of $47 billion increased, 18% sequentially and nearly tripled year over year. Sequential growth was driven by Vera Rubin shipments to top leading Neo Cloud customers and the start of our frontier labs building their own data centers.

1
407
$NVDA
AI Clouds, Industrial and Enterprise revenue rose 18% from the prior quarter to nearly three times its year-earlier level. NVIDIA attributed the quarterly growth to Vera Rubin shipments to leading neocloud providers and frontier AI labs starting to build their own data centers.
Quote: AI Clouds, Industrial and Enterprise, or ACIE revenue, of $47 billion increased, 18% sequentially and nearly tripled year over year. Sequential growth was driven by Vera Rubin shipments to top leading Neo Cloud customers and the start of our frontier labs building their own data centers.
$NVDA
NVIDIA said token prices have fallen nearly 60% since May, driving up usage and compute demand. GPU rental prices are rising across generations, with Hopper securing higher rates on multiyear renewals.
Quote: Token prices have fallen nearly 60% since May. Accelerating token usage and demand for compute. As a result, GPU rental prices are rising across generations. Hopper GPUs have re-contracted at up to twice their original price under the multi-year agreements,
$NVDA
NVIDIA said token prices have fallen nearly 60% since May, driving up usage and compute demand. GPU rental prices are rising across generations, with Hopper securing higher rates on multiyear renewals.
Quote: Token prices have fallen nearly 60% since May. Accelerating token usage and demand for compute. As a result, GPU rental prices are rising across generations. Hopper GPUs have re-contracted at up to twice their original price under the multi-year agreements,
$AAOI
With $AAOI already crushed 81% from its $233.67 peak to $45.22—and sliding toward $43 after hours—management just filed a new $550 million at-the-market stock offering, its fourth in nine months. Dropping another massive equity tap right into a bruised tape hits shareholders where it hurts most.
The dilution math turns punishing at depressed prices: raising $600 million at $183.06 this summer took 3.28 million shares, whereas $550 million at the $45.16 filing price requires 12.18 million new shares, a 13.4% share-count expansion. Applied Optoelectronics spent $1.19 billion across nine-month operating and investing cash outflows, carried $928.8 million in September 30 CapEx commitments, and just paid $102.25 million cash for three Houston plants to meet hyperscale 1.6T obligations.
Hyperscalers lock in contractually capped optical pricing while public shareholders foot a $2.25 billion 2026 ATM bill.
$NVDA
NVIDIA beat revenue expectations by 6.6%, but its next-quarter margin outlook limits how much of that growth reaches operating profit.
1. The print
Q3 revenue was $115.84bn, up 103% YoY, vs $108.71bn consensus and the $108bn +/-2% company guide. Adjusted diluted EPS was $2.68 vs $2.47; GAAP EPS was $2.70. Weighted-average diluted shares: 24.186bn for Q3 FY27.
Data Center revenue reached $107.6bn vs the dated $101.8bn Visible Alpha benchmark. Hyperscale was $60.1bn, AI Clouds/Industrial/Enterprise $47.5bn and Edge Computing $8.2bn. NVIDIA says Rubin has shipped and describes it as its fastest architecture ramp.
2. The next-quarter trade-off
Q4 revenue guidance is $130bn +/-3%: $126.1-133.9bn, with the midpoint 4.1% above $124.89bn consensus and our preview's $124.92bn benchmark. Q4 includes an extra week and assumes no China Data Center compute revenue. Q3 included $2.4bn of Hopper shipments to China.
Q3 adjusted gross margin was 74.9%, above the 73.5%-74.5% guide. Q4 guidance falls to 71%-72%; adjusted operating expenses rise to $10.7bn from $8.841bn. At the revenue and margin midpoints, implied adjusted operating profit is about $82.3bn, up 5.6% from $77.883bn in Q3, versus 12.2% revenue growth. This is our calculation from company guidance.
3. Cash and commitments
Operating cash flow doubled sequentially to $48.253bn; free cash flow was $43.777bn. Cash conversion improved, although federal tax-payment timing helped. Receivables rose to $81.033bn, inventory to $39.724bn and DSO to 64 days from 60. NVIDIA cites shipment timing and extended customer terms.
Supply commitments rose to $390bn from $279bn. Maximum guarantee exposure reached $118bn. These are separate obligations with different conditions and timing.
4. Our preview questions
Q1 [Answered] Revenue, Data Center and adjusted EPS all exceeded their stated benchmarks.
Q2 [Partly answered] Q4 guide beats consensus; the extra week and delivery bridge need C1.
Q3 [Partly answered] Q3 profitability held; Q4's 71%-72% margin resets the outlook. Drivers and duration go to C2.
Q4 [Partly answered] Cash flow improved, while DSO lengthened. Collection and tax timing go to C3.
Q5 [Partly answered] Rubin's Q3 shipment milestone is met; FY28 growth visibility and funding commitments go to C4.
Q6 [Release cannot answer; carry to call] The matched management Q&A comparison goes to C5.
5. The call agenda
C1. Underlying Q4 growth after the extra week, China and Rubin delivery milestones.
C2. The 340bp margin decline at midpoint: mix, pricing, ramp costs and duration.
C3. Collection under extended terms and sustainable cash generation after tax timing.
C4. FY28 demand/supply visibility and the amounts, conditions and timing of commitments.
C5. Compare Kress with her prior answers and Huang's on matched questions, numbers and deadlines.
Our view: delivery strengthens the growth thesis; the lower Q4 margin makes profit conversion the next decisive test.


2
743
$NVDA
NVIDIA 3Q REV. $115.8B, EST. $109.33B
NVIDIA 3Q DATA CENTER REVENUE $107.6B, EST. $101.87B
NVIDIA 3Q ADJ GROSS MARGIN 74.9%
BOARD APPROVED AN BOOST OF $150B SHARE BUYBACK
SEES 4Q REV PLUS OR MINUS $130B VS 125B EST
2
569

$NVDA
🚨Five metrics to watch in NVIDIA’s earnings👇:
1. Revenue growth
Compare total revenue with expectations and Data Center revenue with last quarter. Watch whether growth is accelerating or slowing.
2. Next-quarter guidance
Compare the revenue outlook with consensus. This is our top priority: how much growth is still ahead.
3. Gross margin
Last quarter’s GAAP gross margin was 75%. Watch whether NVIDIA can sustain profitability as shipments expand.
4. Networking revenue
Track growth in networking alongside GPU sales. It shows how much NVIDIA earns from connecting the AI cluster.
5. Cash collection
Compare operating cash flow and receivables with revenue growth. Watch how quickly sales turn into cash.
Our priority: strong forward guidance, sustained margins and cash collection that keeps pace with growth.
2
5
638
$IQE
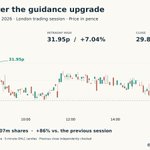
IQE raised its FY2026 revenue growth outlook to over 40%. Its shares rallied as much as 7.0% on November 17, then finished unchanged at 29.85p, with trading volume roughly 86% above the previous session.
The operating update was stronger. July’s revenue growth guidance was over 30%. IQE now expects adjusted EBITDA in the mid-teens of millions of pounds, says AI and data-center optical opportunities have converted into revenue, and reports strong order-book coverage for 2027.
The share price reached 31.95p before giving back the entire gain. Our read is that improving fundamentals met enough selling to leave the stock flat on the day. The next test is whether further revenue conversion and earnings delivery can attract buying that holds through the close.


$IQE $AXTI $LITE $COHR $SIVE
Panic selling across AI optics has left $AXTI 74% below its 52-week high, $COHR 55% off peak, $LITE down 8.5% Monday, and London's IQE LN 58% below highs near 30.5p. Fast money is dumping the photonics stack as if laser demand just hit an air pocket.
Primary filings across the Indium Phosphide chain show the exact opposite: substrate supplier AXT grew Q3 revenue 162% YoY and guided Q4 near 90 million USD on full allocation, Taiwan epiwafer leader 3081 TT jumped 183% YoY, and Lumentum plus Coherent guided to fresh record quarters. Today IQE hiked FY2026 revenue growth guidance again to over 40% YoY with strong 2027 order coverage, confirming captive fabs are overflowing into merchant reactors.
High-power 1.6T lasers consume up to twice the Indium Phosphide wafer area per chip, locking the entire material stack into a physical bottleneck through 2027.

2
5
595
$NVDA
Lambda has deployed CPO networking across 10,000+ Blackwell Ultra GPUs. Its reported pod-level latency is 10.1% lower than conventional pluggable optics, with the same throughput.
The November 16 announcement puts a concrete deployment behind the CPO investment thesis. At its Quebec campus, Lambda is using NVIDIA Photonics switches that move optical engines beside the switch ASIC, shortening the electrical signal path from inches to millimeters.
Lambda also reports median optics temperatures of 36°C versus 51°C for pluggables. The switches retain 18 removable external light sources, showing where lasers remain essential as the optical architecture changes.
We see this deployment as evidence that CPO is becoming part of large AI clusters. The investment focus now extends to optical-engine integration, external light sources and serviceability at scale.

1
2
468
$NVDA
I am very happy to be a member of MNGA(Make NVDIA great again!)


Over the past week, I’ve been overwhelmed by the love and support of friends, industry colleagues, and people I've never met. Thank you to everyone who has shown kindness to my family and me. It means the world to me.
I came to the United States 53 years ago, and becoming an American citizen is one of the greatest gifts and proudest moments of my life. NVIDIA has been my life’s work. Building it into the company it is today alongside my colleagues has been a privilege and an honor. Nowhere but in America could a company like NVIDIA be possible. I love our country, and I love NVIDIA.
I did not live up to the standards expected of everyone at NVIDIA, and I have made serious mistakes in my personal life. I created problems for the Board that I deeply regret. I own my mistakes completely, and I am committed to cooperating with the Board’s independent investigation.
Since my departure, I’ve seen an outpouring of calls from NVIDIA’s employees, investors, business partners, and customers for me to return as CEO. Many continue to reach out to me directly as the company navigates complex technology, market, competitive, and geopolitical dynamics. NVIDIA is a once-in-a-generation company. If the Board of Directors decides that my return is in the best interest of our shareholders, our employees, the company, and America, I would be honored to answer these calls and return as CEO.
Thank you again to everyone who has shared their good wishes. I am profoundly humbled by your support. To my family: I love you, and I will spend the rest of my life being worthy of yours.
Jensen
$AXTI
🚨🚨China, as a competitor, is on the rise and is about to challenge the status of $AXTI !
AXT's Chinese InP rival is adding RMB 81.43M to a project whose existing and under-construction capacity is already booked through end-2027.
Yunnan Germanium raised the project budget 43.2% to RMB 269.99M. The increase includes RMB 34.33M for higher equipment prices, RMB 42.56M for 294 additional equipment units to increase the large-diameter mix, and RMB 4.54M for installation. The project's stated target is 450,000 wafers/year in 4-inch equivalents.
The commercial evidence matters. On Nov 10, Yunnan disclosed roughly 13,000 six-inch wafers on order, worth about RMB 300M, mainly from leading overseas customers. Some orders already have export permits and are being delivered.
AXT has exceeded its 2026 capacity-doubling goal. Its Q3 SEC filing shows USD 108.22M in group contract liabilities. The newly filed Lumentum agreement runs six years and specifies a USD 43.5M initial deposit to support capacity expansion and reservation. Price increases require mutual written agreement.
Our read: Yunnan's six-inch orders establish a serious competitor in larger wafers, while its booked expansion supports strong InP demand. AXT's advantage must show up in qualified output, reliable delivery and contract economics as the market scales.


$AXTI $COHR $LITE $NVDA $SIVE
A new 100-ton 7N high-purity indium trial line in Yunnan adds upstream metal security for China, while leaving the global 70% Indium Phosphide wafer deficit completely intact through 2027.
Breaking wires out of China today flagged a domestic breakthrough in 7N-grade (99.99999% purity) indium for Indium Phosphide substrates. Tracing the primary disclosure shows Kingland Technology (000711. SZ) started trial runs on a 100-ton-per-year Phase II purification line in Lufeng, Yunnan, upgrading recycled zinc-indium smelting output to <=0.1g of total impurity per metric ton. Shares of $AXTI barely budged around $38.50 after hours, and the unit-consumption math explains why.
First, raw metal purification and single-crystal wafer growth sit worlds apart in the optical supply chain. A single 2-inch Indium Phosphide wafer consumes just 1 to 2 grams of 7N metallic indium. Even at 2.6 million to 3.0 million 2-inch-equivalent wafers of global demand in 2026, the entire global substrate industry absorbs fewer than 10 metric tons of 7N metal per year. Yunnan Germanium (002428. SZ), China's largest local substrate maker outside Beijing Tongmei, requires only 300 to 400 kilograms of 7N indium to run its existing 150,000-wafer annual line. Domestic specialist Zhuzhou Keneng already ships 6N to 8N ultra-pure indium at scale, and 7N metal commands only about RMB 1,000/kg (~$140/kg) over standard 4N-5N refined indium. Most of Kingland's 100-ton nameplate capacity will feed display targets and GPU indium thermal interface materials, while semiconductor qualification alone takes 1 to 5 years.
Second, the real US-China chokepoint war sits inside Vertical Gradient Freeze crystal furnaces (>1,000C at ~27 atmospheres) and Beijing's February 2025 MOFCOM Announcement No. 10 export licensing regime. China refines ~70% of the world's primary indium, yet three foreign-controlled players—Sumitomo Electric (~42%), AXT (~36%), and JX Advanced Metals (~13%)—still control over 90% of merchant Indium Phosphide wafers, with non-Tongmei Chinese vendors below 10% overall and under 5% at 6-inch.
AXT embodies this geopolitical split. Headquartered in Fremont with 100% of its substrate manufacturing inside China via Beijing Tongmei, AXT grew Q3 2026 revenue 162% YoY to $73.4 million at a 56.0% GAAP gross margin (up from 22.3% a year ago), yet Chinese export permit gating held its Q2 North America sales to $160,000. Even domestic champion Xinyao Semiconductor achieves a 7% to 8% direct crystal-to-wafer yield, roughly one-third of Beijing Tongmei's ~25% benchmark.
Third, US and Japanese optical leaders are spending billions to bypass that licensing bottleneck via onshore 6-inch integration and multi-year capacity prepayments. Every 1.6T optical module consumes roughly 2.7x to 3.0x the Indium Phosphide area of an 800G module, and silicon photonics still requires Indium Phosphide continuous-wave lasers because silicon cannot emit light efficiently. To lock down supply, $NVDA invested $2.0 billion each into $COHR and $LITE in March 2026 alongside multi-billion-dollar purchase commitments. Coherent ($7.12 billion FY26 revenue; Datacenter & Communications up 40% to $5.27 billion) broke ground on expanding the world's first volume 6-inch Indium Phosphide fab in Sherman, Texas with up to $50 million in CHIPS Act funding—quadrupling wafer output and cutting die cost by ~60%—while prepaying AXT $22.3 million for 3-year 6-inch supply. Lumentum committed $43.5 million in 6-year deposits to AXT with laser orders booked into 2028, while Japan's JX Metals is deploying JPY 120 billion (~$780 million) to expand non-China wafer capacity 7x to 10x by FY30.
China's 7N metal expansion fortifies domestic feedstock for local optical module giants like Innolight, while global pricing power in 1.6T and CPO optics remains anchored in 6-inch crystal yields, Chinese export permit cadence, and US-Japan fab scale.


$MU $CXMT $SKHY
Governance and capital-allocation answers from ChangXin Memory's Q3 2026 earnings briefings explain why an 89.53% gross-margin cash machine plunged 41.4% off its peak to close at a post-IPO low today, and why overseas desks misread CXMT's stock drop as a global memory warning.
On the surface, ChangXin Technology Group (SHA: 688825) closing down 5.61% at RMB 36.19 on November 17 (a RMB 2.45 trillion or $368 billion market cap, down from a post-listing high of RMB 61.80) looks alarming next to weak sessions in Micron ($MU), SK hynix (000660 KS), and Samsung Electronics (005930 KS). Yet CXMT's Q3 income statement and Q3 briefing Q&A expose two purely domestic equity leaks between fab-level cash generation and public A-share holders.
The first leak is a joint-venture minority-interest funnel. In Q3 2026, CXMT's revenue climbed 19.30% QoQ to RMB 118.71 billion ($17.81 billion) and consolidated net profit jumped 19.38% QoQ to RMB 88.98 billion ($13.35 billion), yet net profit attributable to parent shareholders edged up just 3.01% QoQ from RMB 52.84 billion to RMB 54.43 billion ($8.17 billion). Management explained in its Q3 briefing record that two subsidiary fabs, ChangXin Xinqiao in Hefei and ChangXin Jidian in Beijing, each grew revenue and profit by over 50% sequentially in Q3. Because local state and strategic co-investors funded early fab construction directly at the subsidiary level, CXMT holds lower equity stakes in those two fabs. Consequently, minority shareholders absorbed RMB 34.55 billion ($5.18 billion), or 38.83% of Q3 consolidated net profit, up 1,099 bps from 27.84% (RMB 29.94 billion) in 1H 2026. Even after recent parent capital injections into Beijing Jidian, nearly two-fifths of Q3 fab earnings bypassed public parent shareholders.
The second leak is a cavernous shareholder-return gap. CXMT generated RMB 254.75 billion ($38.22 billion) in nine-month operating cash flow and holds RMB 353.62 billion ($53.06 billion) in cash and trading financial assets. Questioned at today's November 17 briefing on initiating a dividend, Board Secretary Yuan Yuan reiterated that DRAM requires heavy capital and R&D reinvestment and that dividends remain under study in due course. Meanwhile, Chairman Zhu Yiming's upsized RMB 2.5 billion to 5.0 billion ($0.38 billion to $0.75 billion) buyback proposal equals just 0.10% to 0.20% of market cap, cannot begin until six months post-IPO in late January 2027, and earmarks up to 50% of repurchased shares for employee equity incentives, even as CXMT channels RMB 18.0 billion ($2.70 billion) of over-raised IPO funds into new R&D and Hefei back-end test facilities. By contrast, SK hynix committed roughly KRW 100 trillion ($74.7 billion, or at least 50% of free cash flow) to FY2026 dividends and share cancellations, and Samsung outlined KRW 90 trillion to 110 trillion ($67.3 billion to $82.2 billion) in 2026 shareholder returns.
CXMT's A-share derating prices in 38.8% subsidiary minority dilution and sub-0.2% capital returns at 11x annualized parent earnings, leaving its underlying 89.53% gross-margin DRAM fundamentals completely intact for global peers.


$MU $CXMT $SKHY
Technical disclosures from ChangXin Memory's Q3 2026 earnings briefings prove two critical facts for global DRAM supply: CXMT's 89.53% gross margin comes from DUV quad-patterning on planar 6F2, and its year-end 4F2 server DDR5 sampling will add less than 1.8% to 2027 global bit supply.
When ChangXin Technology Group (SHA: 688825) announced plans to sample 4F2 vertical-channel server DDR5 RDIMMs by year-end 2026 shortly after Micron ($MU) shelved 4F2 development, memory equities across New York, Seoul, and Taipei sold off on fears that Chinese architectural innovation had bypassed EUV export controls to flood the market. Reading CXMT's Q3 institutional briefing Q&A alongside President Cao Kanyu's remarks at today's November 17 Shanghai Stock Exchange Q3 briefing separates current fab economics from multi-year R&D milestones.
CXMT's current cash flow engine is its mass-produced 5th-generation (G5) planar platform. Using DUV quad-patterning to shrink active-area half-pitch without EUV lithography, G5 raised net dies per wafer by at least 50% over its 4th-generation node. That single-wafer productivity jump underpins CXMT's 24Gb-to-32Gb server DDR5 iteration (covering 5,600 to 8,000 Mbps RDIMMs up to 128GB and 12,800 Mbps MRDIMMs up to 192GB) as well as its 12,800 Mbps LPDDR6 lineup.
The divergence between Micron and CXMT on 4F2 reflects equipment access rather than an imminent supply wave. Armed with EUV systems, Micron, SK hynix (000660 KS), and Samsung Electronics (005930 KS) can scale conventional one-wafer 6F2 architectures through 1-gamma and 1c nodes (where Micron is already qualifying 8,800 MT/s RDIMMs and sampling 512GB modules) before adopting 4F2 around 2028. Lacking EUV, CXMT confirmed at today's briefing that its 6th-generation 4F2 platform combines self-developed vertical surrounding-gate (VSG) transistors with wafer-to-wafer hybrid bonding of separate logic and array wafers, shrinking unit cell area by 33.3% from 6F2 to 4F2 and targeting high-density server DDR5 first.
Supply math shows why year-end 2026 engineering samples will keep 2027 DRAM pricing tight. Hybrid wafer bonding consumes two silicon wafers per finished stack, faces sub-micron alignment yield hurdles where one defective wafer scraps the pair, and requires 6 to 12 months of server qualification. Even assuming a 12% global DRAM bit share for CXMT, supply modeling caps 4F2's incremental 2027 global bit addition at 0.05% in a conservative case, 0.30% in a base case, and 1.80% in an extreme full-yield case, against projected 2027 global bit growth of 24.10%. Meanwhile, TrendForce estimates HBM will absorb 30.0% of DRAM wafer starts at the Big Three by late 2027 (up from 22.0% exiting 2026) at roughly a 3-to-1 wafer trade ratio versus DDR5, while CXMT made zero mention of HBM across its Q3 report and both earnings briefings.
Dual-wafer hybrid bonding gives EUV-restricted CXMT a viable long-term path below 10nm, while Big Three HBM wafer allocation drains far more conventional DRAM capacity in 2027 than CXMT's early 4F2 ramp can replace.


$MU $CXMT $SKHY
Technical disclosures from ChangXin Memory's Q3 2026 earnings briefings prove two critical facts for global DRAM supply: CXMT's 89.53% gross margin comes from DUV quad-patterning on planar 6F2, and its year-end 4F2 server DDR5 sampling will add less than 1.8% to 2027 global bit supply.
When ChangXin Technology Group (SHA: 688825) announced plans to sample 4F2 vertical-channel server DDR5 RDIMMs by year-end 2026 shortly after Micron ($MU) shelved 4F2 development, memory equities across New York, Seoul, and Taipei sold off on fears that Chinese architectural innovation had bypassed EUV export controls to flood the market. Reading CXMT's Q3 institutional briefing Q&A alongside President Cao Kanyu's remarks at today's November 17 Shanghai Stock Exchange Q3 briefing separates current fab economics from multi-year R&D milestones.
CXMT's current cash flow engine is its mass-produced 5th-generation (G5) planar platform. Using DUV quad-patterning to shrink active-area half-pitch without EUV lithography, G5 raised net dies per wafer by at least 50% over its 4th-generation node. That single-wafer productivity jump underpins CXMT's 24Gb-to-32Gb server DDR5 iteration (covering 5,600 to 8,000 Mbps RDIMMs up to 128GB and 12,800 Mbps MRDIMMs up to 192GB) as well as its 12,800 Mbps LPDDR6 lineup.
The divergence between Micron and CXMT on 4F2 reflects equipment access rather than an imminent supply wave. Armed with EUV systems, Micron, SK hynix (000660 KS), and Samsung Electronics (005930 KS) can scale conventional one-wafer 6F2 architectures through 1-gamma and 1c nodes (where Micron is already qualifying 8,800 MT/s RDIMMs and sampling 512GB modules) before adopting 4F2 around 2028. Lacking EUV, CXMT confirmed at today's briefing that its 6th-generation 4F2 platform combines self-developed vertical surrounding-gate (VSG) transistors with wafer-to-wafer hybrid bonding of separate logic and array wafers, shrinking unit cell area by 33.3% from 6F2 to 4F2 and targeting high-density server DDR5 first.
Supply math shows why year-end 2026 engineering samples will keep 2027 DRAM pricing tight. Hybrid wafer bonding consumes two silicon wafers per finished stack, faces sub-micron alignment yield hurdles where one defective wafer scraps the pair, and requires 6 to 12 months of server qualification. Even assuming a 12% global DRAM bit share for CXMT, supply modeling caps 4F2's incremental 2027 global bit addition at 0.05% in a conservative case, 0.30% in a base case, and 1.80% in an extreme full-yield case, against projected 2027 global bit growth of 24.10%. Meanwhile, TrendForce estimates HBM will absorb 30.0% of DRAM wafer starts at the Big Three by late 2027 (up from 22.0% exiting 2026) at roughly a 3-to-1 wafer trade ratio versus DDR5, while CXMT made zero mention of HBM across its Q3 report and both earnings briefings.
Dual-wafer hybrid bonding gives EUV-restricted CXMT a viable long-term path below 10nm, while Big Three HBM wafer allocation drains far more conventional DRAM capacity in 2027 than CXMT's early 4F2 ramp can replace.
$MU $CXMT $SKHY
Disclosures from ChangXin Memory's Q3 2026 earnings briefings dismantle both of the bear theses currently compressing Micron ($MU) below 10x trailing earnings and pressuring South Korean memory leaders.
Across its filed Q3 institutional briefing record and today's November 17 Shanghai Stock Exchange Q3 earnings briefing, ChangXin Technology Group (SHA: 688825) addressed pricing and demand head-on. Overseas bears have long warned that rising Chinese DRAM capacity would trigger predatory discounting across standard DDR5 and mobile memory. Management confirmed the exact opposite: CXMT's product pricing sits roughly on par with overseas manufacturers, backed by an expanding server DDR5 revenue mix above 1H 2026's 46.22% share. That pricing discipline lifted CXMT's quarterly revenue from RMB 50.81 billion in Q1 to RMB 99.50 billion in Q2 and RMB 118.71 billion ($17.81 billion) in Q3, while consolidated gross margin climbed from 84.74% in 1H to 87.59% in Q2 and 89.53% in Q3. CFO Huang Danyang confirmed today that Q4 DRAM shortages remain intact and guided Q4 gross margin stable near ~89.5%.
CXMT's briefing readout also counters today's Seoul brokerage target-price cuts on SK hynix (000660 KS) and Samsung Electronics (005930 KS), which projected 2027 smartphone memory spec downgrades due to higher component costs. President Cao Kanyu reported at today's briefing that edge-AI memory growth across AI handsets, AI PCs, smart glasses, and autonomous vehicles is outpacing every other consumer vertical, while CXMT's 16Gb-die, 12,800 Mbps LPDDR6 (delivering 60% higher bandwidth at 20% lower power than LPDDR5X) has already entered commercial mass production on flagship foldables alongside Xiaomi's Xring O3 processor. On-device AI agents require wider bandwidth and larger resident DRAM pools, preventing flagship OEMs from cutting memory per handset even as budget consumer electronics stay soft.
Looking across primary Q3 filings for all four global DRAM producers, industry profitability and contract visibility are moving in lockstep. CXMT posted an 83.43% operating margin and confirmed active long-term supply agreement talks with top customers; Micron delivered an 80.70% GAAP operating margin on $54.23 billion in FQ4 revenue with $12.90 billion in noncurrent customer contract deposits; SK hynix achieved an 80.00% operating margin on KRW 104.62 trillion ($78.19 billion) in Q3 sales with over 50% of 2027 to 2028 output locked into five-year LTAs; and Samsung's Device Solutions semiconductor division earned a 72.40% operating margin on KRW 147.10 trillion ($109.94 billion) in Q3 revenue while targeting 60% to 70% multi-year contract coverage.
Four independent memory producers cannot simultaneously sustain 72% to 83% semiconductor operating margins and sign multi-year volume contracts in a market entering commodity oversupply.


$MU $CXMT $SKHY
Disclosures from ChangXin Memory's Q3 2026 earnings briefings dismantle both of the bear theses currently compressing Micron ($MU) below 10x trailing earnings and pressuring South Korean memory leaders.
Across its filed Q3 institutional briefing record and today's November 17 Shanghai Stock Exchange Q3 earnings briefing, ChangXin Technology Group (SHA: 688825) addressed pricing and demand head-on. Overseas bears have long warned that rising Chinese DRAM capacity would trigger predatory discounting across standard DDR5 and mobile memory. Management confirmed the exact opposite: CXMT's product pricing sits roughly on par with overseas manufacturers, backed by an expanding server DDR5 revenue mix above 1H 2026's 46.22% share. That pricing discipline lifted CXMT's quarterly revenue from RMB 50.81 billion in Q1 to RMB 99.50 billion in Q2 and RMB 118.71 billion ($17.81 billion) in Q3, while consolidated gross margin climbed from 84.74% in 1H to 87.59% in Q2 and 89.53% in Q3. CFO Huang Danyang confirmed today that Q4 DRAM shortages remain intact and guided Q4 gross margin stable near ~89.5%.
CXMT's briefing readout also counters today's Seoul brokerage target-price cuts on SK hynix (000660 KS) and Samsung Electronics (005930 KS), which projected 2027 smartphone memory spec downgrades due to higher component costs. President Cao Kanyu reported at today's briefing that edge-AI memory growth across AI handsets, AI PCs, smart glasses, and autonomous vehicles is outpacing every other consumer vertical, while CXMT's 16Gb-die, 12,800 Mbps LPDDR6 (delivering 60% higher bandwidth at 20% lower power than LPDDR5X) has already entered commercial mass production on flagship foldables alongside Xiaomi's Xring O3 processor. On-device AI agents require wider bandwidth and larger resident DRAM pools, preventing flagship OEMs from cutting memory per handset even as budget consumer electronics stay soft.
Looking across primary Q3 filings for all four global DRAM producers, industry profitability and contract visibility are moving in lockstep. CXMT posted an 83.43% operating margin and confirmed active long-term supply agreement talks with top customers; Micron delivered an 80.70% GAAP operating margin on $54.23 billion in FQ4 revenue with $12.90 billion in noncurrent customer contract deposits; SK hynix achieved an 80.00% operating margin on KRW 104.62 trillion ($78.19 billion) in Q3 sales with over 50% of 2027 to 2028 output locked into five-year LTAs; and Samsung's Device Solutions semiconductor division earned a 72.40% operating margin on KRW 147.10 trillion ($109.94 billion) in Q3 revenue while targeting 60% to 70% multi-year contract coverage.
Four independent memory producers cannot simultaneously sustain 72% to 83% semiconductor operating margins and sign multi-year volume contracts in a market entering commodity oversupply.
$MU $CXMT $SKHY
An EUV-restricted Chinese DRAM maker just printed $17.81 billion in single-quarter revenue at an 89.53% gross margin and confirmed today that Q4 shortages and margins are holding firm, while global memory equities trade as if the cycle already peaked.
At today's November 17 Shanghai Stock Exchange Q3 earnings briefing, combined with its filed Q3 institutional briefing record, ChangXin Memory Technologies parent ChangXin Technology Group (SHA: 688825) laid out a financial reality most Western semiconductor desks have yet to translate. In Q3 2026, CXMT crossed RMB 100 billion in quarterly revenue for the first time at RMB 118.71 billion ($17.81 billion, up 19.30% QoQ and 613.18% YoY). Consolidated gross margin climbed another 194 bps sequentially to 89.53%, lifting operating margin to a record 83.43% and consolidated net profit to RMB 88.98 billion ($13.35 billion). Single-quarter operating cash flow surged nearly 40% QoQ to RMB 123.60 billion ($18.55 billion), pushing nine-month operating cash flow to RMB 254.75 billion ($38.22 billion) against just RMB 37.00 billion ($5.55 billion) in capital expenditure cash outflows. CXMT exited September with RMB 353.62 billion ($53.06 billion) in cash and trading financial assets and a 36.34% debt-to-asset ratio.
Management's operational readout today was equally unambiguous. CFO Huang Danyang guided Q4 2026 DRAM supply shortages to persist and gross margin to remain stable near Q3's ~89.5% plateau as utilization and yields rise across its three 12-inch fabs in Hefei and Beijing. President Cao Kanyu confirmed ongoing long-term supply agreement negotiations with top-tier customers, sustained server DDR5 undersupply, mass production of 12,800 Mbps LPDDR6 (delivering 60% higher bandwidth at 20% lower power than LPDDR5X) alongside AEC-Q100 Grade 2 automotive LPDDR5X, and server-first deployment for its next-generation 4F2 vertical-channel architecture, with zero mention of HBM throughout the filings and briefing.
[Insert Table: cxmt_q3_2026_briefing_scorecard.png]
Yet tape action across four markets tells a sharply disconnected story: Micron ($MU) trades below 10x trailing earnings around $720 to $734 after yesterday's 7.46% drop, SK hynix (000660 KS) and Samsung Electronics (005930 KS) slid 1.96% and 3.30% in Seoul today after brokerage target cuts warning of 2027 smartphone memory spec downgrades, and CXMT itself fell 5.61% today to a post-IPO closing low of RMB 36.19 (RMB 2.45 trillion or $368 billion market cap).
Over our next three standalone notes dissecting conclusions directly from CXMT's Q3 earnings briefings, we will unpack three structural realities behind these numbers. Part 1 examines why CXMT's confirmed parity pricing with overseas peers, server DDR5 mix shift, LTA lock-ins, and accelerating edge-AI LPDDR6 demand invalidate both the Chinese price-dumping narrative and South Korean brokerages' 2027 smartphone spec-downgrade call. Part 2 breaks down how CXMT achieved a 50%+ die-per-wafer jump via DUV quad-patterning on its 5th-generation node without EUV and why year-end sampling of its dual-wafer hybrid-bonded 4F2 server DDR5 RDIMMs adds well under 2% to 2027 global bit supply after Micron walked away from 4F2. Part 3 traces why an 89.53% gross-margin cash machine sank 41.4% from its post-listing peak, exposing the RMB 34.55 billion single-quarter minority-interest leakage at its joint-venture fabs and a RMB 2.5 billion to 5.0 billion buyback plan worth under 0.2% of market value.
Global memory stocks are pricing in an imminent commodity bust on the exact same day the world's fourth-largest DRAM producer confirmed nearly 90% gross margins and unbroken Q4 supply deficits.

$MU $CXMT $SKHY
An EUV-restricted Chinese DRAM maker just printed $17.81 billion in single-quarter revenue at an 89.53% gross margin and confirmed today that Q4 shortages and margins are holding firm, while global memory equities trade as if the cycle already peaked.
At today's November 17 Shanghai Stock Exchange Q3 earnings briefing, combined with its filed Q3 institutional briefing record, ChangXin Memory Technologies parent ChangXin Technology Group (SHA: 688825) laid out a financial reality most Western semiconductor desks have yet to translate. In Q3 2026, CXMT crossed RMB 100 billion in quarterly revenue for the first time at RMB 118.71 billion ($17.81 billion, up 19.30% QoQ and 613.18% YoY). Consolidated gross margin climbed another 194 bps sequentially to 89.53%, lifting operating margin to a record 83.43% and consolidated net profit to RMB 88.98 billion ($13.35 billion). Single-quarter operating cash flow surged nearly 40% QoQ to RMB 123.60 billion ($18.55 billion), pushing nine-month operating cash flow to RMB 254.75 billion ($38.22 billion) against just RMB 37.00 billion ($5.55 billion) in capital expenditure cash outflows. CXMT exited September with RMB 353.62 billion ($53.06 billion) in cash and trading financial assets and a 36.34% debt-to-asset ratio.
Management's operational readout today was equally unambiguous. CFO Huang Danyang guided Q4 2026 DRAM supply shortages to persist and gross margin to remain stable near Q3's ~89.5% plateau as utilization and yields rise across its three 12-inch fabs in Hefei and Beijing. President Cao Kanyu confirmed ongoing long-term supply agreement negotiations with top-tier customers, sustained server DDR5 undersupply, mass production of 12,800 Mbps LPDDR6 (delivering 60% higher bandwidth at 20% lower power than LPDDR5X) alongside AEC-Q100 Grade 2 automotive LPDDR5X, and server-first deployment for its next-generation 4F2 vertical-channel architecture, with zero mention of HBM throughout the filings and briefing.
[Insert Table: cxmt_q3_2026_briefing_scorecard.png]
Yet tape action across four markets tells a sharply disconnected story: Micron ($MU) trades below 10x trailing earnings around $720 to $734 after yesterday's 7.46% drop, SK hynix (000660 KS) and Samsung Electronics (005930 KS) slid 1.96% and 3.30% in Seoul today after brokerage target cuts warning of 2027 smartphone memory spec downgrades, and CXMT itself fell 5.61% today to a post-IPO closing low of RMB 36.19 (RMB 2.45 trillion or $368 billion market cap).
Over our next three standalone notes dissecting conclusions directly from CXMT's Q3 earnings briefings, we will unpack three structural realities behind these numbers. Part 1 examines why CXMT's confirmed parity pricing with overseas peers, server DDR5 mix shift, LTA lock-ins, and accelerating edge-AI LPDDR6 demand invalidate both the Chinese price-dumping narrative and South Korean brokerages' 2027 smartphone spec-downgrade call. Part 2 breaks down how CXMT achieved a 50%+ die-per-wafer jump via DUV quad-patterning on its 5th-generation node without EUV and why year-end sampling of its dual-wafer hybrid-bonded 4F2 server DDR5 RDIMMs adds well under 2% to 2027 global bit supply after Micron walked away from 4F2. Part 3 traces why an 89.53% gross-margin cash machine sank 41.4% from its post-listing peak, exposing the RMB 34.55 billion single-quarter minority-interest leakage at its joint-venture fabs and a RMB 2.5 billion to 5.0 billion buyback plan worth under 0.2% of market value.
Global memory stocks are pricing in an imminent commodity bust on the exact same day the world's fourth-largest DRAM producer confirmed nearly 90% gross margins and unbroken Q4 supply deficits.