

Stock market research. AI / data centers / power infra / cloud compute. NFA
Miami, FL
Joined February 2021
- Tweets6.4K
- Following317
- Followers35.1K
- Likes25K




Pinned Tweet
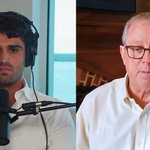
The Silicon Stack Podcast | Ep. 2 Featuring @PaulBPrager
I sat down with $WULF CEO Paul Prager. The Naval Academy grad who has transformed TeraWulf into one of the fastest-growing pure-play AI/HPC data center platforms in the U.S.
We discuss:
• The 20-year Anthropic deal
• Statewide data center moratoriums
• Power generation (BTM & FTM)
• Overseas expansion plans

Small Cap Snipa retweeted

𝗪𝗲𝗹𝗹𝘀 𝗙𝗮𝗿𝗴𝗼 $315 𝗳𝗿𝗮𝗺𝗲𝘀 𝘁𝗵𝗲 $NVDA 𝘂𝗽𝘀𝗶𝗱𝗲 𝗶𝗻𝘁𝗼 2027 𝗮𝘀 𝗮 𝘀𝘂𝗽𝗽𝗹𝘆 𝗾𝘂𝗲𝘀𝘁𝗶𝗼𝗻.
Every GTC Berlin item the note lists adds capacity somewhere in the chain:
1. Substrates
2. Advanced packaging
3. Test
4. Optics for co-packaged links
$SPCX is one buyer asking for 10 GW next year, Nvidia only. That is close to half of what Wells has Nvidia shipping in 2027.
My guess is that gives Nvidia the say over who gets Vera Rubin first, and pricing holds through 2027.


Wells Fargo sees $NVDA shipping ~23 GW of AI infrastructure capacity in CY27 / FY28: $315 PT
Vera Rubin supply chain is 2x that of Grace Blackwell and can assemble a VR rack in 5 minutes today vs two hours previously.

Wells Fargo sees $NVDA shipping ~23 GW of AI infrastructure capacity in CY27 / FY28: $315 PT
Vera Rubin supply chain is 2x that of Grace Blackwell and can assemble a VR rack in 5 minutes today vs two hours previously.
NEOCLOUD / HPC EXPERT CALLS:
I’ve started sourcing expert calls with current and former VPs and directors across neoclouds, hyperscalers, and the broader AI ecosystem.
Focus areas: $NBIS, $CRWV, $SPCX, $NVDA, $MSFT, $IREN, Crusoe, Nscale + more.
I’ll post transcript snippets here and walk through the full calls on spaces Saturday evenings. My real-world job is picking up, which I’m very grateful for, so this is how I’m keeping the high-alpha notes flowing without needing to be online 24/7.
If you’re interested in this, follow and DM me. My DMs are always open if you want to connect or have something relevant.
Looking forward to getting these out!
$IREN to advance Europes sovereign AI ambitions with 300 MW Spanish campus
Planned 300MW Badajoz campus provides foundation for European AI Cloud capacity; initial operations targeted for 2028

$NBIS introduced public live pricing for GPU spot computing capacity, expanding its pricing options for AI developers
• Expands AI Builder Program to Europe with NVIDIA to accelerate European AI development
• Live prices are available on its website and through Shadeform, Silicon Data and GPU Finder.
• Other options include reserve auctions for short-term capacity blocks and pay-as-you-go access without fixed-term reservations.
• Nebius is also piloting a capacity-rebate program that lets customers recover value by returning idle GPUs to the spot pool.

Morningstar cuts Neocloud price targets on financing risk:
$CRWV: $108 from $115
$NBIS: $150 maintained
$IREN: $37 from $43
“Despite similar business risk, Nebius' balance sheet is stronger, (CoreWeave) with minimal net debt. Nebius has correctly used its high valuation to raise capital through equity and convertibles but needs to keep its share price elevated to maintain lower financial leverage than its peers.”
Bottom line from the note: cheap capital is essential to the trillion-dollar AI buildout, but rising leverage and credit stress are now material risks.

BofA: Data center additions ramp hard from 13 GW in 2025 to ~56 GW by 2030E:
The industry is expected to add 212 GW of cumulative incremental capacity between 2026-2030
Nvidia still the core of the stack but custom silicon like is scaling aggressively alongside AMD and others
$NVIDIA $GOOGL $META $MSFT $AMZN $AMD

The bots are absolutely insane lately, damn. Please do not fall for any of these scamming bots. This is my only account and I’ll never reach out to sell anything.
There are 13 quote tweets from bots on this post and it has been happening on every post lately. @elonmusk @nikitabier
JP. MORGAN ON CONTRACT ECONOMICS & GPU USEFUL LIFE:
Contract economics generate residual cash flow to the parent, with GPU useful lives extending the optionality beyond the contract term.
As laid out in the $CRWV illustrative contract cash flow, a 5-year contract with capex of ~51% of total contract value, funded ~80% by asset-level debt, generates residual cash flow to the parent of ~16% of contract value after full repayment of the asset-level debt, sufficient to cover ~5 years of data center obligations even if the capacity is not re-contracted.
We view the illustrative economics as conservative, as the useful lives of GPUs are currently extending beyond both the 6-year depreciation schedule and the contract term, as evidenced by observed in-market usage of ~8 years on V100 and ~7 years on T4 and the A100 contract signed into 2029 on a SKU introduced in 2020, positioning CoreWeave to earn cash flow beyond the contract term with only lease and power costs to cover once the asset-level debt is repaid.
$SPCX $NBIS $IREN
$WULF CEO Paul Prager on the stock price:
“My focus is entirely on creating long-term value for shareholders and execution.”
• He doesn’t react to day-to-day moves
• He’s the largest shareholder
• The balance sheet is a “fortress”
• CFO Patrick Fleury paid tax on vested RSUs instead of selling
“As long as I can execute and explain it to shareholders, we will win.”
@PaulBPrager agreed to join the podcast fresh off the Anthropic deal and earnings. He had no idea who I was, still did a full hour, and then stayed an extra 15 minutes off camera just to shoot the shit. 100% one of the good guys in this space and I am rooting for him. You can watch the full convo here or in my pinned tweet.
youtu.be/CCAhWyNCnCg?is=FD35…

BofA sees $CRWV becoming a 4.8 GW business generating $43.3B of revenue by YE28 👀
Nvidia’s Vera Rubin is expected to become a larger portion of capacity beginning in 2027, leading to a step-up in monetization relative to current-generation deployments (GB200, GB300, H100, H200, etc).
“Under our assumptions, initial Vera Rubin contracts that were likely signed early in 2026 generate approximately $12/watt annually, with pricing gradually increasing to $14/watt annually by the end of 2028.”


Hyperscalers and neoclouds are paving a path to ~125 GW by year end 2028 (4x in compute capacity vs 2025)
Morgan Stanley is bullish on the spend and attractive ROIC (25-50%) ahead in the age of inference:
$SPCX $NBIS $CRWV $AMZN $GOOGL $META $MSFT


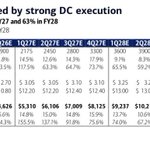
JP MORGAN: “WE BELIEVE THE CURRENT CONCERNS ON $CRWV ARE OVERDONE RELATIVE TO THE FUNDAMENTALS”
1. Datacenter demand is robust and has improved in recent months, rather than moderated, providing limited datapoints to support long-term datacenter demand concerns.
2. Bringing capacity online is materially tougher than the linear progression in relation to conversion of published contracted capacity to active capacity, and CoreWeave's execution leadership on this front has consistently stood out in our customer conversations.
3. Economics at a project level remain sound with the company positioned to generate both healthy margins and returns on cash flow, despite initial investment focus driving some temporary margin and cash flow hurdles.
4. Beyond the sound economics on a project for a typical 5-year contract agreement, there is an additional monetization lever in recontracting GPUs beyond the 5-year duration.
5. Project level returns (unlevered IRR) exceed cost of capital for the company.


