Pinned Tweet
Surge Battery Metals Corporate Presentation
(TSX-V: $NILI.v | OTCQX: $NILIF)
- Updated MRE; 10.51 Mt LCE M&I @ 3,007 ppm Li
- PEA: US$9.17B NPV, 22.8% IRR, over 42 years
- JV with Evolution Mining ($EVN)
- PFS led by Fluor Corporation (Q4 2026)
surgebatterymetals.com/inves…

"This is an American asset… a tier one resource asset."
Brian Paes-Braga, co-lead of Surge Battery Metals' Strategic Advisory Board, on the Nevada North Lithium Project.
→ 4.56 Mt LCE Mineral Reserve
→ 3,928 ppm Li Mineral Reserve grade
→ 42-year mine life
→ ~92,250 tpa average annual production
surgebatterymetals.com
Views expressed are his own; Mr. Paes-Braga co-led the Company's June 2026 strategic financing.
$NILI.V $NILIF
Chinese lithium carbonate inventories below 3 weeks of supply are another clear signal that the surplus is gone and the market is tightening.
This is exactly why new, high-grade domestic supply matters. Nevada North is advancing a 3,928 ppm Li mineral reserve with a 42-year mine plan, life-of-mine operating costs of US$4,719/t carbonate, and an after-tax NPV of US$9.81B.
Secure North American production is needed as inventories draw and EV + storage demand continues to grow.
Make sure to follow @matt_fernley for your Lithium Analysis.
$NILI.V $NILIF


What drives the economics at Nevada North:
→ 3,928 ppm Li Mineral Reserve grade
→ 0.88:1 strip ratio
Together they drive a life-of-mine operating cost of US$4,719 per tonne of lithium carbonate, an after-tax NPV of US$9.81 billion at an 8% discount rate, a 23.6% after-tax IRR, and a 4.2-year payback from the start of production.
$NILI.V $NILIF
Surge Chairman Graham Harris on U.S. lithium supply and demand.
→ Global lithium consumption up 20% in 2025 (est.), to 263,000 tonnes
→ One commercial-scale U.S. lithium producer, in Nevada
→ U.S. net import reliance above 50%, with imports led by Chile and Argentina
Source: USGS Mineral Commodity Summaries 2026
Full interview on the Rock Stock Channel YouTube.
$NILI.V $NILIF
It’s crazy how hard lithium equities have been hit recently. Short-term price weakness and negative sentiment have dominated the tape. But the macro case for lithium has never been clearer or more important.
Gasoline-only cars just fell below 50% of global new vehicle sales for the first time in history. That’s a structural inflection point. BEVs reached about 17% and hybrids about 18% in the first half of 2026, and the trend is accelerating. As @elonmusk noted, almost all cars will be electric in the future. Every one of those vehicles needs lithium in its battery.
EVs remain the dominant demand driver for lithium, with energy storage adding a second major growth vector. Near-term market noise does not change the long-term requirement for new, scalable, high-quality supply, especially from reliable jurisdictions.
That’s why projects like Nevada North matter. Our PFS outlines a high-grade (3,928 ppm Li reserve), long-life (42 years) path to battery-grade lithium carbonate at competitive costs (US$4,719/t), with an after-tax NPV of US$9.81B and 23.6% IRR. Domestic North American supply is needed as the electrification transition scales.
The equity reaction is disconnected from the fundamentals of demand growth. The macro still points one way.
$NILI.V $NILIF

Grade. Scale. Jurisdiction.
Brian Paes-Braga on the Nevada North Lithium Project:
→ 3,928 ppm Li Mineral Reserve grade
→ 10.5 Mt LCE Measured & Indicated Resource
→ Elko County, Nevada
Full interview: youtube.com/watch?v=WE0Nn_Rf…
$NILI.V $NILIF
The PFS puts overall lithium recovery at 84.9%, up from 82.8% in the 2025 PEA. Mineral Reserve grade is 3,928 ppm Li, with ~4,340 ppm Li processed over the first ten years.
Full interview: youtube.com/watch?v=Bxy_m29g…
$NILI.V $NILIF
Thank you to @RKEquityRocks, @LithiumIonBull and @matt_fernley for the detailed discussion on the Nevada North PFS.
Graham Harris and Iain Scarr walk through the higher-grade resource, reduced Phase 1 CapEx, 84.9% recovery, and the clearer path into feasibility that builds on the work already advancing at NNLP.
$NILI.V $NILIF

.@SurgeBattery's Nevada North PFS strengthens the second-mover case behind Thacker Pass: higher grade, lower phase-one CapEx, 85% recovery and a clearer path into feasibility.
Graham Harris and Iain Scarr join us to discuss what comes next.👇 $NILI.V
(00:00) Nevada North PFS Sets The Stakes
(04:11) Why Phase One CapEx Fell
(05:18) US Lithium Demand Supports Scale
(06:59) Recovery Gains Face Scale-Up Test
(12:39) Sulphur Costs Show Limited Sensitivity
(15:08) Solid-Liquid Separation Is Key Risk
(16:16) High-Grade Clay Narrows Cost Gap
(21:50) Thacker Pass Creates Second-Mover Advantage
(23:19) Strategic Capital Opens Funding Path
(24:56) Experienced Team Supports Execution
Lithium sentiment has turned overly negative, but the numbers say otherwise. @D_Jimenez_Sch breaks it down cleanly: China’s battery production through August already equates to ~400kt LCE of incremental demand vs last year, tracking toward at least +500kt for full-year 2026. Supply growth from major exporters is only tracking ~300kt LCE. That leaves a ~200kt deficit, with inventory drawdowns already underway.
This is the backdrop for why high-grade domestic projects matter. Surge’s Nevada North PFS shows a path to battery-grade lithium carbonate at competitive costs (US$4,719/t), with a 42-year mine life and strong economics. New North American supply is needed precisely when the market is tightening.
$NILI.V $NILIF

Sentiment on lithium has turned very negative, mostly on the back of unrelated bits of information. So let's talk numbers, not opinions. What do we actually know?
Demand. The hard data: China's battery production through August 2026 is up the equivalent of ~400kt LCE vs last year. If we carry only part of that growth through to year-end, Chinese batteries alone add at least ~500kt LCE of demand vs 2025.
Supply. Here the only hard data is exporters' trade statistics. Change vs 2025, in kt LCE (YTD Aug → full-year 2026F):
🇦🇺 Australia: +30 → +60
🇨🇱 Chile: +70 → +50
🇦🇷 Argentina: +30 → +65
🇧🇷 Brazil: -10 → -15
🌍 Africa: +50 → +65
🇨🇦 Canada: 0 → 0
🇨🇳 China: +40 → +70 (the softest number)
Total: +210 → ~+295
Even after adding the production that projects and producers have announced, 2026 supply growth comes to roughly 300kt. It's not much more than that. It can't be much more than that.
So for 2026:
Demand: +500kt
Supply: ~+300kt
Balance: a deficit of ~200kt LCE
The deficit is already here.
2027? The bears say demand will pull back. That's much harder to agree or disagree with. But the inventory drawdown happening right now will clearly push the market into deficit.
Figures and views are iLiMarkets' assessment.
The Nevada North Lithium Project PFS, broken down by @LithiumIonBull on @RKEquityRocks: after-tax NPV8% of US$9.81B, 23.6% IRR, and how capital, costs and recovery compare with the 2025 PEA.
Full interview: youtube.com/watch?v=Bxy_m29g…
$NILI.V $NILIF

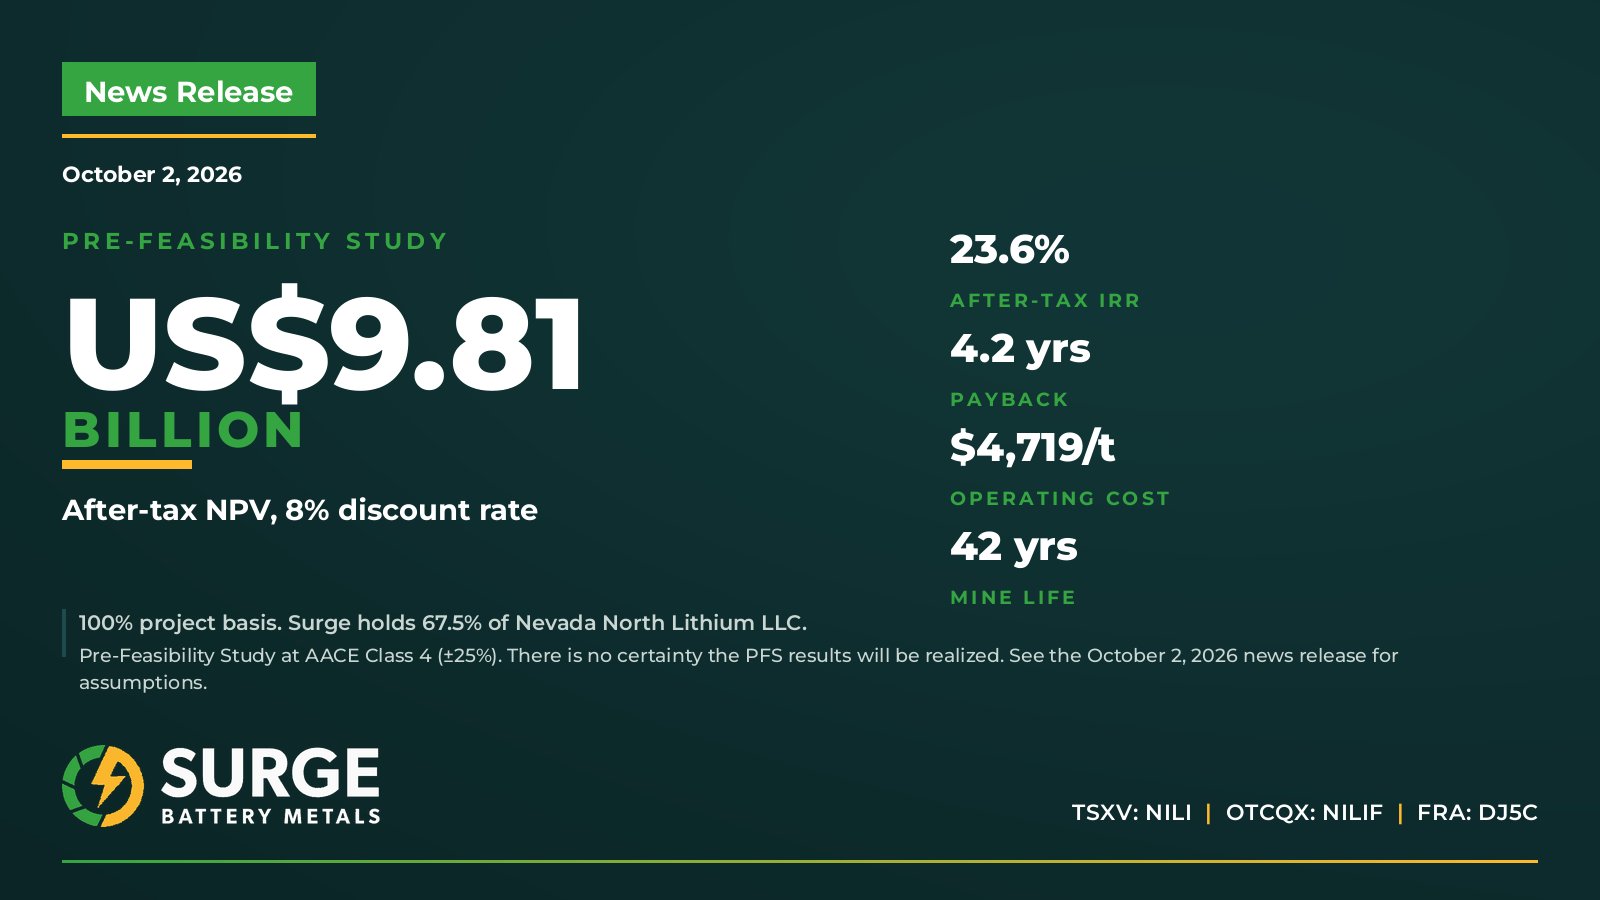
Surge Announces Positive Pre-Feasibility Study at Nevada North: After-Tax NPV8% of US$9.81 Billion, After-Tax IRR of 23.6% and Operating Cost of US$4,719/tonne Lithium Carbonate
PFS improves on 2025 PEA with lower Phase 1 capital, lower operating cost, higher recovery and a faster 4.2-year payback over a 42-year mine life
🔗: surgebatterymetals.com/news
🇨🇦 $NILI.V | 🇺🇸 $NILIF | 🇩🇪 #DJ5C