

Long-Term Investor | Focus on Quality Fundamental Analyses and Insights | Join 5000+ readers: https://xitter.cf/t.co/XZyrRNCFMg | https://xitter.cf/t.co/hbCC9qnITA
Joined January 2022
- Tweets18.9K
- Following283
- Followers38.8K
- Likes41.5K




Pinned Tweet
🙌Time for celebration! 🙌
It's been exactly one year since my Substack launch!
I'm very proud and happy with what I have achieved since then.
Not just growth-wise, but also the quality of my articles and deep dives. With every word I wrote down, I became a better investor and writer.
And probably most importantly, I've met a ton of great smart people, both on SS and here on X. Surrounding myself with other great investor is invaluable.
If you like what I do here, you're certainly gonna like what I do over there. Just a quick summary of what I do:
I'm most proud of my deep dives, which I believe to have greatly improved in quality over the past year.
Amongst others, I have covered $ASML, $NVO, $CSU, $DLO, $KRKNF, $LLY, $TMDX. ($TSM deep dive coming soon).
But I do a lot more: I build valuation models for companies in my portfolio and on my watchlist, write about important things I see in the market, and send out a monthly portfolio update.
I also give live updates on my buys/sells, and you can track how well those updates have performed since then.
I want to thank everyone who has already joined me on my journey there. If you haven't, you can find a direct link to the Substack in my bio.
I know it came at a cost. I haven't posted as much and as high quality as I used to do on X. But since I became a father I just don't really have the time.
Special thanks to some of the great guys that I've been interacting with on both platforms. Make sure to follow them here on X and on Substack as well:
@TheBigBerbowski
@SixSigmaCapital
@GabGrowth
@jimmyinvest
@jpinsights
@pequityresearch
@meeijer
@TheRayMyers
@mvcinvesting
@babyfolio
@rebound_capital
@ManuInvests
@glocalinvestor
@ThierryBorgeat
@bdinvestingg
@DD17_Capital
@WealthyReadings
@euro__stocks
@crux_capital_
TacticzHazel retweeted

Significant beat for SK Hynix:
🔹 Revenue: $78.9B (Est. $74.8B) 🟢; +328% YoY
🔹 Oper Profit: $62.8B (Est. $58.5B) 🟢; +632% YoY
🔹 Oper Margin: 80%; +3,300 bps YoY; record high
🔹 QoQ: Revenue +32% / Oper Profit +38%
$SKHY

SK HYNIX $SKHY Q3’26 EARNINGS HIGHLIGHTS
🔹 Revenue: $78.9B (Est. $74.8B) 🟢; +328% YoY
🔹 Oper Profit: $62.8B (Est. $58.5B) 🟢; +632% YoY
🔹 Oper Margin: 80%; +3,300 bps YoY; record high
🔹 QoQ: Revenue +32% / Oper Profit +38%
Q4 Guide:
🔹 DRAM Bit Growth: Mid-20% QoQ
🔹 NAND Bit Growth: Mid-single% QoQ incl. Solidigm
Q3 Pricing & Volume:
🔹 DRAM ASP: High-20% QoQ; bits ~+10% QoQ
🔹 NAND ASP: Mid-20% QoQ; bits slightly lower QoQ
Profitability:
🔹 Gross Margin: 85.7% (Est. 85.2%) 🟢
🔹 EBITDA: $66.1B; 84% margin; +486% YoY
🔹 EPS: $41.07; +205% YoY
Financials:
🔹 Cash: $86.3B; +311% YoY
🔹 Interest-Bearing Debt: $11.9B; -34% YoY
🔹 Net Debt-to-Equity: -32%; -2,800 bps YoY
🔹 Operating Cash Flow: $41.3B; +281% YoY
🔹 Total Assets: $295.5B
2027 Market Outlook:
🔹 DRAM Demand Bit Growth: +mid-20% YoY
🔹 NAND Demand Bit Growth: +high-teens% YoY
🔹 2027 CapEx: To rise significantly vs 2026
🔸 Memory demand expected to outpace supply through 2030
Product & Technology:
🔹 HBM4: Expected to surpass HBM3E in HBM shipment and revenue share in Q4
🔹 2027 HBM: Negotiations finalized; profitability gap with conventional DRAM expected to narrow meaningfully
🔹 M15X: Ramp-up accelerating to full capacity by end-2026
🔹 321L NAND: Over 50% of domestic capacity in Q4
Business Highlights:
🔹 LTAs: Signed with 14 key customers incl. major global CSPs; standard 5-year term; over 50% of 2027-2028 capacity secured
🔹 Q3 Dividend: ~₩20,000/share (~$15.08), incl. a ₩10,000 special dividend from realized Kioxia gains
🔹 Share Acquisition: ₩20T (~$15.1B) for the quarter, incl. ~₩10T for executive & employee compensation
🔸 Quarterly revenue topped ₩100T for the first time
Note:
🔹 Net Profit: $30.0B; +216% YoY
🔸 Includes a $24.6B non-operating loss: a $17.3B investment-asset loss and an $8.8B FX loss as the won strengthened
FX used for USD conversion: $1 = ₩1,326 (mid-market; Oct 27, 2026)

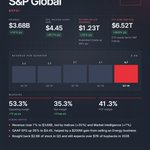
$SPGI just reported earnings.
Overall very solid, exactly what you might expect from this ''boring compounder''.
REV: $3.68B (+7% YoY)
EPS: $4.58 (+9% YoY)
Price is up 4% in premarket.

TacticzHazel retweeted
$NU is down 25% premarket. What a mess.
Double whammy: CTO Eric Young resigning + the Lula effect.
While $NU personally isn't for me, I am deeply impressed with the company, especially the CEO.
I like to invest alongside a strong CEO/Management team, and $NU has one of the best CEO's in the world if you ask me.
Want to learn more about him?
This podcast will you give you a great insight into his mind and thinking.
youtube.com/watch?v=npVZsYao…

TacticzHazel retweeted

The conclusion people are drawing from this comment is bearish for Neoclouds and the entire AI sector, judging by the replies. But this guy is currently building 10 GW of compute capacity. At the very least, that should make people take a closer look at what he’s actually saying.
It’s not the compute capacity in the “partially” completed data centers that’s useless. It’s useless because those facilities don’t have access to power.
SpaceX’s biggest edge right now isn’t that it has secured more GPUs or other compute hardware than anyone else. It’s that they’ve been remarkably effective at sourcing turbines and other power generation equipment at scale.
But energy isn’t the only missing piece that can bring an almost-completed data center online.
We’ve been reading about supply chain bottlenecks for the past 10 months, yet the biggest bottleneck remains getting the context in place.

TacticzHazel retweeted

Hello everyone, our $NUAI deep dive is now live on Substack
A tenant + financing is the major catalyst. Which we expect soon. But what would the deal actually be worth to shareholders? That’s the groundwork we’ve laid in this report.
We start with management hires and the roles they play, followed by a full site breakdown, power availability, and the sector’s tailwinds and headwinds.
We walk through permitting: what has been secured, what remains outstanding, and how requirements differ across the development phases. This ties into @Mark_AAIG technical series, which I’ll also link in the comments.
We then examine different financing scenarios for Phase 1 and Phase 2, showing how funding structures, ownership and potential dilution change the economics for shareholders.
Together, this builds a foundation for understanding the full campus and its planned 1.4 GW of gross capacity. As tenant and financing details emerge, we can quickly reassess the investment case: how much capacity is contracted, on what terms, what it costs to deliver, and how much value ultimately accrues to NUAI shareholders.
Ask us questions, challenge our assumptions, or discuss the report in the Substack subscriber chat. You can also connect to our Discord and join the dedicated NUAI deep-dive channel.
Write-up and technical series in the comments 👇
Team AAIG

TacticzHazel retweeted

$NBIS: A Great Business or a Great Story?
I’ve spent a considerable amount of time thinking about $NBIS, particularly after reading some of the extraordinarily optimistic projections circulating on X. There’s no shortage of people explaining how many gigawatts the company might operate, how much revenue those gigawatts could generate, or why the stock is supposedly trading at some ridiculously low multiple of future sales. I understand the excitement, and frankly, I admire what management has accomplished in a relatively short period of time. But I think there’s a much more interesting conversation to be had, one that goes considerably deeper than revenue projections, capacity announcements, and the usual arguments about how enormous the AI opportunity will become.
Let me make something clear from the beginning. I’m not suggesting $NBIS is a bad investment, that its ambitions are unrealistic, or that its shareholders won’t make substantial amounts of money. In fact, it’s entirely possible that the company becomes enormously successful and today’s valuation turns out to be attractive. What interests me is something much more fundamental: the difference between successfully building an extraordinary business and capturing an extraordinary share of the economic value that business helps create.
There’s a tendency among investors to assume that the more important an industry becomes, the more valuable the companies operating within it must become. It sounds perfectly logical, and sometimes it turns out to be true. But economic history suggests something considerably more complicated, because the industries that transform civilization aren’t necessarily the industries that provide the greatest returns to their investors. Sometimes the enormous value created by an innovation flows primarily to customers rather than to the companies responsible for delivering it.
And this brings me to the first question I would ask about $NBIS. If artificial intelligence becomes dramatically more powerful, computing capacity becomes increasingly abundant, and the cost of intelligence falls by 90% over the next decade, who actually captures the resulting economic value? Is it the infrastructure providers, the chip manufacturers, the businesses developing AI applications, or the millions of companies that suddenly become far more productive? I suspect the answer will be distributed very unevenly, and understanding that distribution might be considerably more important than forecasting how many gigawatts the industry eventually operates.
Consider something fascinating about technological progress. When a product becomes dramatically cheaper, the amount consumed can increase enormously, sometimes by orders of magnitude. But an explosion in consumption doesn’t necessarily mean an explosion in profits for the companies supplying that product. In certain industries, the very process that makes the technology indispensable also makes it increasingly difficult for suppliers to maintain exceptional pricing power.
Imagine computing demand increases tenfold over the next decade while the revenue earned per unit of useful computing falls by 80%. The industry would experience an extraordinary technological expansion, yet revenue per comparable unit of demand would have compressed dramatically. Total industry revenue could still double under those assumptions, but whether profits increased would depend on the costs of supplying that additional capacity. This is an illustration, not a forecast, but it highlights why demand growth and shareholder returns are two very different things.
1/👇
TacticzHazel retweeted
$ASML is not expensive right now.
Forward PE: 24
Forward EV/EBITDA: 19
The power of accelerating earnings.

$ASML is not expensive right now.
Forward PE: 24
Forward EV/EBITDA: 19
The power of accelerating earnings.
TacticzHazel retweeted
My average buy price for $NBIS is $24.
I recently sold part of my position at $260
Another part at $281.
Yet, at this price I am still not buying.
It has nothing to do with the company itself, I just believe it can overshoot a lot lower from here.
If I miss it, I'm happy to let the position run.
You don't ALWAYS have to do something.
And for the bears: $NBIS is still up almost 100% YTD.
Easy to forget after such a sell-off.

This post hit a nerve with a lot of people. And I guess some is fair criticism.
I guess I framed it badly. Now it came across like I was celebrating my perfect execution on $NBIS.
Not even close.
I trimmed my position at way lower levels too. First trim at $60 even. And another one at $140.
The message i was trying to get across that sometimes doing nothing is best. You can wait for the perfect ''there is no way around not buying now'' moment.
And at the same time just sometimes miss these opportunities. There will always be another one.
The biggest mistake in my $NBIS run is me not buying on the way up. I sold.
But that's just how I do things. Once a position gets to big for my liking. Especially highly volatile names. I sometimes trim to balance the portfolio.
Oh and I made a few shitty buys this year as well.
Most will know I hold $NVO.
I also ran up $PNG.NE to $10, to see the position decline to $4 today. Never trimmed.
I've been buying $SE these pasts months, and we all know how that went.
I'm not trying to sell you that I'm the perfect investor.
Far from it.

My average buy price for $NBIS is $24.
I recently sold part of my position at $260
Another part at $281.
Yet, at this price I am still not buying.
It has nothing to do with the company itself, I just believe it can overshoot a lot lower from here.
If I miss it, I'm happy to let the position run.
You don't ALWAYS have to do something.
And for the bears: $NBIS is still up almost 100% YTD.
Easy to forget after such a sell-off.
Cheaper valuations for your favorite holdings are a gift.
Treat it as such.
If you've done your research, thesis holds up, sell-offs are when you act.
Don't sell into fear, sell into euphoria.
This.

I’m gonna call out the so-called finance influencers for a second.
I know this is gonna offend many people and I am sorry for hurting your feelings but this needs to be said.
- Why don’t you talk about your losers?
- Why is it so hard to say, “I was wrong. That stock was a bad pick.”
- Why do the stocks you couldn’t stop talking about suddenly disappear from your feed once they’re down 50%?
2025 and 2026 created a graveyard of stocks down 50%, 60%, 70%+ from their highs. Some may never fully recover.
If you pushed a stock 5, 10, 20 times as an “investment opportunity” - especially to paying subscribers - you don’t get to go silent when it blows up.
Your ego should never be more important than someone else’s capital.
Anybody can post the winner and quietly delete the loser from the conversation.
Real accountability is coming back and saying: I got this one wrong.
Grow some balls. Man up. Own it.
So apparently Patrick Boyle is a fraud.
Such a shame, loved falling asleep to his monotone voice and witty remarks.
youtu.be/Za5IfIbWNEk?is=5eRo…
TacticzHazel retweeted
$NVO is now down 75% from it's all-time high.
Time to do another extensive update on where Novo currently sits, and for this occasion I teamed up with @BurnTheIndex
Looks cheap looking purely at valuation metrics, but is that really the case?
Full update can be found (for free) on my Substack. Link here:
tacticzhazel.substack.com/p/…
Please like and share if you thought this was valuable information!