

Professional rock-turner. Finding the companies the market hasn't found yet, but can't ignore for long. 10+ years in the markets. Deep dives in the newsletter ↓
Join +4.5K Readers ➝
Joined October 2025
- Tweets3.4K
- Following150
- Followers4.2K
- Likes5.1K


Pinned Tweet
Copart: a wonderful company at a wonderful price (I bought it, of course) open.substack.com/pub/undisc…

I want some of whatever sell-side analysts are drinking.
Analysts expected about 30 companies to grow earnings 20%+ a year for 10 years straight. Guess how many made it.
0.
From 1997 to 2022, no company in the MSCI World managed it.

Walter Schloss beat the S&P 500 for 45 years. He wrote down his whole method, condensed into a 16-point checklist:


Wall Street has spent centuries inventing new ways for smart people to lose money.
Point72 wants its analysts to study them, so they don't reinvent one on their own.)

What a wonderful chart. Analysts keep raising their earnings forecasts while investors pay less for each dollar of them.
Mr. Market doesn't believe its own expectations.

Take 10 small cap funds and invest 10% in each fund’s biggest conviction, and you’ll likely outperform all of them. Don’t thank me, thank them.
A portfolio with 2% in Walmart in 1972 and 98% in stocks that all went to 0 still beat the S&P 500 over the whole period.
Is this a textbook argument for diversification, for concentration, or survivorship bias?


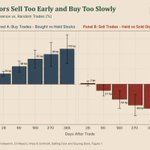
Professional investors would have made more money rolling dice to pick which stocks to sell.
Imagine spending weeks researching a great stock, only to pay for it by selling the wrong one. The best part is they don’t even realize it.

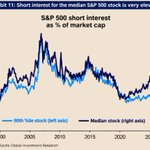
Friendly reminder: short interest is the strongest known predictor of stock market returns.
Stay safe.

So many things in 1 chart:
- The birth of buybacks
- M&A cycles
- Relatively stable R&D despite the technological revolutions
- 2 minutes with this chart and you’ll find plenty more.
All of this happened in 1 investing career. A beginner in 1970 couldn’t have drawn it on day 1, and a beginner today is starting the next version. He’ll need a big eraser.


Your patience has a physical address: right behind your forehead.
It’s the prefrontal cortex, a highly plastic region that you can maintain or let wither, like a muscle.
Every time you delay a reward, or even the anticipation of a reward, you recruit neural networks in this area.
Repeated activation of these circuits changes them deeply. Over months and years, this leads to:
- Synaptic strengthening = stronger and more stable connections between neurons
- More synapses and dendritic complexity = more complex branching of neural networks and deeper processing
- Myelination of the pathways involved = faster and more efficient electrical signal transmission
Practice, and your neurobiology will change. Stop practicing, and it goes back to how it was: connections get pruned, the efficiency of signal transmission drops, and the more impulsive pathways regain their dominance.
Every drawdown you go through without selling, every bout of FOMO you resist, every time you stop yourself from imagining a 10x when you buy is one more repetition. In its infinite generosity, investing offers us training opportunities every day. You just have to know how to recognize them.

Defense stocks are getting massacred, but not IEH Corporation $IEHC: a $73M US micro cap with a backlog up 3x in a year, with parts in many US missile programs in the spotlight since Ukraine and Iran.
We wrote what we think is the most comprehensive deep dive on it:
A $73M sole-source US missile supplier: backlog up 3x, record quarter, clean balance sheet open.substack.com/pub/undisc…

Buying great businesses isn’t enough when everyone else knows they’re great too.
The most profitable 20% of US stocks delivered the FOURTH-best returns out of five groups over 40 years. Only the least profitable 20% did worse.

What’s Wrong, Anon? Feeling bad because you’re down too many percent while everybody else seems to be up triple digits YTD?
May the fact that Yahoo was worth more than Berkshire in 1999 help you through this ordeal. Or not.

Undiscovered Compounders retweeted

$UMAC thesis summary
If any of my friends here could let me know if I'm missing something important.
Long and biased, buying into the lows.

Oh yeah, it's between to shit technically. But if you connect the Mar '25 and Nov '25 lows on a log chart we're still above, for now at least.
I have a superbear case that could see it go to $8, but more realistically $10 would surprise me. If you would humor my articulating the case, very open to being told I'm blind to something important.
They've got a tangible book value of about $7.30 per share, $4.60 of which is just cash. At $16 you're paying $500M for the operating business, which should do between $180M and $250M top line next year on 35%-40% GMs.
As far as that operating business goes, it serves a rapidly scaling demand base and sits within a policy driven supply vacuum. These drone parts sourcing requirements are tightening on both the DoW and commercial side, and FAA Part 108 BVLOS (Beyond Visual Line of Sight) regulation is underway, opening up far more commercial use.
We saw 100% top line growth QoQ and 650% growth YoY in Q2. FY '26 should come in around $61M+-3M if Q3 and 4 come in within my bands ($14-$16 and $20-$25M; H1 was $25M). While off a low base in '25 ($11M for the FY), next year we'll still see between 300% to 400% top line growth to between $180M and $250M in my estimation. That while sporting mid 30s gross margins through this phase of production ramp. Should dip a bit in Q3 to low 30s before returning to mid 30s in Q4 and then drifting towards 40 through '27.
As for another near term bump, closing this UE acquisition should provide a clear path for the OSC to inject a healthy chunk of cash into the company, which has been long anticipated but probably couldn't due to audit requirements.
All of which is to say, I think that in spite of the ugly technical picture, paying between 2x to 3x forward EV/Sales on a triple digit grower with a heavily net cash balance sheet and with policy backing is unlikely to be a price I'm too unhappy with long term. Dip could get dippier of course, but I'm leaning into the lows set the past three days and have asks sitting in the book to take some off on any catalyst or relief pop.
The immediate danger is a known weak Q3, which has been guided low in both rev and gm as equipment gets installed and comes online. This has been clearly broadcasted and so should be "priced in", but for all I know the know-nothing quant algos will see a flat Q and hammer the loss of sales momentum.
Idk I'm pretty content with the position at this price, but please let me know if I'm missing something important.
