






FCC transceiver ban headline: "Innolight out."
The detail that matters: the carve-out MS reportedly heard in DC lets China-built 3.2T in if 65%+ of BOM is from US firms. Marvell DSP + LITE/COHR lasers gets close.
Real loser: Chinese lasers. Winner: US lasers, not assemblers.
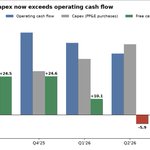
SK hynix says DRAM and HBM are "virtually sold out" through 2029. The number that explains it: Q3 capex (PP&E) was KRW 12.7T on KRW 104.6T revenue. 12% of sales, vs 21% a year ago.
The shortage is demand plus discipline. Watch 2027 capex, guided "significantly" higher.

China’s #4 DRAM maker CXMT priced the biggest A-share chip IPO ever (~$8.5B) at an ~$85B valuation. The pre-IPO perp on Hyperliquid says that’s quaint: ~$7-8 vs the $1.29 IPO print, implying $500B+ — half of SK Hynix, for a fab still at ~25% HBM3E yields.
It lists July 27, no daily price limits for the first five sessions. If Chinese retail marks the #4 DRAM maker anywhere near the perp, the read-across is simple: $MU — a real HBM business at ~6.5x forward earnings — screens as the mispriced one. The supply bill comes later.
KD87 retweeted

It's honestly disgusting how openly retail gets farmed here.
I'm not bearish these companies. I just think the valuations US retail gets handed on day one are ridiculous.
All the reasonable-entry upside already happened in private, walled off from us. By the time we're allowed in, the tag reads:
- SpaceX, ~$1.8T at IPO
- Anthropic, ~$1T, still private
- OpenAI, ~$850B, still private
- Cerebras, ~$80B on day one
Now look at where Chinese retail gets to step in:
- Zhipu, ~$7B at IPO
- MiniMax, ~$6B at IPO
- CXMT, ~$80B with the move still ahead, and the public can actually subscribe
American retail only gets access once the valuation is already in the stratosphere.
The 100x always happens where you're not allowed to be. You only get invited when it's time to hold the bag.


$CRM back-solves to something odd. At 3.6x forward sales the price already assumes ~9% growth forever — the H2 re-acceleration the company still guides to is valued at zero. So the bet here isn't "AI winner," it's just "H2 doesn't break."
The Sep 3 cRPO print settles that one number. Meanwhile the ~$5B Anthropic stake it carries at cost, unmarked, rides free on top. This week's sell-off was an IBM read-across, not a CRM data point.
$NBIS is down about a third from its $299 high, and the business got better on the way down: RPO still north of $33B, and on July 14 it signed a fresh $1B compute deal with Reflection AI. A backlog-rich AI-cloud name selling off while it books new demand.
The part nobody's pricing: the call that decides this name isn't NBIS's own. Meta and Microsoft — its two anchor customers — both report on July 29, eight days before NBIS. Meta's call is where you find out if hyperscaler compute feeds the neoclouds or eats them.
bloomberg.com/news/articles/…

$LEU gets a mechanical bid Tuesday. It enters the S&P SmallCap 600 before the open, on an ~18M-share float that's already ~22% sold short — forced index buying into a book that thin tends to get loud.
But a passive bid is flow, not a verdict on the business. $LEU screens cheap partly because most of its revenue runs through a Russian supplier on per-shipment licenses through 2027 — forced buying doesn't touch that. I'd watch how the float absorbs it before calling a squeeze.
$UUUU's CEO signed the Vacuumschmelze deal that took the stock down 20% — then bought $970K of his own stock at $13.08, the first insider purchase here in five quarters. Before that, insiders sold roughly $17M over a year.
He's defending his own deal, but he's also the only public buyer who has actually seen VAC's books — they're not filed yet, the rest of us are guessing. A year of selling flipping to buying is the strongest version of this signal. Worth a look, maybe a small starter.

KD87 retweeted

1/
I started tweeting this account about 2 years ago when SOL was at 30$ with less than 100 followers.
Now, 2 years in, I've crossed 32k followers.
after 2 years, around the same time, with potential UP-quarter
I figured it’s a good time to write this thread — about how my trading style evolved from scalping to MTF positioning, and why two principles changed everything:
Fold Pre & Pocket Ace. (feat. @thiccyth0t )
2/
The Fold Pre Principle is simple.
You shouldn’t have taken that trade in the first place.
Low conviction positions destroy more accounts than bad entries ever will.
The smartest move?
Don’t enter low-conviction setups at all.
3/
This applies to life too.
Jobs we hate but can’t quit.
Relationships we’ve outgrown but hold onto.
Dead trades we keep averaging down.
Ask yourself:
“If I could walk away today, free of cost, would I re-enter this position?”
If not — fold pre.
4/
Markets evolved.
Short-term trades are now mostly noise.
Charts alone won’t show you the real upside anymore.
Macro drives most of the flow now, and that’s what I began to focus on — ignoring the noise, and spending real time on research + positioning.
5/
I started just like many of you —
BitMEX scalps, leaderboard runs, dopamine loops.
But slowly, I changed.
Because true edge started to show only on higher timeframe setups with asymmetrical reward.
Scalping can’t give you life balance. Big trades can.
6/
There are many ways to make money.
Airdrops, farming, funding, degen longs, sniper entries.
But in the end —
It’s what you do when your Pocket Aces show up that defines you.
7/
And Pocket Aces don’t come often.
It’s your job to recognize them —
– When fundamentals + positioning + catalysts align.
– When you feel it in your gut and your spreadsheet.
– When the only thing left is to size in and execute.
8/
That’s how I treat my trading now.
Not as a trade.
But as an investment.
If the opportunity doesn’t align with a clear narrative or conviction — I skip it.
If it does, I size in.
Simple.
9/
Everyone has different edges.
Some people are great at scalping.
Some at hunting airdrops.
Some at L1 narratives, farming or option flow.
Don’t copy others.
Just know your Pocket Aces.
And when they come, bet like your life depends on it.
10/
Fold Pre is the art of restraint.
Pocket Ace is the art of commitment.
Both require experience.
Both require pain.
But if you can master just these two —
You’ll not only survive this market.
You’ll win.
11/
It looks like we’ll need to enter positions ourselves before mid-month.
Keep it simple:
→ Focus on a few key narratives
→ Don’t over-complicate
→ Don’t over-trade
→ Have conviction in the bet you chose, researched, and verified.
Believe in yourself.
Keep some cash on the side for new narratives.
Time to lock in.
KD87 retweeted

Remember - tariffs are dovish, and big tariffs are very dovish.

Big tariffs would lead to more rate cuts than expected. The inflationary impact of tariffs can be mitigated by fx moves, margin compression, and are ultimately transitory. But their damage to business sentiment and export sectors could raise unemployment.
fedguy.com/tariffs-are-dovis…

KD87 retweeted

S&P 500 - TAX DRAIN
In years following large bull market gains, the S&P 500 often suffers through an air pocket during tax season.
We saw this in 2022 (-12%) and 2024 (-5%).
Beware of those expecting positive April seasonality
@3F_Research
