

AI, big data, community, bond trading
USA
Joined August 2023
- Tweets36
- Following5
- Followers133
- Likes3







dataQollab retweeted

.@dataQollab MBSMKT CLOSE: Not Likely But Warranted (10/27/2026 Pre-FOMC)
Rates spent Tuesday doing what markets usually do the day before a Fed decision. They paced the hallway, checked the door a few times, and ended the session roughly where they went out yesterday. No reason to add risk in front of the Fed tomorrow...
Treasuries started strong with 2s leading the way (4.5bps lower at 4.70) before gains were quickly erased after durable goods printed hot at 8:30am. Yields “jumped” a whopping ~3bps across the curve when the data flashed which took 2s from 4.70% to 4.73% and 10s from 4.97% to 5.00%. “Weakness” -- if you can call it that -- lasted for 90 minutes at most before oil deflated and allowed rates to slowly consolidate on air for the rest of the session. At 4pm 2s were -1.0bp vs 445pm marks at 4.73%; 5s were +1.3bps at 4.84%, and 10s were +0.5bp at 4.99%.
Mortgages traded quietly alongside Treasuries. TBAs finished near UNCH on the day with down-in-coupon getting the gold star for basis performance vs both 5s and 10s. FNCL 5.0s and 5.5s finished up 2-3 ticks, 6.0s gained 1+ to 99-17, and 6.5s were flat at 101-126. The FNCL current coupon was last spotted at 6.125 (-0.8bp); 2.2bp tighter to 5s (+129/) and 1.3bp tighter to 10s at +113/. Volume reflected the clear lack of motivation with FNCL 6s the most active spot in the stack while elevated roll volume was noted in FNCL 3.5s (relatively speaking).
The real question is whether tomorrow’s FOMC decision is as predictable as the market believes. Futures imply only about a 9% probability of another 25bp hike, effectively treating a hold as a foregone conclusion. Yet economic data over the past month has offered the Fed little reason to declare victory over inflation. September CPI and PPI were both hotter than expected, regional surveys continue to show selling-price pressure, and the Beige Book highlighted persistent increases in energy, transportation, commodities, and insurance costs. The argument for another hike is hardly unreasonable, especially with the last FOMC statement emphasizing a “timelier return to the Committee’s 2 percent goal”. The argument for waiting appears rooted in the patience embedded in recent Fed communications from the likes of John Williams, the preference to avoid consecutive moves, and perhaps the biggest reason for a hold tomorrow...political sensitivity to hiking rates immediately ahead of the midterm elections. We suspect the market’s recent flight-to-quality rally cough-covering shorts-cough and concerns over potential AI financing contagion have contributed greatly to expectations becoming heavily skewed toward a hold.
That leaves an uncomfortable asymmetry for rates. A hold is overwhelmingly priced and offers relatively little reason for a further rally on its own. A surprise hike, on the other hand, would force an immediate repricing of the front-end (at least). Even a hold could prove hawkish if accompanied by multiple dissents or commentary from Chair Warsh reinforcing the likelihood of additional tightening in December and early 2027. Given the recent volatility in Treasuries and the speed with which the 10-year retreated from yields above 5.30%, the market may be more vulnerable to a hawkish surprise than current implied probabilities suggest.
Not likely to hike but definitely warranted. We did a deep dive on the blog if you’re interested in the evidence.
mbsmkt.com/community/october…
AQ

dataQollab retweeted
.@dataQollab MBSMKT WEEKLY: Quick Summary
1) You definitely sing a certain Vanessa Carlton song in the car. Don't lie.
2) Mortgages closed the books on an ugly month and quarter without any style, grace, or dignity ,,|,,
3) Spec payups went poof. Day 1 margin leakage will be/is a problem for lenders looking to sell loans.
4) Spotting a current coupon will be difficult if 6.5 TBA coupons trade below par. Getting close.
5) The economy is operating at full employment. Any NFP print > 0 is just extra icing on an already iced cake.
6) Every day the war continues is another day the inflation impulse stays alive <-- Vigilante view.
7) The Fed is solely focused on a "timely" return to target inflation. The labor market is not a concern right now.
Read the rest if the mood so strikes you: mbsmkt.com/community/mbsmkt-…

Aug 2026 month-end TBA MBS 5pm screen grab and a quote from the MBSMKT CLOSE: "....the question is whether real money is genuinely sold on the idea of another hike cycle or if fast money algos are simply riding 'anything can happen in September' tactical momentum.


dataQollab retweeted
.@Pulte seems to have taken on @FHFA press secretary responsibilities so I started using @impactcapitoldc's AI to track his tape bombs. Have enjoyed the layered perspective it provides re: the potential impacts on housing and the mortgage market.
Quarter end can't come soon enough. Here's my 03272025 closing marks .

dataQollab retweeted
FHA has decided to "end the wasteful misappropriation of taxpayer dollars to benefit illegal aliens" ie you gotta have a green card to get an FHA loan now. Times are certainly changing but Alf, ET, and the Dos Equis guy aren't too worried because all 12 of their FHA insured "owner-occupied" properties are locked in at 3.00%. ET is phoning so many homes. Today we heard about 25% tariffs on cars not built by FHA eligible borrowers. Tomorrow @Pulte might make Radon great again. Stocks sold all day and bonds could not have cared any less. Durable goods data didn't help yields nor did $70bn 5s trading with a tail. Bear steepening pressed mortgage spreads uniformly wider but performance played out in a choppy manner. Basis movement had me double checking my model all day. Quarter-end window dressing might get weird...
AQ

dataQollab retweeted
AEI says Donald and his team of Rescue Rangers should consider selling or leasing unused government property to help alleviate the housing affordability crisis. Realtors are lining up to stage CFPB's headquarters for showings and rental agents have been spotted putting bunk beds inside the Dept of Education. Note: Agent sales commissions will not be clearly stated in any listing and will not be negotiated. Rates trading was a tale of two sessions today. Us vs. them. Yields ticked persistently higher overnight and then yields bounced consistently lower all day until a floor was finally found after 3pm marks flashed . It feels like the market is still finding its footing which means consolidation patterns are our friend until tariff tapebombs take out local highs/lows or fawnflation fears are verified with validated econ data. Mortgages naturally underperformed into the superficial intraday bull flattener but the bounce back was enough for lenders to reprice for the better. Mortgage rates have little to show for it though. Not the worst news for pipeline hedgers...
Durable goods data at 0830, some Fedspeak around 10am, and then $70bn 5s get dutched at 1....
AQ

dataQollab retweeted
Treasury Secretary Scott Bessent ("Bessy") says the American Dream is all about homeownership, finding purpose, and achieving financial security without having to work two jobs. Bessy also believes "hopelessness" eats away at the American Dream which explains why some loan officers are purposely working two jobs to remedy a lack of financial security because many Americans think homeownership is a hopeless dream. That wasn't the joke for today btw. No no...these MOOOOOving comments from Bessy were preceded by @Pulte completely reshuffling Fannie's and Freddie's boardrooms. Shortly after those 8-Ks printed, GSE employees received a passive aggressive ,,|,, email from HR announcing the Enterprise Hunger Games challenge. As I read it, the vaguely obvious rules outlined in the body of the ,,|,, email are actually quite simple . You just have to read between the ,,|,, lines. If GSE employees refuse to return to office 5 days a week and do not agree to purchase their lunch from the world class cafeterias that costs a ton of money to operate...then they will get the Tony Soprano series finale treatment. At least markets were calm and volatility isn't an issue for hedgers ,,|,,

dataQollab retweeted
A WSJ story claims there's a secret Fannie Mae blacklist preventing condo owners from selling their units. Reporters were unable to confirm the story after DOGE eliminated Fannie Mae's condo review team. FED DAY. Jerome sees clouds but has no idea when/if it will actually rain..

dataQollab retweeted
Commentary opener today: All five parties of Greenland’s parliament have bluntly dismissed Donald’s bid to take over the Arctic island. I guess U.S. property insurers will have to find another less risky geo to replace the business they’ve abandoned in Florida and California.

dataQollab retweeted
.@dataQollab Class A 48hr day marks. Three different marks provided. Each with a distinct pricing recipe. One of the benefits for hedgers trading OTC products with embedded optionality. There is no right price as long as you can explain logic and demonstrate consistency...#mbs


Our 445pm mortgage market screen. TBA basis has been squirrelly intraday since rate touched max resistance on 3/4/25. LOs now taking calls instead of making them. Will be interesting to see through-the-box reports. Expecting steep <12 WALA ramps next month. #IRRRL #recapture

dataQollab retweeted
Mortgages saw their heaviest trading volume since May 15th yesterday. FNCL 6s priced near par are the biggest contributor with consistent spikes in the 4pm hour as lenders hedge out. Do not wait for 72-hour day to roll! @MBSLive @dataQollab

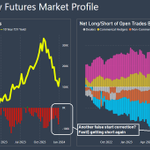
Did rates go too far too fast again? Benchmark 10s rallied all the way down to 3.77% on a potential Fed pivot but quickly jumped back to 4.00% once 2024 trading opened. Fast Money added heavy new short positions into the move. Market profile matters when setting desk durations.

Heavy post-4pm volume today as lenders squared up risk ahead of the holiday. Bid/ask gapped wider when originators were most active though. Dealers finally paying respect to their models again. Steep S-curves have pressed moneyness coupon hedge ratios noticeably lower this week.

The mortgage basis couldn't keep pace with the post-FOMC rates rally yesterday. Higher and wider in heavy trading volume. 156% of the 20 day moving average. Lender P&Ls will struggle with margin calls, lock renegotiations, and MSR multiple repricing....

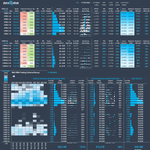
TBA MBS closing marks and desk ratios for 11282023. Take note of basis outperformance and volume spikes in 4.5s, 5s, and 5.5s. This is becoming a trend as investors chase a potential 2024 bull steepener. Buying on the relative cheapness of future moneyness within the stack

