

Built a hedge fund. Now building Arthur, the AI co-founder that gets shit done. https://xitter.cf/t.co/enujRKUTQn. Macro | AI | Startup Investing
Dubai, UAE
Joined August 2019
- Tweets3.9K
- Following1.8K
- Followers1.7K
- Likes29.5K





Pinned Tweet
Everyone is watching Optimus, Figure and Unitree.
I went looking at what actually goes inside the bloody things.
Motors. Bearings. Roller screws. Precision gears. Encoders. Force sensors. Magnets. Actuators.
Then I looked at who makes them, how difficult they are to manufacture and what happens if we really try to build millions of robots a year.
That turned out to be much more interesting than the robots.
open.substack.com/pub/derekw…
🤖 Made with AI

$SoftBank is getting properly fucked. Down 11% today and 52% from its June high.
Borrowing billions at up to 9.75% to stay in the AI game, with precious little cash flow coming from its biggest bets.
Its 5-year CDS is at 432bps, a four-year high. Bonds trading below par, with some now yielding over 10%.
Yet if OpenAI pulls off its proposed $1.4tn raise, SoftBank's 13% stake alone would be worth 15% MORE than its entire market cap.
And that's before Arm and the rest of the portfolio.
It does add up. This is what happens when paper valuations run miles ahead of cash flow, and you need increasingly expensive debt to keep the whole thing going.
Higher rates, inflation and a weakening dollar only make the funding problem worse.
The AI bubble is becoming a massive cash flow crisis that will flow all the way down into private markets, where they are still throwing cash at massive valuations.
I've spent over 30 years starting, building and investing in businesses, and I reckon we've got the whole startup thing a bit backwards.
We celebrate starting, raising and announcing.
Yet none of that means you've built a business.
Until someone wants what you're selling and is prepared to pay for it, you've got a hobby.
AI STOCKS ARE BOUNCING. THE DEBT MARKET STILL ISN’T BUYING IT.
In the words of Mr T... “I pity the fool.”
⭐️ Nasdaq +1.0% and VIX back down to 16.6.
⭐️ SpaceX and Super Micro are dragging AI higher.
⭐️ CoreWeave is still down while the rest of AI bounces.
⭐️ France just hit 5% on the 10Y.
⭐️ The US 20Y auction is the next real bond test.
⭐️ And Big Tech is stretching depreciation lives just as AI hardware is turning over faster.
📈 Stocks
S&P 500: 7,749, +0.48%
Dow: 52,655, +0.30%
Nasdaq: 26,686, +0.99%
Russell 2000: +0.36%
VIX: 16.6, -4.1%
VIX is cheap as chips again considering what is still going on underneath.
AI is doing the work:
SpaceX $SPCX +10.0%
Super Micro $SMCI +9.1%
Tesla $TSLA +3.5%
Nvidia $NVDA +1.6%
CoreWeave is still going the other way:
$CRWV: $61.11, -1.6%.
That divergence is still worth watching.
🤖 AI: Demand Fine. Funding Still The Problem.
SpaceX had a cracking quarter.
Revenue: $14.6bn, +161% YoY
AI revenue: $7.6bn
Net income: $4.4bn
Capex: $19.6bn
More than half the revenue is now coming from AI/server rentals.
So demand is clearly there.
But the capital requirement is fucking enormous.
And S&P has now warned that hyperscalers probably have more AI-linked liabilities than anyone can actually see, buried in SPVs, guarantees, leases and data-centre structures. It reckons the top six could spend more than $7tn on AI infrastructure between 2025 and 2030.
Reuters separately estimates Big Tech already has around $1.09tn of future data-centre lease commitments that have not yet fully hit reported balance sheets.
So the chain is still:
Credit spreads ↑ → funding costs ↑ → funding conditions tighten → project returns ↓ → capex gets harder
🧮 One More AI Accounting Trick Worth Watching
The depreciation assumptions are getting stretched.
A lot of Big Tech is now using 5.5–6 year useful lives for servers and networking kit.
That matters because moving $100bn of equipment from a 4-year life to 6 years cuts annual depreciation from:
$25bn → $16.7bn
That is roughly $8.3bn more pre-tax profit without one extra dollar of cash coming in.
And AI hardware is hardly getting obsolete more slowly.
Quite the opposite.
New GPUs, memory, networking and accelerators are turning over faster.
So extending useful lives while the hardware cycle speeds up is worth watching very closely.
More capex + more debt + longer depreciation = nicer EPS today.
The problem arrives later if the kit has to be impaired or replaced faster than the accounts assumed.
📈 Treasuries / 20Y Auction
Current:
5Y: 4.93%
10Y: 5.11%
30Y: 5.41%
Treasury is selling $13bn of 20Y bonds at 1pm ET.
That is today’s proper duration test.
The 20Y is around 5.48% going into it.
If that auction tails badly, the sovereign-funding problem is straight back on the table.
If it clears well, then Treasuries really are reclaiming some of their haven role.
🇫🇷 France: 5% Has Arrived
France’s 10Y OAT hit 5% today, the highest since 2002.
OAT/Bund is around 150–157bp, close to levels not seen since the euro crisis. Reuters
That is no longer some little French political wobble.
It is:
weak growth
big deficits
protests
budget problems
political uncertainty
and a proper sovereign risk premium
The CAC is actually up today, which makes the bond move even more interesting.
Equities are shrugging.
Bond investors are not.
🇯🇵 Japan: Still Part Of The Debasement Trade
Japan still has the same ugly mix:
USD/JPY: ~158
2Y JGB: ~1.9%
5Y JGB: ~2.3%
10Y JGB: ~2.9%
30Y JGB: ~3.5%
BOJ still wants to tighten.
Government still wants fiscal support.
Debt keeps growing.
Yields stay historically high.
And the yen is still weak.
If Japanese investors can earn materially more at home, that matters for who keeps buying US Treasuries too.
🛢️ Oil / Energy
Brent: ~$108.8
WTI: ~$97.3
Oil is stuck between two opposing forces.
On one side:
18+ vessel attacks in two weeks around Hormuz
Saudi infrastructure risk
Iran escalation
On the other:
Russia/Ukraine talks possibly restarting
more Russian barrels
some diesel relief
That is why Brent is still above $100 without running away again.
💵 FX / Gold / Bitcoin
DXY: 101.78
USD/JPY: 158.09
EUR/USD: 1.1231
Gold: ~$4,149
Bitcoin: ~$84,665, +2.4% Pasted text Pasted text
Gold holding above $4,100 with Treasury yields still north of 5% remains interesting for the debasement trade.
📅 Coming up
Meta and Tesla report after the close.
For Meta:
capex
AI monetisation
margins
depreciation assumptions
For Tesla:
AI spend
autonomy
robotics
and anything concrete on the SpaceX tie-up
These are now much more than simple EPS beats or misses.
The market wants to know whether the returns are arriving quickly enough to justify the capital being thrown at AI. Reuters
The Read
The surface looks fine.
Nasdaq +1%.
VIX 16.6.
SpaceX +10%.
Super Micro +9%.
But underneath:
CoreWeave still weak
AI liabilities still growing
Big Tech stretching depreciation lives
France at 5%
US long rates still above 5%
Brent still above $100
So yes, equities are bouncing.
The bit I still don’t trust is the funding and accounting underneath the build-out.
Layoffs at @carbon_robotics as firm “realigns costs due to broader economic conditions”
Carbon Robotics is cutting staff even as it pushes toward an IPO and new products. If you supply or compete in ag robotics, prepare for tighter budgets and shifting…
wire.fusion-42.com/stories/b…

AI STOCKS ARE BOUNCING, IGNORING THE DEBT MARKET
In the words of Mr T... "I pity the fool"
⭐️ Nasdaq is up more than 1%, but AI credit is still widening.
⭐️ CoreWeave bonds are still yielding around 15%.
⭐️ Treasury yields are back up after last week’s haven rally.
⭐️ France is getting properly ugly.
⭐️ Oil has eased, but the physical market around Hormuz is still a mess.
📈 Stocks
US equities are bouncing:
S&P 500: 7,698, +0.5%
Nasdaq: 26,454, +1.2%
Dow: flat
Russell 2000: +0.4%
VIX: 18.4, -8%
Tech is doing the work.
Amazon $AMZN +5.0%
Intel $INTC +2.9%
Nvidia $NVDA +1.6%
IREN $IREN +4.4%
CoreWeave is still weak:
$CRWV: $60.31, -1.8%.
And breadth still isn’t great. Reuters had 242 Nasdaq names making new lows against only 20 new highs even as the index bounced. Reuters
🤖 AI: Equities Up, Credit Wider
This is the bit I care about.
Oracle 5Y CDS: ~288bp
SoftBank 5Y CDS: ~424bp
CoreWeave CDS: 1,000bp+
CoreWeave’s 2031 bond yield has eased a bit from last week’s panic, but is still around 15.1%.
So the equity market is saying:
“buy the dip.”
The credit market is saying:
“show me how the fuck you’re going to finance it.”
And S&P has added another problem today: it thinks hyperscalers probably have more AI-linked liabilities than we can actually see, buried in SPVs, guarantees and data-centre structures. It reckons the top six could spend more than $7 tn on AI infrastructure between 2025 and 2030.
The chain remains:
Credit spreads ↑ → funding costs ↑ → funding conditions tighten → project returns ↓ → capex gets harder
📈 Treasuries / Fed
Treasuries had a proper haven rally into Friday, despite the hot CPI print.
Today some of that move is reversing as equities bounce:
2Y: ~4.79%, +5bp vs Friday
5Y: 4.94%, +4bp
10Y: 5.14%, +5bp
30Y: 5.48%, +5bp
So the curve is basically 5bp higher across the board.
The more interesting change is Fed pricing.
After last week’s hot CPI, October hike odds briefly jumped hard. They have since collapsed after Warsh refused to pre-commit and financial conditions tightened through the market itself.
That is a pretty important shift:
Stocks ↓ → credit wider → funding harder → Treasuries bid → Fed pressure eases
🇫🇷 France
Europe is having a worse day.
CAC 40: -1.1%
Euro Stoxx 50: -1.0%
DAX: -1.2%
FTSE 100: -1.1%
France is the main problem.
The 10Y OAT is around 4.9% and the spread over Bunds is about 146bp as riots, weak growth, budget delays and fiscal worries pile on. French banks and retailers are getting hit.
This no longer looks like a one-day political wobble.
The market is charging France a proper risk premium now.
🛢️ Oil / Energy
Oil has eased from the highs:
WTI: around $99–100 Brent: around $108–110
Trump’s Russia sanctions waiver is helping because it keeps more Russian supply flowing.
But the physical market is still nasty.
Hormuz flows reportedly fell from more than 20m barrels/day to around 8.5m during the latest disruption, and shipping attacks are still the big physical risk.
🇯🇵 Japan, Still A Massive Part of the Debasement Trade
Ueda says inflation is close enough to target to justify more tightening, while the government is still talking about more debt-funded fiscal support.
USD/JPY: ~158.5
2Y JGB: ~1.90%
5Y JGB: ~2.30%
10Y JGB: ~2.91%
30Y JGB: around 3.5% area
So Japan still has the ugly mix:
more debt → higher JGB yields → weak yen → tighter BOJ
And if Japanese investors start demanding more yield at home, that matters for US Treasuries too.
🇨🇳 China
China’s Q3 GDP came in at 4.5%, better than expected, while the yuan is near a four-year high.
The more important long-term point is still the same.
China does not need to kill the dollar.
It just needs to:
buy fewer Treasuries hold more gold settle more trade in yuan build deeper RMB markets and make itself less dependent on the dollar system
Slowly.
While Washington keeps issuing more debt at 5%+.
Tht is how the marginal buyer problem gets worse over time.
📅 What Matters Next
Tuesday: SpaceX $SPCX reports after the close, with the call at 4:30pm ET. That one matters because it is also reportedly trying to raise $40bn for AI compute — roughly $10bn of bank loans + $30bn of IG debt. ir.spacex.com
Wednesday after the close: META, TSLA, LRCX, TXN and IBM. That is the first proper earnings test after last week’s AI funding wobble. Watch Meta capex/AI monetisation, Lam/TI chip orders and whether anyone delays infrastructure spend. Reuters
Global govie supply
Japan: tomorrow is the big one — ¥700bn of 20Y JGBs. With the BOJ still sounding hawkish and the government talking more debt-funded fiscal support, that auction matters. Japan also has a ¥500bn liquidity-enhancement auction Thursday. 財務省
UK: conventional gilt auction Tuesday, then an index-linked gilt auction Thursday. DMO
France: no new long OAT auction this week after last Thursday’s sale, but France is still issuing bills and the OAT/Bund spread is the thing to watch, not supply itself. Ministère de l'Agriculture
US: the main duration tests are the 20Y Treasury reopening on Wednesday and 5Y TIPS on Thursday.
So the next 72 hours are pretty clean:
Japan 20Y auction → SpaceX results/funding → META/TSLA/LRCX/TXN/IBM → US 20Y/TIPS supply
That is enough to tell us whether last week’s AI/credit stress was just a wobble or the start of a proper repricing.

THE BOUNCE FAILED. THE DEBT GROWS.
Thats was a week that was.
⭐️ CPI, PPI and import prices all came in hotter than expected.
⭐️ Nasdaq lost 4.5% this week. CoreWeave lost 25.2%.
⭐️ Government bonds caught a safety bid while Washington reported another $2tn annual deficit.
⭐️ Europe outperformed. Japan’s higher borrowing costs remain a global risk.
⭐️ Brent finished near $110.
⭐️ Ukraine’s satellite restrictions exposed the cost of depending on infrastructure somebody else controls.
📉 STOCKS — DEAD CAT BOUNCE
Weekly moves:
Nasdaq: −4.5%
S&P 500: −1.9%
Russell 2000: −3.0%
Dow: +0.7%.
The Dow held up while technology and smaller companies took the damage. Money is becoming more selective about which earnings—and which balance sheets—it trusts.
VIX finished at 19.99, up roughly 35% over the week, after reaching 22.31 on Friday. Protection is getting more expensive.
🔥 INFLATION. THE PROBLEM IS STILL HERE
CPI: 3.7% annually, with core prices up 0.3% monthly.
PPI: 6.3% annually, up 1.3% in September alone. Producer energy prices jumped 10.8%. Strip out food, energy and trade services, and prices were still 5% higher annually.
Import prices: +1.1% monthly against 0.8% expected, and +8.1% annually. Those figures exclude tariffs. Duties add another cost, which businesses absorb in margins or pass through to customers.
Energy, imported goods, tariffs and financing costs. Businesses are being squeezed from several directions.
🥇 GOLD. I STILL LIKE IT
Gold sold off after CPI as traders priced a tougher Fed. It then recovered, trading around $4,165–$4,167 late Friday, although still roughly 0.7% lower over the week.
My view: gold around $4,145 looks like a gift over the longer term.
The market’s first reaction was that the Fed would fight harder. My concern is how far behind the problem it remains.
Higher rates can squeeze demand. They cannot reopen Hormuz, remove tariffs or make Washington balance its books. They also increase the cost of refinancing debt.
🤖 AI DEMAND DOESN’T PAY THE INTEREST BILL
CoreWeave closed at $61.39:
−11.9% on Friday.
−25.2% over the week.
Thursday’s 5.9% bounce disappeared the following day.
Dell lost approximately 23% over the week, showing how the pressure reaches equipment suppliers.
CoreWeave bond yields traded above 15% during the week. Its five-year CDS spread passed 1,100bp on Thursday. Oracle’s default protection also reached record levels. These are reported levels during the week, rather than Friday closing quotes.
Funding costs ↑ → project returns ↓ → refinancing harder → capex delayed → supplier earnings at risk.
AI adoption can keep growing while investors lose money. The equipment, electricity and debt still have to be paid for.
Revenue backlogs are useful. Cash flow determines whether the financing works.
🤖 ANTHROPIC GROWTH UP, VALUATION UNDER PRESSURE
Anthropic reportedly told investors Q3 revenue reached $16.8 bn, up 45% quarter on quarter, with an adjusted profit. Strong growth, but slower than Q2’s more-than-doubling.
Some investors are now discussing $1.5 tn, against earlier expectations around $2 tn. That is 25% lower, though no IPO price has been agreed.
Still no public S-1 located. The filing was confidential; reported prospectus details and private investor presentations are what we have so far.
“Adjusted profit” needs the adjustments. Revenue needs margins, cash flow and spending commitments alongside it.
At trillion-dollar valuations, even 45% quarterly growth can disappoint. That tells you how much perfection was already priced in.
My guess is that the numbers are shit (for a $2t val) and they will delay using a safety excuse.
🏦 US BONDS A SAFETY BID APPEARED BUT THERE IS STILL A MONSTER BORROWING PROBLEM
US 10-year: approximately 5.09%, down around 16bp over the week.
US 30-year: 5.44%, also down around 16bp.
Investors bought Treasuries as they cut equity risk.
My view is that this relief will struggle against the scale of borrowing still ahead.
Friday’s fiscal figures:
$5.40tn collected.
$7.40tn spent.
$1.992tn annual budget deficit.
$1.36tn gross interest costs, equivalent to roughly 25% of federal receipts.
Total federal debt above >$40tn.
Washington must finance that spending gap alongside refinancing maturing debt. Older, cheaper borrowing rolling into higher rates adds pressure to the interest bill.
Spending grew 6%. Receipts grew 3%. The gap widened despite record revenues.
This is a debt spiral and the credit-card binge mentality continues.
🇨🇳 CHINA EXPORT BOOM, DOMESTIC STRAIN
Shanghai Composite: 3,716 | −2.6% over the week.
Hang Seng: 24,187 | −0.1%.
Friday’s rebound did little to repair mainland losses.
September exports surged 36.3% annually, against 25.5% expected. Imports rose 31%, versus 24.5% expected.
The monthly trade surplus reached a record $133.5 bn, taking the first nine months to $938.1 bn. AI-related equipment and semiconductor shipments were major contributors. Part of the export surge reflects higher chip prices, so headline export growth overstates the increase in physical volumes.
The domestic picture is much weaker.
Producer inflation accelerated to 5%, above 4.5% expected. Consumer inflation was only 0.9%, below the 1% forecast.
Factories face rising energy and commodity costs while weak household demand limits their ability to pass those costs on. That puts margins under pressure.
💴 THE YUAN AND CAPITAL FLOWS
The yuan traded around 6.69 per dollar on Friday, near its strongest since January 2023 and heading for a third consecutive weekly gain. Strong exports are supporting the currency despite domestic weakness.
Beijing also pledged further financial-market opening, wider international use of yuan bonds as collateral and stronger offshore yuan markets. This is relevant to diversification away from dollar assets, although it does not establish that the dollar is losing reserve-currency status.
China is exposed to the same AI spending cycle supporting US technology. If financing pressure slows global data-centre investment, Chinese equipment suppliers feel it too.
🇯🇵 JAPAN CHEAP FUNDING IS GETTING LESS CHEAP
Japan’s 10-year yield finished around 2.94%, down 7.9bp over the week.
The 30-year finished at 4.01%, down 5.7bp.
Japanese bonds rallied too, but the BOJ’s policy rate is now 1.25%. Several brokerages expect another increase in December, while Ueda warned about inflation overshooting its target.
Higher domestic yields can encourage Japanese investors to keep more capital at home. More expensive yen funding also squeezes leveraged carry trades.
That matters well beyond Japan.
🇪🇺 EUROPE BETTER EQUITIES, SAME INFLATION CONSTRAINT
STOXX 600 finished at 644.74, gaining more than 2% over the week. Strong results helped Europe outperform the concentrated US technology trade.
But eurozone inflation remained 3.8%. The ECB has raised rates 50bp this year, taking its deposit rate to 2.50%, with another December increase priced in.
Germany’s 10-year yield was around 3.42% late Friday. Europe’s stronger equity performance does not remove its financing constraints.
🛢️ OIL — STILL FEEDING INFLATION
Brent settled at $109.86, up 3.72% on Friday, as Middle East supply risks kept prices elevated.
That feeds into freight, manufacturing and household bills. It also makes it harder for central banks to support weakening economies without risking another inflation surge.
🛰️ STARLINK / STARSHIELD — WHO CONTROLS THE SWITCH?
Ukraine says its military Starshield connections were cut when terminals travelled above roughly 160 km/h, disrupting drone operations. Negotiations to remove the restriction continued on Friday.
This concerns the speed at which terminals move. Musk says the US government controls Starshield; Trump denied ordering the restrictions. Responsibility remains unresolved.
Critical infrastructure comes with political and counterparty risk when another party can restrict access.
For Europe, sovereign communications capacity has a very practical value.
👀 NEXT WEEK: 19–23 OCTOBER
📊 Data
Mon: China GDP (4.4% expected vs 4.3% prior), industrial production and retail sales; Canada CPI.
Tue: UK jobs/wages; China loan prime rates; US housing starts, permits and pending sales.
Wed: UK CPI.
Thu: US jobless claims.
Fri: Japan CPI; UK retail sales; US/UK/eurozone flash manufacturing and services PMIs; final Michigan sentiment and inflation expectations.
🏦 US auctions
Mon: $95bn 13-week + $82bn 26-week bills.
Tue: $95bn 6-week bills.
Wed: $13bn 20-year bond reopening.
Thu: $26bn new 5-year TIPS.
$311bn announced, plus scheduled 17-, 4- and 8-week bills. Gross issuance includes refinancing.
🇯🇵 Japan
Tue: ¥700bn 20-year JGBs.
Thu: ¥500bn liquidity-enhancement reopening auction.
🇪🇺 Europe
Tue: UK 2036 conventional gilt; German green bonds.
Thu: UK 2031 index-linked gilt.
Watch the 20-year auction for sustained demand, TIPS for inflation protection, and Friday’s data for rising prices alongside weakening growth.
I don’t see gut feeling and data-driven investing as opposites.
What we call gut feeling is just human pattern recognition that we can’t yet fully explain.
As more companies are built using AI, we’ll have far more data on founders, their decisions, behaviour and outcomes. Over time, we’ll get better at understanding the patterns behind successful businesses.
LLMs alone won’t get us there. We need AI that can understand real-world behaviour, not just language.
A VC’s gut feeling may be an information advantage today. That doesn’t make it a fundamental human advantage tomorrow.
Just because we can’t explain something yet doesn’t mean we won’t.

THIS 100%

I think one of the biggest problems with startup accelerators is that we’ve confused teaching founders how to pitch with teaching them how to build a business.
Spend three months perfecting your story.
Build a beautiful deck.
Practice your two-minute pitch 100 times.
Learn exactly which buzzwords investors want to hear.
Then get on stage at Demo Day and announce you’re raising $4M.
Great.
But can you actually sell your product?
Do you know why customers buy it?
Can you explain your margins without opening a spreadsheet?
I’m a big fan of accelerators. The best ones provide incredible mentorship, networks, and early capital.
But we’ve created an ecosystem where some founders can explain their billion-dollar market opportunity better than they can explain their first $10,000 in revenue.
Fundraising is a skill. Building a business is a completely different skill.
And the two don’t always overlap.
Maybe Demo Day should include five minutes of founders trying to sell their product to an actual customer.
Because getting 200 VCs excited about your startup is impressive.
Getting 20 customers to pay for it might be even more impressive.
Dug into this a few weeks ago when @HarryStebbings posted a timely and openly honest video on this.
VC is really caught between a rock and a hard place but doing the same as everyone else is shit strategy.
There will be a lot of reinvention required at the early stage to keep capital flowing into startups across the board.
xitter.cf/derek__watson/status/2…


I've just been listening to a bunch of people with enormous reach and power. The Trumps, Hegseth, Musk, Altman. You know the gang.
I was taught not to lie. Clearly, a lot of people weren't.
Or perhaps they've simply decided that power gives them the right to lie, manipulate and get their own way.
The funny thing about lying is that it always gets found out. People know. The evidence is there. The contradictions are on record.
But some people have doubled down so many times they can't even remember their own bullshit anymore.
What's extraordinary is that we've never had better tools to check facts, verify claims and establish a history of what people actually said and did. Yet the lies just keep coming.
And when they're caught? Double down harder. Tell another lie. Call everyone else stupid, shout louder and repeat.
Apparently, lying is no longer something to be ashamed of. Neither is getting caught.
And that's what really worries me.
We've reached a point where being exposed as a liar doesn't necessarily cost you your power, your position or even your supporters.
When dishonesty carries no consequences, it stops being a personal failing and becomes a method of exercising power.
I suspect most people, liars included, would say this is wrong. Agreeing it's wrong is obviously not the lever, otherwise it would have stopped by now.
The US has a Constitution written specifically to prevent abuse of power, and it means bugger all when the people meant to enforce it look the other way. That's what's actually costing the country its credibility, not the lying itself but that nobody with the job of stopping it is doing the job.
I will not teach my son that lying, cheating or manipulating people is fine because it gets you what you want. Integrity is what you do when telling the truth costs you something, and he's watching the most powerful people on the planet demonstrate the opposite every day.
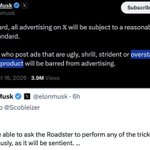
For example: and it is difficult to defend.
In 2017, Musk promised a car for delivery in 2020. Tesla took deposits of up to $250,000 from customers.
Nine years later, no production cars have been delivered.
And Tesla has repeatedly moved the goalposts.
There's a distinction between a failed promise and a deliberate lie. To establish the latter, you'd need evidence Musk knew the original promise was false when he made it.
But taking substantial sums of money against a repeatedly missed delivery promise, without delivering the product, raises serious questions about accountability.
and now nine years later there is a new Roadster announced.... feels like a snake oil salesman.
At what point does a promise that is never honoured stop being treated as ambition and start being treated as deception?
TRUMP and the DEMOCRATS MIDTERM PROBLEM
• Democratic House: 90–91% probability.
• Democratic Senate: 63–65%.
- @Kalshi @Polymarket
• Democratic sweep: 63%.
- @Polymarket
National polling: Democrats 50%, Republicans 42%. An eight-point lead.
- @RCPolling
Trump’s average approval: 38.7%. Disapproval: 59.4%.
- @RCPolling
Recent approval polls: 30% at @pewresearch to 43% at @Rasmussen_Poll.
Approval on the economy: 25%. Inflation: around 20%.
- @FT @focaldataHQ
Nothing is settled. But these are ugly numbers for Republicans and the Democrats can’t rest and count on it.
THE BOUNCE FAILED. THE DEBT GROWS.
Thats was a week that was.
⭐️ CPI, PPI and import prices all came in hotter than expected.
⭐️ Nasdaq lost 4.5% this week. CoreWeave lost 25.2%.
⭐️ Government bonds caught a safety bid while Washington reported another $2tn annual deficit.
⭐️ Europe outperformed. Japan’s higher borrowing costs remain a global risk.
⭐️ Brent finished near $110.
⭐️ Ukraine’s satellite restrictions exposed the cost of depending on infrastructure somebody else controls.
📉 STOCKS — DEAD CAT BOUNCE
Weekly moves:
Nasdaq: −4.5%
S&P 500: −1.9%
Russell 2000: −3.0%
Dow: +0.7%.
The Dow held up while technology and smaller companies took the damage. Money is becoming more selective about which earnings—and which balance sheets—it trusts.
VIX finished at 19.99, up roughly 35% over the week, after reaching 22.31 on Friday. Protection is getting more expensive.
🔥 INFLATION. THE PROBLEM IS STILL HERE
CPI: 3.7% annually, with core prices up 0.3% monthly.
PPI: 6.3% annually, up 1.3% in September alone. Producer energy prices jumped 10.8%. Strip out food, energy and trade services, and prices were still 5% higher annually.
Import prices: +1.1% monthly against 0.8% expected, and +8.1% annually. Those figures exclude tariffs. Duties add another cost, which businesses absorb in margins or pass through to customers.
Energy, imported goods, tariffs and financing costs. Businesses are being squeezed from several directions.
🥇 GOLD. I STILL LIKE IT
Gold sold off after CPI as traders priced a tougher Fed. It then recovered, trading around $4,165–$4,167 late Friday, although still roughly 0.7% lower over the week.
My view: gold around $4,145 looks like a gift over the longer term.
The market’s first reaction was that the Fed would fight harder. My concern is how far behind the problem it remains.
Higher rates can squeeze demand. They cannot reopen Hormuz, remove tariffs or make Washington balance its books. They also increase the cost of refinancing debt.
🤖 AI DEMAND DOESN’T PAY THE INTEREST BILL
CoreWeave closed at $61.39:
−11.9% on Friday.
−25.2% over the week.
Thursday’s 5.9% bounce disappeared the following day.
Dell lost approximately 23% over the week, showing how the pressure reaches equipment suppliers.
CoreWeave bond yields traded above 15% during the week. Its five-year CDS spread passed 1,100bp on Thursday. Oracle’s default protection also reached record levels. These are reported levels during the week, rather than Friday closing quotes.
Funding costs ↑ → project returns ↓ → refinancing harder → capex delayed → supplier earnings at risk.
AI adoption can keep growing while investors lose money. The equipment, electricity and debt still have to be paid for.
Revenue backlogs are useful. Cash flow determines whether the financing works.
🤖 ANTHROPIC GROWTH UP, VALUATION UNDER PRESSURE
Anthropic reportedly told investors Q3 revenue reached $16.8 bn, up 45% quarter on quarter, with an adjusted profit. Strong growth, but slower than Q2’s more-than-doubling.
Some investors are now discussing $1.5 tn, against earlier expectations around $2 tn. That is 25% lower, though no IPO price has been agreed.
Still no public S-1 located. The filing was confidential; reported prospectus details and private investor presentations are what we have so far.
“Adjusted profit” needs the adjustments. Revenue needs margins, cash flow and spending commitments alongside it.
At trillion-dollar valuations, even 45% quarterly growth can disappoint. That tells you how much perfection was already priced in.
My guess is that the numbers are shit (for a $2t val) and they will delay using a safety excuse.
🏦 US BONDS A SAFETY BID APPEARED BUT THERE IS STILL A MONSTER BORROWING PROBLEM
US 10-year: approximately 5.09%, down around 16bp over the week.
US 30-year: 5.44%, also down around 16bp.
Investors bought Treasuries as they cut equity risk.
My view is that this relief will struggle against the scale of borrowing still ahead.
Friday’s fiscal figures:
$5.40tn collected.
$7.40tn spent.
$1.992tn annual budget deficit.
$1.36tn gross interest costs, equivalent to roughly 25% of federal receipts.
Total federal debt above >$40tn.
Washington must finance that spending gap alongside refinancing maturing debt. Older, cheaper borrowing rolling into higher rates adds pressure to the interest bill.
Spending grew 6%. Receipts grew 3%. The gap widened despite record revenues.
This is a debt spiral and the credit-card binge mentality continues.
🇨🇳 CHINA EXPORT BOOM, DOMESTIC STRAIN
Shanghai Composite: 3,716 | −2.6% over the week.
Hang Seng: 24,187 | −0.1%.
Friday’s rebound did little to repair mainland losses.
September exports surged 36.3% annually, against 25.5% expected. Imports rose 31%, versus 24.5% expected.
The monthly trade surplus reached a record $133.5 bn, taking the first nine months to $938.1 bn. AI-related equipment and semiconductor shipments were major contributors. Part of the export surge reflects higher chip prices, so headline export growth overstates the increase in physical volumes.
The domestic picture is much weaker.
Producer inflation accelerated to 5%, above 4.5% expected. Consumer inflation was only 0.9%, below the 1% forecast.
Factories face rising energy and commodity costs while weak household demand limits their ability to pass those costs on. That puts margins under pressure.
💴 THE YUAN AND CAPITAL FLOWS
The yuan traded around 6.69 per dollar on Friday, near its strongest since January 2023 and heading for a third consecutive weekly gain. Strong exports are supporting the currency despite domestic weakness.
Beijing also pledged further financial-market opening, wider international use of yuan bonds as collateral and stronger offshore yuan markets. This is relevant to diversification away from dollar assets, although it does not establish that the dollar is losing reserve-currency status.
China is exposed to the same AI spending cycle supporting US technology. If financing pressure slows global data-centre investment, Chinese equipment suppliers feel it too.
🇯🇵 JAPAN CHEAP FUNDING IS GETTING LESS CHEAP
Japan’s 10-year yield finished around 2.94%, down 7.9bp over the week.
The 30-year finished at 4.01%, down 5.7bp.
Japanese bonds rallied too, but the BOJ’s policy rate is now 1.25%. Several brokerages expect another increase in December, while Ueda warned about inflation overshooting its target.
Higher domestic yields can encourage Japanese investors to keep more capital at home. More expensive yen funding also squeezes leveraged carry trades.
That matters well beyond Japan.
🇪🇺 EUROPE BETTER EQUITIES, SAME INFLATION CONSTRAINT
STOXX 600 finished at 644.74, gaining more than 2% over the week. Strong results helped Europe outperform the concentrated US technology trade.
But eurozone inflation remained 3.8%. The ECB has raised rates 50bp this year, taking its deposit rate to 2.50%, with another December increase priced in.
Germany’s 10-year yield was around 3.42% late Friday. Europe’s stronger equity performance does not remove its financing constraints.
🛢️ OIL — STILL FEEDING INFLATION
Brent settled at $109.86, up 3.72% on Friday, as Middle East supply risks kept prices elevated.
That feeds into freight, manufacturing and household bills. It also makes it harder for central banks to support weakening economies without risking another inflation surge.
🛰️ STARLINK / STARSHIELD — WHO CONTROLS THE SWITCH?
Ukraine says its military Starshield connections were cut when terminals travelled above roughly 160 km/h, disrupting drone operations. Negotiations to remove the restriction continued on Friday.
This concerns the speed at which terminals move. Musk says the US government controls Starshield; Trump denied ordering the restrictions. Responsibility remains unresolved.
Critical infrastructure comes with political and counterparty risk when another party can restrict access.
For Europe, sovereign communications capacity has a very practical value.
👀 NEXT WEEK: 19–23 OCTOBER
📊 Data
Mon: China GDP (4.4% expected vs 4.3% prior), industrial production and retail sales; Canada CPI.
Tue: UK jobs/wages; China loan prime rates; US housing starts, permits and pending sales.
Wed: UK CPI.
Thu: US jobless claims.
Fri: Japan CPI; UK retail sales; US/UK/eurozone flash manufacturing and services PMIs; final Michigan sentiment and inflation expectations.
🏦 US auctions
Mon: $95bn 13-week + $82bn 26-week bills.
Tue: $95bn 6-week bills.
Wed: $13bn 20-year bond reopening.
Thu: $26bn new 5-year TIPS.
$311bn announced, plus scheduled 17-, 4- and 8-week bills. Gross issuance includes refinancing.
🇯🇵 Japan
Tue: ¥700bn 20-year JGBs.
Thu: ¥500bn liquidity-enhancement reopening auction.
🇪🇺 Europe
Tue: UK 2036 conventional gilt; German green bonds.
Thu: UK 2031 index-linked gilt.
Watch the 20-year auction for sustained demand, TIPS for inflation protection, and Friday’s data for rising prices alongside weakening growth.
DEAD CAT BOUNCE. THE SELLING IS SPREADING.
⭐️ CoreWeave down nearly 12%. Yesterday’s rebound wiped out.
⭐️ IREN down 10%. Palantir down nearly 7%.
⭐️ Nasdaq down roughly 1.9%.
⭐️ Treasury yields higher. The earlier safety bid has faded.
⭐️ Brent above $109.
⭐️ Another hot inflation number — before tariffs.
Stocks ↓ → funding pressure ↑ → higher energy costs squeeze margins
📉 Stocks
Nasdaq: ~26,219, −1.85%
S&P 500: ~7,686, −0.75%
Dow: ~52,035, −0.27%
Yesterday’s modest Nasdaq and S&P gains have been more than erased. Tech remains the centre of the damage, but the Dow has also lost its earlier gains.
🤖 AI + Credit
CoreWeave $CRWV: $61.49, −11.77%
IREN $IREN: $27.33, −10.07%
Palantir $PLTR: $186.70, −6.88%.
CoreWeave bounced almost 6% yesterday. Today it has lost that gain and more.
Funding costs ↑ → project returns ↓ → capex harder to finance → equipment orders and earnings assumptions at risk
Demand can keep growing while the economics get worse. You still have to finance the kit, power the data centres and service the debt.
📊 Inflation
September import prices:
+1.1% monthly
+8.1% annually
Non-fuel imports: +6.0% annually.
These figures exclude tariffs. Import duties add another cost that businesses absorb in margins or pass to customers.
Industrial production rose 0.7%, but manufacturing increased only 0.3%, while vehicle production fell 3%.
Manufacturing growth across Q3 was just 0.7% annualised. Prices are running hot; factory growth is much less convincing.
🏦 Bonds / Treasury
US 10-year: ~5.13%, up roughly 4bp today. The earlier bond rally has reversed.
Treasury’s latest dealer questionnaire gave no explicit signal that cuts to long-dated auction sizes were imminent. Some investors had been hoping for one. Longer-term yields rose afterwards.
20-year reopening and 5-year TIPS.
Shares falling. Government bonds falling. Less protection when you need it.
🛢️ Oil
Brent: ~$109.33, +3.22%.
The earlier dip has gone. Higher fuel costs add pressure to household spending, business margins and the inflation outlook.
👀 What Next
Watch whether equities recover into the close and whether Treasury yields ease. Foreign capital-flow figures are also due, giving a lagged view of overseas demand for US assets.
The AI trade is under more stress ...
Japan still under massive pressure
US debt spiral is getting worse and worse.
DeReK WaTSoN retweeted

Echte innovatie komt uit Europa.
Tesla kan het dan een jaartje later ook eens proberen.
DEAD CAT BOUNCE. THE SELLING IS SPREADING.
⭐️ CoreWeave down nearly 12%. Yesterday’s rebound wiped out.
⭐️ IREN down 10%. Palantir down nearly 7%.
⭐️ Nasdaq down roughly 1.9%.
⭐️ Treasury yields higher. The earlier safety bid has faded.
⭐️ Brent above $109.
⭐️ Another hot inflation number — before tariffs.
Stocks ↓ → funding pressure ↑ → higher energy costs squeeze margins
📉 Stocks
Nasdaq: ~26,219, −1.85%
S&P 500: ~7,686, −0.75%
Dow: ~52,035, −0.27%
Yesterday’s modest Nasdaq and S&P gains have been more than erased. Tech remains the centre of the damage, but the Dow has also lost its earlier gains.
🤖 AI + Credit
CoreWeave $CRWV: $61.49, −11.77%
IREN $IREN: $27.33, −10.07%
Palantir $PLTR: $186.70, −6.88%.
CoreWeave bounced almost 6% yesterday. Today it has lost that gain and more.
Funding costs ↑ → project returns ↓ → capex harder to finance → equipment orders and earnings assumptions at risk
Demand can keep growing while the economics get worse. You still have to finance the kit, power the data centres and service the debt.
📊 Inflation
September import prices:
+1.1% monthly
+8.1% annually
Non-fuel imports: +6.0% annually.
These figures exclude tariffs. Import duties add another cost that businesses absorb in margins or pass to customers.
Industrial production rose 0.7%, but manufacturing increased only 0.3%, while vehicle production fell 3%.
Manufacturing growth across Q3 was just 0.7% annualised. Prices are running hot; factory growth is much less convincing.
🏦 Bonds / Treasury
US 10-year: ~5.13%, up roughly 4bp today. The earlier bond rally has reversed.
Treasury’s latest dealer questionnaire gave no explicit signal that cuts to long-dated auction sizes were imminent. Some investors had been hoping for one. Longer-term yields rose afterwards.
20-year reopening and 5-year TIPS.
Shares falling. Government bonds falling. Less protection when you need it.
🛢️ Oil
Brent: ~$109.33, +3.22%.
The earlier dip has gone. Higher fuel costs add pressure to household spending, business margins and the inflation outlook.
👀 What Next
Watch whether equities recover into the close and whether Treasury yields ease. Foreign capital-flow figures are also due, giving a lagged view of overseas demand for US assets.
The AI trade is under more stress ...
Japan still under massive pressure
US debt spiral is getting worse and worse.
GLOBAL RISK-OFF IS GETTING F'in UGLIER
⭐️ Japan and Korea are getting smashed.
⭐️ US futures are still lower after yesterday’s AI rout.
⭐️ Treasuries are catching a proper safety bid.
⭐️ The dollar is backing off as Fed hike odds ease.
⭐️ Oil is lower, but Hormuz and Saudi risk are still very real.
⭐️ TSMC is today’s big AI test.
Stocks ↓ → Credit spreads ↑ → Funding harder →
Treasuries catch a bid
📉 Stocks
Asia has taken yesterday’s US AI sell-off and made it worse.
Nikkei 225: ~64,185, -5.25%
KOSPI: roughly -7% to -8%
Taiwan: -3%
Underneath it, the same AI/memory names are getting hammered again:
Samsung -9.5%
SK Hynix -11.4%
SoftBank $9984 -10%
Tokyo Electron -7.3%
Kioxia -11.2%
This follows yesterday’s US damage:
Nasdaq -1.88%
S&P 500 -1.11%
SOX -4.3%
futures are pointing lower
That is the ugly bit:
US AI cracks → Asia gets smashed → US futures stay soft.
🤖 AI + Credit
Yesterday the selling moved beyond valuation.
CoreWeave $CRWV -15% area
Oracle $ORCL -8.8%
Nebius $NBIS -10%
Dell $DELL -11%
CoreWeave’s unsecured bonds are yielding around 15%, while credit protection on AI-linked names has widened sharply.
That is the mechanism to watch:
Funding cost ↑ → project returns ↓ → capex delayed → equipment orders at risk → revenue/EPS assumptions ↓
Financing stress moving through the supply chain.
🏗️ Primary Market
AirTrunk has delayed its planned $1.5 bn Singapore data-centre REIT IPO into 2027.
Firmus already pulled its multibillion-dollar float.
and Anthropic is the counterpoint to the funding stress. It reportedly told investors Q3 revenue hit about $16.8 bn, up 45% QoQ, and that it was profitable on an adjusted basis. (we know what that means)
So the top-end demand (we saw AMSL results) and monetisation are clearly real. The question is whether the rest of the AI infrastructure chain can fund the capex needed to keep up.
A $2t Valuation is narrative capitalism doing a lot of work to get a lot of stupid people to buy in.
AI stocks ↓ → AI credit wider → IPOs delayed → funding harder
That is where this becomes more than another bad week for tech.
📈 Bonds / Fed
Yesterday’s hot CPI initially sent yields sharply higher.
Then equities sold off hard enough that the bond market flipped.
US 10Y: ~5.14% overnight, down about 4bp
That is a proper safety bid.
Fed hike odds have also backed away from the post-CPI spike, with the market pricing roughly 31.6% for a 25bp move at the next meeting.
💵 FX
The dollar has backed away from yesterday’s 18-month high.
USD/JPY: ~157.9
EUR/USD: ~1.119
The yen is stronger, but nowhere near enough yet to call this a full carry unwind.
🛢️ Oil
Oil is lower this morning:
Brent: $104.67, -$1.39
WTI: $94.07, -$1.02. Reuters
That helps.
But the physical risk has not gone away.
Houthi attacks on Saudi infrastructure continue, Iran is threatening shipping through Hormuz, and two vessels have sunk in separate incidents. At the same time, higher Russian and Middle East supply is helping cap prices.
So oil is lower because supply expectations have improved a bit, not because the geopolitical risk has disappeared.
In fact with the MidTerms coming the Trump shit shows only option is to escalate Iran again to blame it them.
🇹🇼 TSMC
This is the big AI test today.
We already know revenue was strong.
What matters now is:
AI demand
CoWoS capacity
capex guidance
margins
any customer delays
If TSMC says demand is still intact, then the market’s problem becomes very clear:
Demand is not breaking. Funding is.
My weekend read arrived just in time
Looking forward to it … the reality of AI without all the hype and bullshit
Many thanks @manni_patel

No surprise there

AI Unwinds: Hedge Funds Just Dumped AI Stocks At The 2nd Fastest Pace In A Year As Net Leverage Tumbles zerohedge.com/markets/ai-unw…
