

Founder/CEO of Savvy Trader & Earnings Hub CoHost of BuyHoldRant Podcast: https://xitter.cf/t.co/sW4vyFRSmq My portfolio & trades - near realtime: https://xitter.cf/t.co/laiDRy8ocb
Scottsdale, AZ
Joined September 2008
- Tweets16.7K
- Following1.3K
- Followers42.6K
- Likes11K





Pinned Tweet
My portfolio (+812%) vs. S&P 500 (+83%). In 4 1/2 years since my portfolio has been public, I've outperformed the S&P 500 by ~10x.
I've been told consistently that it's nearly impossible to beat the S&P 500, yet I've been doing just that for ~25 years! Kind of wild.
What am I buying now? My portfolio is public and 100% free (link in bio). But if you must know, this year, I've been going heavy into $MU (my AI semiconductor bet, trading at a ridiculous forward PE of just 7, or a 70% discount to FPE of the S&P500), $META (my overall "amazing business" that's growing faster than peers with huge AI upside, yet trading at a massive discount) and $RIVN (my "future is EVs + Autonomy" bet, but on a company that has a ridiculously low valuation of just $22 Billion rather than $1.4 Trillion!).
I share my views and what I'm doing publicly, including alerts of when I make trades, but I don't give investment advice. Everything I share is for awareness and helping others learn from my transactions.
If it's helped you in any way, comment and say hi!
Ep 61: $META, $TSLA & $SPCX Earnings, Tesla Roadster, Muse Spark Opens xitter.cf/i/broadcasts/1vJpPNbBQ…
Join @dustinalper and I LIVE at 1pm Pacific / 4pm Eastern for Ep 61 of Buy Hold Rant where we'll talk about $META, $TSLA and $SPCX earnings, $RKLB, $MU and AI in general, plus the new Tesla Roadster demo, and sooo much more + your questions.
youtube.com/watch?v=vektZ_7l…
Each of $GOOGL, $AMZN, $MSFT, $META and $SPCX hope to bring 5-10GW of new AI data centers online in 2027. In SpaceX's case, maybe they hope to get to 20GW.
However, only @elonmusk is claiming that his 10-20GW will generate $500 Billion to $1 Trillion of ARR for SpaceX next year.
At this point, what's stopping the rest of the industry from saying "you know what, we can also sell our new capacity at $50/watt" and project MASSIVE revenue increases based on hypotheticals? Everybody should do this.
So what's the reason none of the others are making such claims? Are they dumb?
At some point, this level of hubris (confidently predicting 2027 $SPCX revenue at $500 Billion to $1 Trillion), becomes indistinguishable from a scam.
Because where will that revenue come from?
Elon is assuming there is infinite demand for data center rentals at $50 per watt per year, even though it costs less than $50 per watt to build a data center. His assumption is that if SpaceX can put up 10-20GW of DCs x $50 per watt, that = $500-$1,000 Billion of revenue.
I think at best, it's irresponsible to set such expectations with your shareholders, and at worst, it's very hard to tell it apart from what a scammer might say.
There's an extremely low probability that any of the vision training from the millions of FSD vehicles would be reused for Optimus. The training needed to drive a vehicle is vastly different than the training needed to operate a robot.
Ironically Farzad's video here actually makes this point pretty well, yet his headline/title for it seems completely off.
Obviously, they'll both use similar NN systems & vision, but almost certainly, completely separate training models.

It's ironic, but often times when companies have the most attractive price, people have the least interest in them. Just a little over 2 years ago, I was buying $RKLB shares at $3.57 (~$2.5 Billion valuation at the time), and nobody was interested in the company. Peak interest came after the company was $100-$150/share (at ~60 to $90 Billion valuation!).
The stock has lost favor again and now it's down to ~$30 Billion valuation, but, people are far more interested in $SPCX at $2 Trillion.
Here's an interesting thought experiment (not investment advice): Let's assume space companies could get a sustained Price/Sales ratio of 20:1.
For SpaceX to go up 100%, they would need $2 Trillion of market cap. At 20:1, it would need an additional $100 Billion of revenue.
For Rocket Lab to go up 100%, they would need $30 Billion of market cap. At 20:1, it would need an additional $1.5 Billion of revenue.
Rocket Lab already has > $2 Billion back log of concrete satellite and launch orders. Not to mention its purchase of Iridium and the revenue growth that might happen as a result.
SpaceX's largest revenue growth is coming from data center rentals at $50 PER WATT on 90-day contracts! A number that is unlikely to be sustainable on revenues that could disappear due to short-term contracts.
Just some things to think about.

Picked up more $RIVN and $RKLB today at fire sale prices.
Yes, these are high risk companies as both are still bleeding (losing money) every quarter and at least a couple years away from profitability. But, both companies have plenty of cash to weather short-term storms. I think shorts have written both of them off as dead and are going all-in.
Any good news on these two companies could trigger a short squeeze.

I recorded this video making the case for $RKLB in June of 2025, when the stock AND its revenue-run-rate was roughly 1/2 what it is today. Since this video, space has become far more important. Also Rocket Lab has solidified its ambitions into space-based communication (something I argued was a natural next-step for Rocket Lab) with the acquisition of Iridium $IRDM:
A few weeks ago, I was asked if I was planning to add more $RKLB shares since the price had dropped so much from a high of $150 not long ago. This is what I had to say at the time when the price was in the mid-to-high $60 range.
Now that the Neutron delay is official and the price has tanked to the low $50 range, I'm starting to re-add to my position. Today, I added ~9% more. If it goes further down, I might do more depending on how the rest of my portfolio is doing.
I continue to believe that Rocket Lab is in an incredibly good position to capitalize on the growing need for access to space in both satellite technologies and launch technologies. The Neutron delay doesn't change the core thesis long-term.

If $TSLA had continued to stay in the car business and introduced new models, it would’ve easily been a $200+ billion business (about 2x its current size). Instead, Tesla has stagnated and slowly gotten out of the car business before its new products (Robotaxi & Optimus) have had any revenue. 😞
Seems like a huge miss.
I canceled my Roadster order in Sept of last year after nearly 8 years of waiting on broken promises. Since then my $50k invested in my portfolio (which is public - link in bio) is now worth north of $80k. So no regrets!
Had I not put the deposit in the first place, my $50k would’ve grown to ~$500k in my portfolio!
So it’s safe to say I’m not putting a deposit on the new $TSLA Roadster. I’ll wait for its release and pay a premium!


The entire video by Marques is spot on. Excellent review of the $TSLA event!

The NEW Tesla Roadster Event: My Honest Reaction
youtu.be/scwlR0QHGOk

WTF!? Did @dkhos just say that it was unimaginable for $UBER to be a multi-billion dollar business before he became CEO? I believe the year he took the job in 2017, Uber had grown to over $7 billion business under founder @travisk’s leadership, so it was very imaginable!
Dara can take credit for getting Uber to profitability, but he can’t take credit for creating a multi-billion dollar business that was “unimaginable.” If it was unimaginable investors wouldn’t have already poured $15 billion into the company before Dara even joined!

It's OK to say:
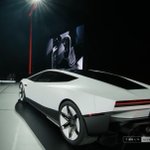
- New Tesla Roadster demo was most impressive demo in history
- And that the "Rocket" particular version of the car that flies is unlikely to ever ship (or be road-legal)
- And that no version of the car is likely to ship in 2028 if Elon's historical promises are any indication.
- And that this demo, and other AI/Chip/Data Center collaborations between $TSLA and $SPCX are likely to be the precursor to set the stage for the soon-to-be-announced merger of the two companies.
