

Institutional Investor. Private Markets (PE, PD, Infra, Real Estate): €1Bn+ invested. Primaries & direct Secondaries. Sharing insights on markets, deals & GPs
Paris, France
Joined April 2020
- Tweets1.6K
- Following371
- Followers9.8K
- Likes3.1K




Pinned Tweet
This is the story of the most profitable private equity buyout of all time and it’s French 🇫🇷
Company : Polyplus-Transfection
Sector : Healthcare 💊
Sponsor : Archimed
Here is a thread on how Archimed achieved a 300x MOIC on its initial investment 🧵👇
Fundraising Update!
I’m very happy to share some exciting news!
Our secondary fund opened for subscriptions just two weeks ago, and we’ve already secured €11 million in commitments!
We couldn’t have asked for a better start!
There’s still a long way to go to reach our €80–100 million target, but we’re off to a fantastic start!
The Institutional Limited Partner retweeted
Folks! I have some great news. We’ve just received distribution approval from the market authority for my secondary fund focused on small transactions. We’re officially ready to go!
I’m very excited to start fundraising in September, with the fund launch to follow in early October. We will have very attractive terms for early closers.
I’ve built this strategy over the last few years as an institutional investor around a simple conviction: some of the most attractive opportunities in secondaries are found in transactions that are too small and subscale for the largest or more established players.
Stay tuned!
I’ve seen a lot of PE secondaries deal flow lately. There is a lot of junk out there that I wouldn't even consider at a high discount because many are just coin flips.
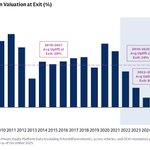
👉 Hard truth: a sizeable portion of deals done between 2018–2021 that haven’t already exited look quite poor. Even some of the top-performing GPs are facing setbacks; it seems no one is immune. Expect the number of zombie assets and zombie GPs to keep increasing. The dispersion is massive.
Many deals were bought at extremely high multiples, financed for a different rate environment, and hit by various macro shocks such as COVID, wars, inflation, etc.


The Institutional Limited Partner retweeted
AI is hitting Lower Mid-Market Private Equity faster than I expected.
Yesterday I attended the AGM of one of our LMM funds. Nearly every portco had rolled out AI initiatives of varying complexity, some early-stage, some more advanced. But across the board: real productivity gains and real P&L impact, already.
One example stood out. A specialised luxury consulting firm (50 FTEs) implemented AI primarily for document drafting, PPT generation, and similar tasks. The productivity gains allowed them to compete in larger tenders they would never have attempted before. Simply because they previously lacked the headcount to respond competitively.
Their CEO : “Thanks to AI, we now do at 50 FTEs what would have required 150 FTEs three years ago.”
But the real insight is why they’re winning against much larger firms.
Their clients don’t want to pay premium fees for armies of juniors producing insipid, templated insights. They want senior expertise. That’s what they’re buying.
Most of the actual document drafting is junior work. AI now does it faster and cheaper. This firm runs an almost entirely senior team with genuine industry expertise. AI handles the rest.
Small, nimble companies are taking market share from bloated incumbents and this is just the beginning

I start listening when a guy delivers 4x+ net MOIC on a buyout fund.


I had a meeting with a Top 5% European lower mid-market GP today, and one of the partners shared is thought about Software Investing 👇
« Software is not 'dead' because of AI, but you now have to be much more disciplined in what you back. The market reaction has been partly justified, but the idea that all software companies will be disrupted is intellectually lazy. Instead, there is a clear split between fragile and highly defensible software businesses.
The types of software we like have common characteristics
1. Backbone systems: software that sits at the core of a client’s operations and cannot be removed without breaking the business (e.g., accounting or ERP systems).
2. Ownership of proprietary data: the software generates and controls the underlying data, rather than just layering on top of existing datasets.
3. Strong distribution moat: customer bases built over many years through direct sales and deep integration, not easily replicated by a new AI-native entrant.
4. Regulatory barriers: software operating in regulated environments (e.g., certified platforms) is far harder to replace quickly.
5. Low tolerance for error: when mistakes have financial, legal, or operational consequences, clients are reluctant to switch to less proven AI-driven tools.
6. High technical depth: complex products with large codebases are more defensible than lightweight tools that can be rebuilt easily with vibecoding.
Bottom line: we remain positive on software, especially vertical, mission-critical, and regulated solutions. The current environment as potentially attractive for investing, as valuations may be over-correcting due to generalized fears around AI. »
I am computing some stats on our secondary track record, and I found that on a time-series basis, our weighted-average DPI after 18 months is 0.46x, which I think is quite good for buyout exposure.
This is what secondary is meant for: early cash flows
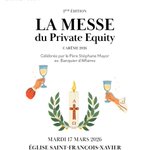
The market is so bad that they are organizing a private equity Mass in Paris 🤣
« Good Lord, offer us crystallized carried on unrealized gains, forgive us our 2% management fees, keep us away from adjusted EBITDA, and deliver us from add-backs. Amen.”

The Institutional Limited Partner retweeted
🚨As we prepare the launch of our Private Equity Secondaries fund dedicated to small deals (target Sept 2026) and given the current prolific deal flow, I’m looking for a partner able to provide ~€10 to 15m of warehousing capacity to seed initial transactions.
These deals would be transferred into the fund at launch (avoiding a blind pool for incoming investors and making it more appealing).
Economics are negotiable but ideally: pre-agreed yield and exit through inflows or option to convert into the fund with no fees and no carry.
DMs open, feel free to reach out
Another good report from Campbell Lutyens on secondaries. Some stats that caught my attention 👇
1. Average pricing and size by underlying strategy
2. Trend in pricing by underlying strategy
3. Evergreen still overpaying 330bps on average vs traditional closed funds
4. GP-led activity by sector and valuations


The independent sponsor model is gaining traction, with deal value increasing tenfold over the last 7 years.
The current state of the PE market is prone to the formation of this type of structure, and I believe we will see more and more going forward

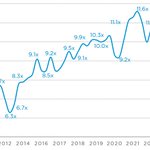
Private Equity - Valuations for European mid-market deals continue to decline, reaching levels not seen since 2015.
1. Argos Index fell to 8.3x EV/EBITDA in Q4 2025, down from 9.8x at the same time last year.
2. Only 7% of deals are now closed above 15x EBITDA, a record low
3. Mid Market M&A accelerated at year's end, supported by lower valuations and better alignment between buyers and sellers expectations


The Institutional Limited Partner retweeted
It's happening! In a few months, I will go on the other side of the fence after a decade as an LP.
With a bit of structuring and time to clear all the regulatory hurdles, our fund dedicated to small secondaries should be ready in Q3.
