

Cofounder @bondifinance Bringing corporate bonds onchain.
Joined October 2021
- Tweets2.2K
- Following401
- Followers348
- Likes5.3K




Akın retweeted

Full replay of the live with @kadiogluakin and the Bondi team: teapawt.org/i/broadcasts/2jPqMlBkm…

Akın retweeted

AMA with @bondifinance today at 15:00 UTC
Bondi brings publicly traded USD corporate bonds on-chain as Bond Tokens - fully backed 1:1, coupons paid in stablecoins.
On the call:
• @ali_sarp — Co-founder, Bondi Finance
• @kadiogluakin — Co-founder, Bondi Finance
• @daniilkozin — CEO, EasyMM
We’ll talk about real yield from corporate credit and how bonds become fully composable on-chain primitives.

Akın retweeted

Scarcity can only be allocated three ways: price, queue, or lottery.
Pick your poison.

Akın retweeted

Different tokens can depend on the same source of income. We trace who pays onchain yield and explore where corporate bonds fit in a portfolio.

Akın retweeted

classic pattern of incumbents fighting new tech.
we've seen this play out time and time again.
the harder they fight it, the more bullish i get.


Akın retweeted
Tomorrow, @kadiogluakin and @ali_sarp will be talking about corporate bonds and Bondi at 10:30 am UTC on SURGECAST.
Come join us!

The smallest piece of a corporate bond you can normally buy is $100K. That’s the only reason most people have never owned one.
Tomorrow on SURGECAST, the co-founders of @bondifinance discuss cutting that into $100 pieces and what it opens up.
Catch it live at 10:30 AM UTC 🔔

Akın retweeted

Este lunes en colaboración con @CFUCEMA @ClubUcema @twinfinance_ vamos a estar hablando de tokenizacion regional y sus usos de en DeFi
Gratuito a todos, presencial en la UCEMA o virtual en zoom!
Link below

Akın retweeted
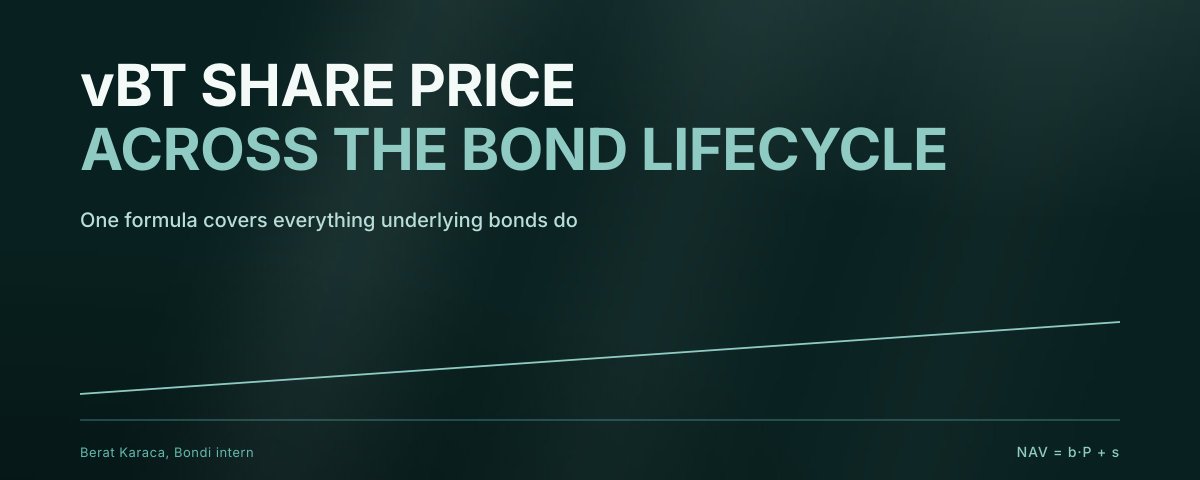
What is a Vault Bond Token share worth, and how does it move when the bond pays a coupon, gets called, amortizes or matures?
Written by our intern Berat Karaca, @caesar0sum.
Akın retweeted
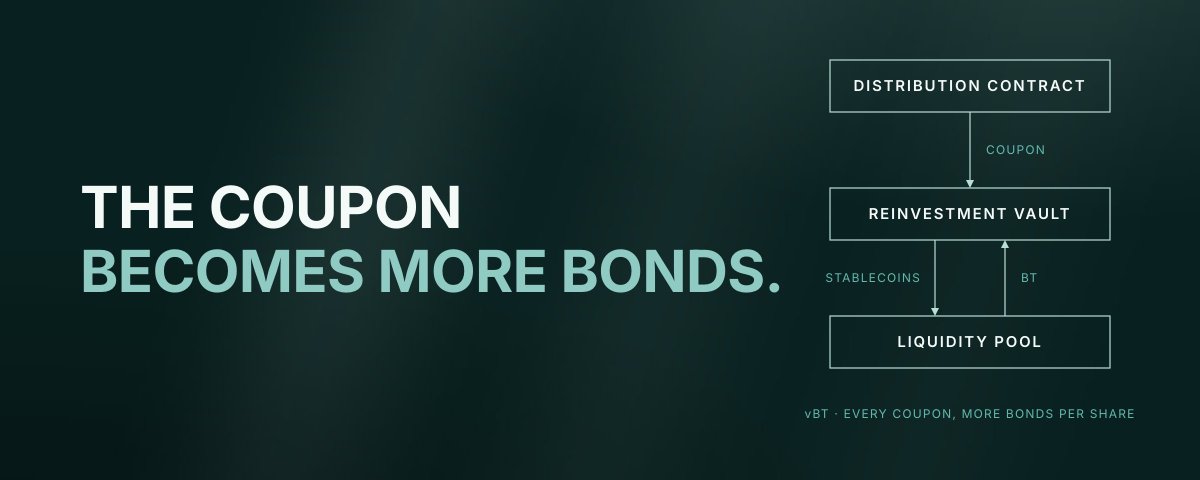
Reinvestment done mechanically, at any size: deposit Bond Tokens, hold one share, every coupon buys more bonds. 🌱
Why it matters and how it works👇
Akın retweeted

Perhaps retail has finally woken up to the fact that there are far better investment opportunities than home ownership


Akın retweeted

🟢🎙 Builders Hub #7 is locked in.
Next Monday we're sitting down with @bondifinance — the team putting real corporate bonds onchain, the kind that normally take $200,000 to touch.
We'll walk through how a bond actually becomes a token, and what it takes to bring a real-world asset into crypto.
📅 Monday, September 14 · 11 AM UTC
Set a reminder below so you don't miss it 👇


Akın retweeted
Compounding a single bond in TradFi: about $5M.
A daily rebalancing and compounding ETF with many bonds: more than $100M, impossible operationally.
On Bondi: only hundreds of dollars, same terms.
This is the Bondi thesis.
Akın retweeted

We have built the best infra to turn public corporate bonds into DeFi composable tokens while sticking true to the nature of bonds.
So now you have the underlyings:
Bond Token Investment Grade, btIG: 7.28% Investment Grade public credit
Bond Token Global Banks, btBANK: 7.65% Investment-Grade and Crossover bank perpetuals
Bond Token High Yield B, btHYb: 11.23% BB/B rated
Bond Token High Yield C, btHYc: 21.69% B/CCC rated
And the infrastructure:
Redemption Vault: clean off-chain exit when you want out
Reinvestment Vault: coupons auto-compound, vBT fully composable
Bondi vision is coming together.🐢
Now compose.
Strategy 1 — yield compounding 🌱: deposit Bond Tokens (BTs) into the Reinvestment Vault. Get Vault Bond Tokens (vBTs). Coupons reinvest automatically. Watch vBT accrue in BT over time. Truly passive fixed-income with auto-compounding. Requires FIVE MILLION USD for single-names (more than 50 million for baskets like above) in tradfi, done with 100s with Bondi.
Strategy 2 — collateralized borrowing 💳: deposit vbt into a lending market as collateral and borrow stablecoins against it. You retain full bond exposure (and the coupon stream auto-compounding underneath) while unlocking stablecoin liquidity for anything else, expenses, opportunistic buys, working capital. Multiple $100M+ vault curators we've spoken to have already greenlit lending against Bond Tokens.
Strategy 3 — leveraged looping 🪜: take the Strategy 2 stablecoin borrow, use it to buy more vbt, repost as collateral, repeat. If your basket yields 10% and you borrow at 5%, 2x leverage gets you ~15% net. 3x gets ~20%. All running on public credit; corporate bonds, uncorrelated to crypto markets. Looks degen but the underlying isn't.
We've run the numbers at survival calibrated leverages per basket: btIG at 2.47x → 9.46%. btBANK at 2.01x → 9.38%. btHYb at 2.08x → 12.04%. btHYc at 1.79x → 25.42%.
Blend the stack and you're looking at ~14.1%.
Strategy 4 — bullet exits 🎯: You don’t have to hold to maturity. Redeem whenever via Redemption Vault. No secondary liquidity headaches.
This is what DeFi didn't know it needed but needed badly. Uncorrelated, fully composable real yield. Real fixed-income, real institutional credit, made composable for the first time.
Merging the best of DeFi and TradFi. Someone just had to do it.
Bondi did it.
gBondi🐢
Day 68


I've talked about 50-100%+ returns in sovereign distressed debt. At Bondi we've publicly delivered 10-15% APYs with completed Bond Tokens, plus the Binghatti calls at ~170% APR and around 20% on our calls of the Chinese Real Estate bottom with Bond Token Chinese Real Estate, btCRE. And mind you that these are the ONLY calls we have made publicly.
Now on a personal account, I wanna share some of my personal watchlist. What are similar opportunities in public corporate credit right now?
Maybe the most most political trade in credit: China Vanke (XS1713193586, 3.975% Nov 2027).
Trading at ~55. 🇨🇳
To understand this bond you need the whole decade, not the last headline.
Vanke was once China's largest developer by sales, part state-owned, professionally managed, the one every analyst said would survive when Beijing drew its "three red lines" in 2020 and started deflating the biggest real estate bubble in history. And for years, that was exactly right. Evergrande defaulted. Sunac defaulted. Country Garden defaulted.
Yet when a Vanke bond actually reached its finish line during the panic, it paid.
January 2025 was the darkest stretch: the CEO detained, the first annual loss in Vanke's history, and Vanke's May 2025 dollar bond (XS2078641888, same issuer, same offshore structure as ours), four months from maturity, crashed to 59.8.
What happened next is the template for this whole trade: Shenzhen Metro, the state-owned largest shareholder, took over management and opened the wallet. That bond went from 59.8 to 91 in a couple of weeks and was repaid at par on schedule, May 12. Buying that panic returned ~70% in under four months. A 220%+ APR (north of 400% if you compound it). The market priced Vanke's death. The state paid par.
Now the right edge of the chart, the part that matters. Through 2025 Shenzhen Metro lent Vanke ¥31.5B across 13 tranches, basically paying its public debt for it, and our bond sat in the low 80s.
Then the cracks: widening losses, and in October the chairman of Shenzhen Metro quit after just 259 days. November made it real: the lending got capped, S&P cut twice to CCC-, and the bond took a sharp dive to high 50s.
\November to December got ugly fast: creditors rejected extension requests, Fitch went all the way to C, and the bond collapsed to 15 around the turn of the year. The worst ever in its history, by far.
Then end of January 2026, and the same movie again: Shenzhen Metro revived support with a ¥2.36B loan, extensions passed, the bond tripled off the bottom.
But notice the regime change, because it's the honest heart of this trade: the state no longer pays everything. Onshore bonds now get extended, not repaid. Holders take 40% upfront and wait a year for the rest. Ten bonds and counting. Through spring the bond chopped in the 40s as a ¥88.6B annual loss printed and an asset sale failed with zero bidders. Then July: a ¥519M loan (2.29%, collateral pledged this time) completed extensions on every 2026 public maturity, and the bond broke out from under 50 to the mid-50s. That's the staircase you see on the right.
Now look at who actually runs this company. January 2025: Shenzhen Metro's chairman takes the Vanke chair, ten Metro executives installed across the org. October: he's swapped for Huang Liping, a 30-year Shenzhen Metro veteran. June 2026: Huang becomes chairman of Shenzhen Metro TOO.
One man now chairs both the lender and the borrower.
Here's the punchline. The rating agencies give Vanke ZERO support uplift. Fitch's official reasoning: Shenzhen Metro is a minority shareholder that "does not control the board." That sentence was written weeks before the board became literally chaired by Shenzhen Metro's own chairman. The agencies rate the org chart of 2017. The trade is pricing the org chart of 2026.
Now the trade itself. These are the offshore notes. ~15 months to maturity. If they're repaid at par like every offshore Vanke bond so far: +81% to par plus three more coupons, roughly +90% total from 55.
IF instead the extension playbook crosses offshore for the first time, or the drip of state loans dries up: these notes sit structurally last in line, behind onshore creditors, behind the pledged collateral the new loans now demand.
Fitch's recovery rating on them is RR5, 11 to 30 cents. At 55 with a ~20c recovery the market implies roughly 40% odds of full repayment. Slightly worse than a coin flip.
And be clear-eyed about why it's 55 and not 85: the May 2025 par repayment happened while the state was still paying everything. The regime since November is minimum-viable support. The precedent proves willingness. It doesn't promise the ending.
You are NOT underwriting Chinese property. You are underwriting whether Beijing lets the company stiff foreign creditors 15 months before the finish line, while it's still writing ¥500M cheques to avoid exactly that headline.
Remember, this is a high-risk opportunity.
Day 66

Akın retweeted
I have a lot of @Apple stock--- and I miss Steve Jobs. Tim Cook must immediately increase the size of the screen... fb.me/Hjj8Y27p
Akın retweeted
A bond’s quoted price and the amount paid at settlement are usually different.
The quote is the clean price. The settlement amount includes accrued interest, making it the dirty price.
That is why the same clean quote can cost more on one day than another. 🧵
Akın retweeted
Met a German founder this week and asked him if all the stories one reads about the challenges of startups in Germany are exaggerated. "No, they're understated." Proceeded to describe spending a full day having a 90-page investment contract read to him (mandatory under German law; § 13 BeurkG) by a notary that then charged €30,000. That was for his first company. His second company, needless to say, was not incorporated in Germany.
Akın retweeted
We called this one publicly on March 10. ~169% APR in 20 days. Same name, second entry two weeks later, we called it again,~172% APR.
The whole corporate bond universe is priced continuously in the real market every day. Bondi tokenizes it. Redemption Vault (shipping soon) hands you the offchain liquidity to actually realize plays like this.
Case in point. 👇
Math is done. Past is past. Let's talk about how to make money now. 💰
It's not 1981. You don’t have a Volcker. But you have something else you can spot: panic, fear premiums, and geopolitical mispricings.
On March 10, 2026, we did exactly this at @bondifinance and called a 169% APR play:
🔗teapawt.org/bondifinance/status/20…
The trade was a Binghatti Sukuk (XS3145700491, 8.125% coupon, matures 2030). One of Dubai's most reputable luxury developers.
AED 12.43B (USD ~3.4B) FY25 revenue, nearly doubled YoY.
Gross debt leverage 1.9x. Net debt 1.1x. EBITDA interest coverage >9x.
The 40-year S&P default data for BB- implied a 1-year 0.88% probability of default.
(Fitch affirmed BB- three days after our article)
Missiles were flying in the region. Hands started shaking. The bond fell from $99.68 to $91.71 on geopolitics.
Our call was simple: at $91.71, you're locked into 10.79% YTM to 2030. If geopolitics normalize and the bond reprices toward $99.68 (where it traded before) in a month you will make 113% APR.
What actually happened was even better.
📈 Binghatti 2030 (March 10 → March 30, 2026). Recovered all the way to $99.76 in 20 days.
Capital gain 8.78%, coupon accrual ~0.5%.
Total return 9.26% in 20 days = ~169% APR.
14 days after our call, more missiles rained down.
On March 24, 2026, the 2030 briefly tanked again to $74.45.
Same day, in our Whales Telegram and @ZeusRWA's RWA Lounge, we pivoted to the shorter Binghatti Sukuk (XS2753304349, 9.625%, matures 2027) at $89.07.
📈 Binghatti 2027 (March 24 → April 20, 2026). Recovered to $99.71.
Total return 12.75% in 27 days = ~172% APR.
Two trades. Same name. Same month. Both worked.
But how could you have realized these gains with our Bond Tokens? People wrote in: "Cool thesis. Loved it. If it rips, how do I actually get my money out?"
Liquidity has always been the hard part of tokenized RWAs. Not anymore. Introducing Bondi vaults starting tomorrow.
Day 57

