




Pinned Tweet
The Militia Long/Short Equity ETF has launched! The ticker symbol is $ORR and it just began trading.
The strategy is similar to my hedge fund, investing in global stocks up to 150% long and 100% short. This strategy will typically have lower correlation and beta to the market than most public investments. This means that during a strong bull run $ORR will have a tough time keeping up. But in a weak market $ORR is expected to outperform.
My reasons for launching $ORR rather than growing my hedge fund:
Many of the investments in my hedge fund are illiquid and I won’t be able to trade them if my hedge fund grows too big. This is why I’ve been turning away new investors. However, well over half of my bets scale well and $ORR will invest in that portion.
The $ORR ETF will have a lower edge due to its larger scale, and thus it has a much lower fee to match. I have a strong opinion that hedge fund fees are incompatible with large AUM generally, not just for my fund. Most people don’t know it but Buffett pointed out that even Berkshire’s track record would have been mediocre with hedge fund type fees. This is by far the biggest reason I want to launch an ETF. I want to do right for the people investing with me, who are trusting me with their money, rather than sell out like most other hedge fund managers do.
The $ORR ETF has less risk than my hedge fund because it uses less leverage and isn’t short many microcap stocks, which can have extreme volatility. This is a more appealing product to risk averse investors.
The ETF vehicle has many benefits: Simplified, favorable taxes for the ETF holder. Can be owned on margin and in retirement accounts. Daily liquidity. Due diligence on ETFs is simpler than hedge funds, convenient for institutional investors. Compliance isn’t an issue for institutional investors. Allows me to rebalance longs without a tax hit. Both very small and very large investors can join, neither of which could invest in my hedge fund.
Expenses stated in the prospectus:
The 1.3% management fee is accurate, which is around .65%/year fee per 100% gross leverage managed.
The 18.84% gross expense ratio is very misleading. These items cause the stated expenses to be very high but are not real economic costs:
1. When a stock or ETF that I’m short pays a dividend it gets counted as an expense. In reality, whenever dividends are paid the underlying stock or ETF drops by roughly the same amount. Thus, the real economics are neutral. The ETF will be heavily short high dividend investments at the start.
2. When I short a stock or an ETF, I am paying to borrow the shares. On average, my larger scale shorts cost 1%/year to borrow. This is considered an expense. However, when I short sell I am simultaneously borrowing shares from one guy and selling them to someone else. That someone else pays cash for these shares, which the ETF holder earns interest on. Thus, I will be earning a positive carry on that short. But the way the “expense” gets calculated, the interest earned from being short does not offset the cost of borrowing.
3. The margin interest paid for being over 100% gross long. Unlike the first two items, this is a real expense but the expected return of the stocks we own is higher than the interest cost.
Frankly, the way the expense ratio gets calculated in the ETF prospectus is nonsensical. Regulators should update this number to better reflect reality. But since they don’t, and since most people do not understand this, ETF managers are reluctant to do anything in their portfolio that causes this official number to go up. Well, I say to hell with that. I’m just going to do whatever I think has the maximum expected value even if this hurts marketing to many potential investors.
Points about the $ORR ETF at launch:
* Until the ETF reaches ~$50-$150 million AUM, I will not be able to short more than 10 individual stocks or ETFs. This is due to the unusual mechanics of short selling in an ETF vehicle and associated implied cost. Thus, $ORR will be shorting mostly bad ETFs in its early days. This isn’t so bad. There’s a big edge in shorting some of these bad ETFs and I even make these same big bets in my hedge fund. But I want to be transparent: the ETF won’t have its full edge until we hit a bit larger scale.
* While the ETF has low AUM you should be careful with trade execution. Do not use market orders. You will get the best fills if you use limit orders and buy between 10 AM and 3:30 PM ET. If you're buying in large size, contact your broker and do a Request for Quote (RFQ) to get best execution. Also, if you want to invest >$10 million and want more liquidity, you can reach out to me and I can help coordinate with a market maker.
Regulation on public posts, or why I haven’t posted about the ETF until now:
Every post I make about the ETF needs to get approval, including replies to questions in this thread. The turnaround time for approval is 5 days and costs money. Thus, I won’t be able to reply to your questions here. Instead, I will gather a list of questions and write up a FAQ.
Oddly, I am allowed to reply to questions on podcasts. If you run a podcast and want to discuss the ETF, I’d like to go on.
-
Thanks to Sam Lee @svrnco for partnering with me on this. Besides financially backing it, there was an awful lot of overhead work and other hurdles when launching an ETF. He did a great job handling most of that work so that I could focus on investing.
For more information about ORR ETF, a prospectus, fees and risks militiaetf.com/
A guy like this publicly saying that China doesn't like the IRGC is a pretty strong signal.
I don't follow Chinese commentary much so I'm not sure how often they say this, or how the message has changed over time.

Tong Zhao is a senior fellow in nuclear policy and China studies at the Carnegie Endowment. Born 1983 in Henan province (mainland China), he holds degrees from Tsinghua University in Beijing, previously worked for the Beijing municipal foreign affairs office, and was based in Beijing with Carnegie’s Tsinghua center before relocating to Washington. He is from the PRC, not Hong Kong or Taiwan.
David Orr retweeted

Physicists in Okinawa have floated a diamond about a centimetre wide and pushed it up and down using nothing but the spins of electrons inside it, pumped by pulses of green laser light.
That object is roughly a hundred million times heavier than anything moved by spin force before. So, a quantum force now shows up directly on something heavy enough for gravity to matter.
David Orr retweeted

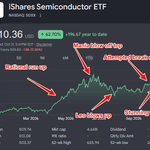
HISTORIC CRASH IN AI MOMENTUM.
Morgan Stanley’s U.S. TMT Momentum Factor has now collapsed 62% from its highs.
Even more remarkable, the factor has recorded 65 daily moves exceeding 5% in absolute terms this year, nearly matching the 70 such moves recorded during the ENTIRE 1999–2001 dot-com boom and bust.
These are not ordinary moves. Absolutely historic volatility and destruction in Momentum.

David Orr retweeted

CCC spreads have doubled from their lows earlier this year
Lots of deep-distress, pre-LME issuers lurking in here.

David Orr retweeted
Had a great time with Ethan.
Disclose: Ethan is not an LP and was not paid by Militia.
Militiacapital.com/disclosur….


Hedge Fund Manager David Orr (@orrdavid) on why he’ll back a delivery guy over a Harvard grad, as long as the track record is real.
David Orr runs Militia Capital, a ~$480M hedge fund. ~50% annualized, Sharpe 2.
“If you didn’t go to Harvard, they’re not going to give you money. They’re gonna lead you on for years.”
We cover:
- Edge is just reps. He's placed a few hundred independent bets every year since 2019, more in one year than a lot of hedge fund managers get in a decade.
- The two-hour rule: if he can't decide on a stock in an hour or two, he skips it. When a trade goes against him, he quits. "The market said I'm wrong, I'm wrong."
- 500 positions in his partition and zero notes. Some of his best shorts are down 40% and he's forgotten what the company does.
- The Gogo lesson: he spent 100 hours on a short and was right on the fundamentals (it's now $2), but it ripped to $20 first. All that research made him stubborn on the way up.
- The AI risk system: it groups the book into custom baskets like "Banks Done Right" and "yield traps," recalculated daily. A 25% bet can quietly become 45% in two weeks.
- How Militia recruits PMs: 95% of track records are junk, and one cherry-picker ran 30 accounts and sent the best one. The PMs who make it include a game show winner, a Spanish government worker and a programmer, with 0.15 cross-correlation.
- The best short seller in the world, quietly: 40% a year short only for years, and he still gets a tiny allocation at his fund.
- Why multi-managers' real business is marketing. Collect $2B a year in fees on $100B and it's "mission accomplished," whatever the returns.
- The long/short tax trick: harvest losses on losing shorts, and never cover one that's down 90%. No tax is due until it's delisted, which can take 10 years.
- $150M raised from one email asking LPs for $100M. He says he could raise a billion but won't, and admits they "must have gotten at least somewhat lucky."
- His AI stock map: hyperscalers locked customers into take-or-pay deals at ~35% return on capital. If compute prices crash 80%, the end customers get wiped out, not the hyperscalers.
- Is investing 99% talent? For big alpha, almost entirely. Pod shop alpha is teachable, maybe for 1 in 50 people rather than 1 in 10,000.
Highlights:
00:00 Intro
00:44 How AI custom factor baskets track dynamic correlation in levered portfolios
03:24 Sourcing non-consensus PM talent and verifying live Sharpe track records
07:24 Structuring carry and tax deferral to attract elite proprietary traders
12:50 Why institutional multi-manager platforms fail to back pure alpha
20:22 The two-hour research limit: Avoiding sunk-cost bias in short selling
27:58 Momentum screening vs deep value: Why top longs hit new highs
29:40 Why traditional finance books fail and what operator biographies teach
37:16 Why rapid technological adaptation beats traditional economic moats
39:26 Analyzing the AI trade: Why hyperscalers offer superior downside protection
44:57 Internalizing stock borrow desks to maximize net-of-fee fund compounding
55:25 Avoiding confirmation bias and why shorting revenue growth fails
01:01:42 Pod shop leverage factories vs raw discretionary alpha generation
01:07:12 Unplugging from market narrative feeds to preserve independent conviction
David Orr retweeted
Iran is trying to hold the line on its exchange rate, but depreciation pressure from the US blockade is just too big. That's why you get step changes in the Rial weaker and another one is just starting. The Rial is down 33% since the blockade restarted...
robinjbrooks.substack.com/p/…

A sincere question about NYC:
Why does the city allow people to set up shops on the sidewalk selling fake goods? It looks ugly, effectively steals from the shop owner's they set up in front of, doesn't generate tax, blocks walking, and frankly the people selling these good seem like a pretty bad bunch overall.
I could fix the problem in a week easily. But the city just lets it happen. Why?
Another construction example in Osaka, where the city understands that if all of these are an eyesore, then most of the city looks like an eyesore more of the time. It's not even expensive to fix this!

