

Empowering investors with AI-driven insights and comprehensive market analysis.
USA
Joined January 2025
- Tweets1.3K
- Following222
- Followers88
- Likes20


sagebytes.ai retweeted
$LSCC Lattice Semiconductor CEO Fouad Tamer: "Industrial embedded is just starting to ramp again. So there are no signs of any double ordering there. On the compute and comms, again, the demand is very strong. And what gives us the confidence, Melissa, is not that this booking is short term, it's extending well into 2028."
I think you need to believe what companies are saying in their earnings call for AI demand.
Microsoft CFO Amy Hood - "customer demand continues to exceed available supply, and Azure guidance for the next quarter is 49% to 50% growth in constant currency"
Alphabet - Management said it is working to bring more capacity online and that it could serve more Cloud demand if it had the capacity.
Amazon - Andy Jassy, CEO, said overall demand for AWS capacity remains exceptionally strong, and the company still expects about $220 billion of 2026 cash capex, with more in 2027.
Coreweave - Management said it has about 10x as much qualified demand as available capacity through the end of 2027
Oracle - Clay Magouyrk, Co-CEO, said demand for all accelerator types is far exceeding the ability to supply them, at least for the next several years.
$MSFT $ORCL $AMZN $CRWV $GOOGL

I remember getting a lot of questions about my forecasts after this article came out.
“SA’s estimates are much higher. Why are your numbers so low?”
“Is your analysis even sound?”
And now, just a month later, they’ve slashed their estimates by 30%…
Truly impressive analysis. So which numbers are we supposed to believe? What exactly has changed in just one month?
This is positive for AI trade as he is saying long term demand for compute is intact as users are doing lot of amazing things with AI.
$AMD $AVGO $SPCX $NVDA

OpenAI CEO Sam Altman on potential double-counting in AI chip demand:
Many AI chipmakers are assuming OpenAI, Anthropic and other major buyers will purchase most of their output.
"We're not all gonna be able to or need to buy ... all of our supply from every chip vendor."
74
$HALO CFO · On raising 2026 total revenue guidance to $1.86-$1.925 billion
"We now expect total revenue of $1.86 billion-$1.925 billion, an increase of $20 million at the midpoint, representing growth of 33%-38% over 2025."
1
116
$FLR CFO · On $10.9 billion of new awards and a $34.3 billion backlog
"New awards were $10.9 billion, led by LNG Canada, mining awards for copper, and a six-month extension for Savannah River. New awards were almost three times quarterly revenue, which significantly bolsters our expectations of future earnings growth. Ending backlog was $34.3 billion and is now about 70% reimbursable, in large part due to the LNG Canada award."
3
1
69

$BSY Executive Chair · On ARR growth of 13% and net retention at a record 110%
"We are excited to report 2026 Q3 operating performance, in which many factors contributed so impressively that our key metric, year-over-year ARR growth, after already notching up during each quarter of 2026, at 13% surpassed our annual outlook range. Our NRR, net revenue retention, for the quarter also reached a historical high of 110%, thanks to Nicholas and our teams for stalwart global execution."
19
🌐 Macro: Chetan Ahya, Chief Asia Economist, Morgan Stanley
“Asia needs to invest more in AI infrastructure. At the same time, Asian chipmakers and memory producers are lifting capex to meet demand of U.S. hyperscalers for building data centres.”
18
$ZETA CFO · On top Athena users growing revenue over 70% versus 46% company growth
"The top 25 Athena users grew revenue more than 70% in Q3 versus the company's overall growth of 46%."
48
$ROIV CEO · On no median treatment failure over 48 weeks in NIU
"As compared with placebo patients who failed therapy in around 12 weeks across the two studies, we did not see median treatment failure in this patient population in over 48 weeks, which is a phenomenal, I think it is the largest benefit ever seen for a non-steroidal therapy in NIU. It met the primary endpoint and all secondary endpoints in both of our studies, with almost two-thirds of patients achieving steroid-free quiescence, which is a major treatment goal for physicians."
15
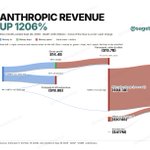
$ANT How Anthropic manages compute
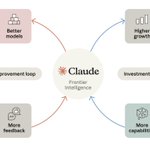
Anthropic says it treats compute as one shared resource: “We manage compute as a single, fungible pool from multiple strategic partners.” It shifts capacity between workloads based on expected productivity. The pool spans AWS Trainium, Google TPUs, NVIDIA GPUs, and AMD GPUs.
Commitments
Purchase commitments and leases total about $900.9 billion, mostly for compute and infrastructure. About $451.6 billion is due before December 31, 2030, most of the rest falls between 2031 and 2045, and about $70.7 billion is due within 12 months of September 30, 2026.
14
$U CEO · On Vector revenue up 126% year over year and 40% quarter over quarter
"Vector revenue grew 126% year-over-year and 40% quarter-over-quarter, which was double our guidance for 20% quarterly growth."
64
Goldman Sachs Research forecasts steady global economic growth in 2027:
The US, Japan, and the UK are projected to grow faster than the consensus of economist estimates.
Energy prices are expected to flip from an economic headwind to a modest boost next year.
AI spending is projected to keep boosting global economic growth in 2027. Our analysts expect nominal global AI investment to rise to $1.8 trillion next year.
The risks to Goldman Sachs Research’s forecast “are tilted to the downside”: Tensions in Iran, fiscal deficits, and lower-than-expected AI capex could result in slower global GDP growth.

Goldman Sachs Research expects steady global economic growth in 2027 amid lower energy prices and ongoing investment in AI.
Read the 2027 Outlook: click.gs.com/g0kj


51
$EPAM CEO · On AI-native revenue above $185 million and a raised 2026 target of $650 million
"Our third quarter came in better than expected, outperforming the high end of our outlook range for revenue, profitability, and earnings per share. In the quarter, the company generated over $185 million in AI-native revenues, once again delivering a sequential double-digit growth rate. EPAM now expects to generate at least $650 million in AI-native revenues in 2026, an increase from our original target of $600 million."
18
$JHX CEO · On fiber cement up 15% and trim-over passing 16 million square feet
"North American fiber cement revenue grew 15% in the quarter. Our fiber cement growth plan is focused on three conversion priorities: converting vinyl siding, winning against wood, and expanding our premium products. On vinyl, our trim-over method is moving the needle, opening up lower-priced homes that have historically been harder for fiber cement to reach, particularly in the Northeast and Midwest, where repair and remodel wood and wood-look siding alone represent an approximately $1 billion conversion opportunity. Trim-over, which surpassed 16 million installed square feet in the quarter, significantly lowers on-the-wall costs and improves contractor economics."
16
$JBS CEO of JBS USA · On U.S. pork margins deteriorating into 1H 2027
"Turning to U.S. pork, market conditions deteriorated rapidly during the quarter. Higher global supply and weaker demand have pressured prices and margins. We expect these conditions to remain challenging into the first half of 2027."
11
$OSCR CEO · On 2026 as the strongest year and raised 2026 operating earnings guidance
"2026 is the strongest year in Oscar Health's history. We delivered record profitability for the first nine months of the year, reporting earnings from operations of $1.3 billion and net income of $1.2 billion. We also expect to achieve several of our 2024 Investor Day commitments one year ahead of plan. Based on our performance year to date, we are raising 2026 earnings from operations guidance for a third time to a range of $850 million-$950 million. Our strong third quarter performance exceeded our expectations with improvement across all core metrics. Revenue grew roughly 70% year-over-year to $5.1 billion. Our SG&A expense ratio improved 350 basis points year-over-year to 14%, another record low reflecting the disciplined execution, greater fixed cost leverage, and AI-driven efficiencies."
2
131
$LAMR CEO · On share gains taken from local media, not other billboard operators
"I would say that the shift that's happening for us in our book is away from local network affiliate or radio broadcast. We're seeing a clear shift there. One of the reasons I highlighted our ex-political October was that I'm sure when you hear from the other medium, particularly local medium, ex-political, they're going to shrink. In October, which was an incredible political month for us, we actually grew ex-political almost 7%. That's why I highlighted that number for you guys. I would say the share shift for us is we're not taking it at the expense of our fellow billboard operators. We're taking it at the expense of other local media."
10
$TPR Coach CEO · On Coach North America up 7% and beating guidance
"In North America, this last quarter, we grew 7%, which is an acceleration from Q4 on a two-year stack basis, and of course, a beat to our guidance."
5
$NXST COO · On non-political ads down 5% and Q4 non-political down high single digits
"On a combined basis, non-political advertising was down 5% for the same reasons I just mentioned, partially offset by incremental revenue from the impact of the FIFA World Cup in the quarter and strong local digital revenues at Legacy Nexstar. Top-performing categories included gaming and sports betting, and banks, savings, investments. Bottom-performing categories included medical/healthcare, home repair and manufacturing, and auto. For the Q4, including TEGNA on an as-combined basis, non-political advertising is expected to decline high single digits, impacted by political crowd-out."
21