
A trader who never said no for a cup of tea or a game of chess
Bengaluru, Karnataka
Joined June 2015
- Tweets6.4K
- Following253
- Followers93.2K
- Likes6.7K





Pinned Tweet
Grateful to be featured in @moneycontrolcom
moneycontrol.com/news/busine…

One of the biggest shams that beginners have been taught is the concept of P/E ratio, where everyone is made to believe that buying something at a high P/E is a very bad thing and that it can never make money.
I'm pretty sure nobody would be able to explain how a stock like Zomato, trading at a P/E of 900, was able to give multibagger returns. How Nykaa, from its lows, was able to deliver multibagger returns despite having a P/E of 340. How Hitachi Energy again gave multibagger returns while consistently trading at a P/E of above 100.
The same goes for many other companies like Solar Industries, E2E Networks, Cupid, etc.
So, when you ignore high growth companies just because they trade at high valuations, you're more or less missing out on really good opportunities that could potentially become multibaggers going forward.
I did burst a couple of firecrackers myself, just for the fun of it. But I was genuinely curious about how a Chinese invention, which made its way into India around the time of the Delhi Sultanate, eventually became such an integral part of a hindu festival
1. China invented fireworks around 1,000 years ago, using gunpowder. They were initially used in celebrations and to ward off evil spirits.
2. Who brought fireworks to India?. Gunpowder and fireworks technology likely reached India through Chinese, Arab and Central Asian traders and military contacts around the 13th–15th centuries, when much of northern India was ruled by the Delhi Sultanate.
3. First evidence in India (1443 AD): Persian traveller Abdur Razzaq recorded fireworks being used during Mahanavami celebrations in the Vijayanagara Empire.
4. Mughal influence (16th–18th centuries): Mughal rulers and other royal families popularised elaborate fireworks displays during weddings, festivals and celebrations. However, fireworks existed in India before the Mughals.
5. How did fireworks become part of Diwali? By the 18th century, rulers, including Maratha rulers, were organising grand public fireworks displays during Diwali. Gradually, the practice spread beyond royal celebrations.
6. When did ordinary people start using them? Firecrackers became increasingly affordable and accessible during the 19th and especially the 20th century, with Indian manufacturing centres such as Sivakasi expanding production.
7. Were firecrackers part of ancient Diwali? There is no historical evidence establishing that. Diwali's traditions of lighting oil lamps and celebrating light existed long before gunpowder fireworks arrived in India.
Diwali did not originate with firecrackers. Fireworks were a later addition influenced by Chinese technology, Indian royal celebrations and eventually mass production.

Yesterday’s move in Nifty shows how skewed the indices are. Around 1,000 stocks went up and 2,000 fell, but Nifty still had a massive rally.
This is expected to some extent. When FIIs pulled out, these were the stocks they sold. Now that they’re buying again, these are likely to be the stocks they get back into, because that kind of money can largely be absorbed only by large caps.

After the recent rally, large-caps, mid-caps and small-caps have given similar returns this financial year. But because we give more importance to recent moves, we feel differently about the same outcome.
Mid-cap and small cap holders feel the market has rallied and they’ve missed out. Large cap holders suddenly feel their stock picking has been great. The returns for the year are similar. It’s the short-term move that changes how we judge our decisions.
Img 1: Nifty Returns
Img 2: Midcap Retuns


After this, I don’t think our finance minister can casually say, “FIIs will come and go.”
They have shown that when they decide to buy, years of underperformance can be wiped out in a matter of days.
Nifty has rallied 2,000 points in less than a week, and the buying has been massive.
What more proof do you need that favourable policies can bring money into the market?
The same thing can happen with domestic investors if you give them some relief. But unfortunately, the finance minister was right about one thing we are the “shock absorbers.”
When FIIs were selling, domestic investors’ money was used to give them an exit. Now FIIs are likely to get the tax relief, while Indian investors continue paying the tax.
If tax relief can encourage FIIs to invest, why can’t you offer similar relief to Indian investors?


Last week, instead of applying for one lot of Jio IPO, if you had invested the same amount in Reliance 1300 CE.
You would be sitting on ₹1 lakh profit instead of ₹3000 from the IPO
That's the power of options trading.
#hindsightprofits


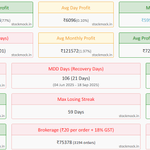
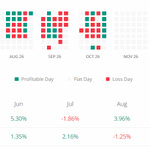
The portfolio was heavily tilted towards small, micro and mid caps, and we got hit hard this month. We got stuck in a few counters where we lost around 30% and couldn’t exit because of lower circuits. This is our first major underperformance since July 2025.
We were up almost 2% in F&O, but it couldn’t make much of a difference to the overall portfolio.
Now the portfolio has found more balance on its own, with a mix of large, mid and small caps instead of being heavily concentrated in small and micro caps. Sharing the latest holdings below.
Stocks: KOTAKBANK, GLAND, E2E, ANANDRATHI, HFCL, TECHM, MOTHERSON, LAURUSLABS, ACUTAAS, INDHOTEL, FEDERALBNK, COFORGE and CPPLUS.
Other holdings: SGBJUN31I, LIQUIDBEES and LTGILTBEES.

One thing I had a very poor understanding of for the longest time was the value of time and the importance of market size.
When we started building FinTarget, it was purely for our own use. Eventually, we realised there was a business opportunity, but we never really understood how big that opportunity could become.
It was only later that we realised the entire addressable market was probably worth just ₹15–20 crore, and even that was growing very slowly, especially with increasing SEBI regulations.
Now, imagine committing 5–10 years of your life to building something in a market that could potentially grow to ₹100–150 crore. Even if you manage to capture 20–30% of that market, you're still looking at a business generating ₹20–45 crore in annual revenue at best.
The problem isn't just the size of the market. It's also how fast the market can grow and whether people are willing to pay.
You could spend the same 10 years, put in the same amount of effort, and build something in a much larger market with significantly greater potential.
That's something I understood very late. Your effort might be the same, but the market you choose can make an enormous difference to the outcome.
Saketh R retweeted

Across Zerodha, here’s roughly the percentage of individual traders who are profitable:
- Futures: ≈50%
- Option sellers: ≈40%
- Option buyers: ≈10%
- MTF: too early to tell, considering it’s a new product
One of the unintended consequences of increasing STT and all the other measures to curb F&O speculation is that they may have pushed traders toward even riskier trading behaviour.
Yes, in theory, losses from buying options are limited to the premium paid. But buying options repeatedly, more often than not, ends with traders losing more money over time than trading futures or selling options. This is not to say that trading futures or selling options is low-risk. It’s a relative comparison.
There are a few reasons why options buying has become so popular.
Most traders don’t realise this, but STT is already one of their largest costs. As STT on futures increased steadily over the years, trading activity migrated from futures to options. Today, options are about 90% of all F&O trading activity.
At the same time, larger contract sizes have made trading futures and selling options more expensive in terms of the margin required. Buying options, on the other hand, is cheaper because it only requires the premium. Hence, more retail traders are buying options.
The other big factor is weekly expiries. Earlier, traders mostly traded monthly expiries. As more contracts started expiring every week, trading effectively became 0-day options. Traders began thinking in days rather than weeks and betting on price moves over increasingly short horizons.
All of these factors have also led to significant growth in MTF, or margin trading facility. With MTF, traders can borrow against eligible stocks and hold positions for extended periods. But MTF is long only.
The intent behind increasing STT, contract sizes, and all the other measures may have been to discourage speculation. The unintended consequence has been traders moving to riskier options trades.
This isn’t just about F&O, by the way. These measures also explain the spectacular increase in crypto F&O volumes. Crypto F&O exists in a grey zone where it’s neither legal nor illegal, and traders can get as much as 100x to 300x leverage on many of these contracts. In the last couple of weeks alone, I’ve come across multiple new platforms advertising crypto F&O contracts, including perpetual futures, none of which are regulated. That’s another unintended consequence of these regulatory measures.
The larger point I’m making is that any regulatory or taxation change has second- and third-order effects. These changes fundamentally alter market structure, and not always for the better, as the recent measures show. The risks always show up in the most unexpected places. And they show up especially in market phases like this one, when markets fall or trade sideways, and liquidity starts to evaporate. That shows up as wider spreads, higher impact costs, and a further drop in trading volumes.
This is perhaps one of the biggest challenges in regulating markets. Indian markets are no longer a backwater, the recent bear phase notwithstanding. We need careful thinking about second- and third-order effects, and thoughtful regulatory design and calibration.

I think one of the most underrated skills in trading is the ability to stick to one thing and keep doing it consistently.
People generally like trying something new. A new job, a new business, a new interest, or in strategy in trading, The moment something stops being exciting or rewarding, the natural tendency is to look for something else.
But trading makes this particularly difficult.
In most professions, doing the same thing repeatedly can become boring. In trading, not only does it become boring, but you can also keep losing money while doing it.
We see this cycle play out repeatedly. When markets are doing well, there is a huge influx of new traders. When markets become difficult and returns don't meet expectations, people slowly start leaving.
Everybody wants to participate when the market is rewarding them. Very few are willing to sit through periods when it isn't.
I've personally made this mistake too. Trying to do too many things at once, constantly exploring something new rather than focusing on getting really good at one thing.
The more I think about it, the more I feel that the ability to focus on one thing, understand it deeply, and have the patience to stick with it through difficult periods is one of the most underrated skills a trader can develop.
It's not just about finding something that works. It's also about being willing to stick with it when it temporarily stops rewarding you.
And I think that's where most people struggle.
It's not necessarily about sticking to one particular strategy, but something much broader. For example, if you take equity and option trading as a whole, rather than spending years and becoming exceptionally good at it, we often tend to jump into other things.
Instead of focusing on one area and striving for excellence, we end up trying to do too many things at the same time, without really developing expertise in any one of them.