Data & Research platform for tokens' value Revenue captured by token holders, and what the market pays for every $1 of it. TG: https://xitter.cf/t.co/kXIf8xPEno
Decentralized
Joined July 2024
- Tweets993
- Following44
- Followers2.8K
- Likes1.1K





Valueverse retweeted

if you use the @ether_fi card, hold ethereum:0xfe0c30065b384f05761f15d0cc899d4f9f9cc0eb or thinking to buy it
finally @valueverse_ai added ethereum:0xfe0c30065b384f05761f15d0cc899d4f9f9cc0eb, so i (we) have like the best and the most accurate data on what actually goes to holders. as a big ether fi fan and daily card user i gave it to my claude and started digging
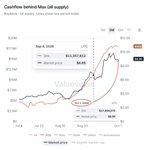
also, @DefiLlama shows $0 to ethereum:0xfe0c30065b384f05761f15d0cc899d4f9f9cc0eb holders since april, looks like it only tracks one old wallet. valueverse is the only tracker i found showing $sethfi stakers still got ~$400k last 3 months
tbh, sadly for me the token is pricey on holder cashflow, ~95x on staked ethfi last month, one of the priciest in the whole screener. yearly whole supply is ~69x, below hyperliquid:native 111x, ethereum:0x1f9840a85d5af5bf1d1762f925bdaddc4201f984 88x, ethereum:0x232ce3bd40fcd6f80f3d55a522d03f25df784ee2 76x (those two annualized, under a year of data)
what bugs me is the staker payouts are ~3x lower than spring, revenue roughly flat. back at spring pace staked ethfi would be like ~17x
i think it's bc of the september dao vote weekly ethfi buys go to card cashback and treasury, $sethfi isnt in the proposal. so token is bought weekly, it just goes to card users not stakers, and screeners dont count that
@MikeSilagadze is card cashback the main value accrual now, or any plan to route part of the weekly buys back to sethfi? would be great to see that multiple come down


Great to see that smart minds are so close to adopt P/FCFt
@thedefiedge we value holder revenue vs. Revenue-eligible market caps, not just liquid m.cap - it is much more detailed metric.
Your current multipliers show a bit different thing


Checking out our new (simple) UI tool with $NEST.
Revenue in 7D-365D periods + annualized at the same chart.
Easier than multiples, yet insightful:
- recent 30D were pretty solid (max annualized)
- longer period 180D steadily grows -> more and more revenue traction gained
You can dig into any token with that

Valueverse retweeted

Talked to @valueverse_ai folks yesterday. It was interesting.
Apparently, CRV and AERO are probably the easiest to evaluate in "TradFi" ways: prices peg to fundamentals and ignore negative or positive mentions in the media.
- CRV is the easiest: just based on your normal cash flow, just made ve-aware, but nothing complicated.
- AERO is trickier. It has semi-liquid NFTs which makes delta-neutral positions feasible, so shorts suppress the price. Also lots of inflation just has to be sold to compensate IL, which suppresses price below the "naive" estimate further. But possible to analyze.
- UNI and HYPE appear to be valued very far from their fundamentals, traders appear to buy the narrative there more than calculations.
Comparing results for buyback vs. ve-tokenomics.
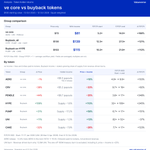
A small case study comparing two baskets consisting 4 biggest buyback tokens and 3 biggest ve-tokens.
Takeaways:
1. The peformance gap "buyback vs. ve" is much smaller that it was stated in the original post: $67 vs $300 -> $81 vs. $139
2. The highest valuation multiples are concentrated in major assets like $HYPE and $UNI. This suggests that market attention and valuation premiums remain heavily concentrated in the largest projects.
Ongoing observations:
1. Buybacks outperformed on price returns.
$100 invested in each of the four buyback tokens one year ago would be worth $130 on average today (equal-weighted across the group).
2. ve-tokenomics underperformed. The same $100 investment across each of the three ve-tokens would be worth just $72 on average.
3. But price performance doesn't tell the whole story. Both groups generate economic value for token holders beyond price appreciation.
4. To account for this:
- Buybacks: we account the reduction in total supply as a kind of an income, since each remaining token represents a larger share of the supply.
- ve-tokenomics: we account for revenue claimable by token holders.
5. $HYPE was the strongest price performer. Excluding $HYPE, the buyback group's average ending value drops from $130 to $115.
6. Accounting for accumulated revenue in the position:
Buybacks: $130 → $139
ve-tokenomics: $72 → $81
7. $HYPE and $UNI have relatively small supply reductions: just 1.6% and 1.3%, respectively. We calculate these figures against maximum supply (the FDV basis), since buybacks increase the proportional ownership of all remaining tokens.
8. $PUMP and $CAKE burned significantly larger portions of their supply, making their buyback-driven value accrual more substantial.
9. $PUMP and $CAKE trade at roughly the same P/FCFt multiples as $CRV and $PENDLE, around 17x, despite their fundamentally different value accrual mechanisms.
10. $AERO stands out with a P/FCFt below 10x, making it one of the cheapest assets in this comparison on a token-holder revenue basis.
All the results are presented at the infographic
Source: Valueverse API

I've been selling my positions that require locking.
Actually, I think some of these mechanisms are incredibly sophisticated. But the performance numbers are pretty depressing.
I was looking at @DefiLlama AI's data, normalizing a $100 investment across different token models over the last 12 months.
Here's what that $100 would be worth:
> Top 9 ve/locked tokens (>$10M): ~$67
> All 24 tracked ve/locked tokens: less than $50
> Buyback & burn tokens: almost $300
Of course, tokenomics aren't the only reason for this performance, but I think we're underestimating how much liquidity matters.
Great technology doesn't automatically mean a great investment.


We don't know why Defillama AI says that @CurveFinance annual revenue is less than $5m.
- It's simply not true.
- We estimate it $15.2m - $27.64m is our data.
- Maybe it was an AI Slop?
Our manually verified data for that:
- $7.19m fees for veCRV holders
- $20.45m bribes that protocol brought for all kind of veCRV holders (incl. @ConvexFinance owning a huge veCRV stake)
- $15.23m veCRV holders yearly income, EXCLUDING vlCVX bribes (so direct veCRV bribes only!)
With all due respect, DeFiLlama appears to lack bribe coverage and proper attribution of fees and bribe revenue to token holders.
You can dig into all numbers yourself👇

After yesterday's post about Curve, I got a few replies worth addressing.
First, I really don't want to be bearish on @CurveFinance. I love the protocol.
I'm using @DefiLlama AI for this analysis, so some figures might not be perfectly accurate.
A lot of people pointed out that Curve no longer depends entirely on its DEX business. That's true, but look at the numbers:
> 2023: ~$40M revenue, with 64% coming from DEX activity.
> Today: less than $5M revenue, with DEX still representing 34%.
Bribes have become a much bigger part of the business, which is actually encouraging given where CRV trades today.
But crvUSD minting and lending activity remain relatively small. I'm really hoping @yieldbasis helps revive this side of the ecosystem.


As more traditional assets move onchain, financial systems will need better ways to understand and compare the economics of assets across increasingly connected markets.
@vasily_sumanov will join @Genzio later today to discuss the shift to always-on markets and what it means for financial infrastructure.
Tune in at 12 PM ET.

Tomorrow, Genzio is bringing together industry leaders to discuss the shift toward always-on markets, what it means for traditional financial infrastructure, and the opportunities and challenges ahead.
🎙️ Hosted by @ActionCEO
Featuring:
@laissu | @BlockConGlobal
• Michael Carrighan | @OnPointWin
• @juga_btc | @SatsTerminal / @Oneswapcc
• @vasily_sumanov | @valueverse_ai
• @micobz | @ShiftRWA
October 13 @ 12:00 PM ET
Join us for the conversation!

Valueverse retweeted

Lots of beautiful data and research here on @valueverse_ai that is going largely unnoticed
h/t @vasily_sumanov
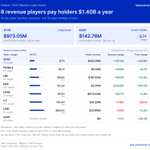
Highlights on @citrini's selection: 8 major revenue generators over 15 tokens
Valuation by cost Holders' Revenue* (P/FCFt 30D):
🥇@aerodrome's $AERO 5.7x, max-locked veAERO rev
🥈@pendle_fi's $PENDLE 16.1x, vePENDLE** rev
🥉@uniswap's $UNI 36.0x, $UNI buybacks rev
*Lower number corresponds to higher token holder's revenue more per unit of token price: 5.7x means that $1 of revenue/year requires owning $5.7 of token equivalent
**vePENDLE is taken since the majority of @pendle_fi revenue is still distributed to vePENDLE, not sPENDLE
Source: Valueverse Data & API


NEW ASSET ADDED: @Lighter_xyz
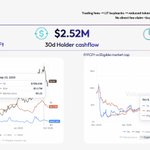
ethereum:0x232ce3bd40fcd6f80f3d55a522d03f25df784ee2 is trading at 125.36× 30D Holder P/FCFt.
We calculate P/FCFt against FDV, using the remaining token supply as the valuation base.
For ethereum:0x232ce3bd40fcd6f80f3d55a522d03f25df784ee2 , that is 984.36M LIT × $3.91 = $3.85B FDV.
Against that, ethereum:0x232ce3bd40fcd6f80f3d55a522d03f25df784ee2 generated $2.52M in holder-attributable buyback value over 30 days.
The cashflow side is worth watching closely.
$492.5K was generated over the last 7 days, versus $2.52M over 30 days.
P/FCFt puts ethereum:0x232ce3bd40fcd6f80f3d55a522d03f25df784ee2's FDV against the cashflow accruing to holders, rather than looking at market capitalization in isolation.


NEW ASSET ADDED to Valueverse: @ponsdotfamily
$PONS is at 1.42× 30D Holder P/FCFt.
$16.05M of holder-attributable buyback value over 30 days against a $276.6M eligible capital base.
$PONS is a premier Robinhood launchpad, and September’s @RobinhoodCrypto activity shows up clearly in the numbers.
But the run-rate is already cooling: 7D holder cashflow is $1.38M, versus $16.05M over 30D. Free gas ended September 29. The next few weeks will show how much of the September activity was structural.
note: P/FCFt = how much the market pays for 1$ of revenue

ALT $PONS holder cashflow Data source: Valueverse

A while ago, we teamed up with Yield Basis and delivered "A State of BTCFi", a joint report on how BTCs are used onchain.
You can read it in the @yieldbasis article👇
The results are straightforward:
• Only ~0.5% of existing BTCs or 246k are tokenized (can be used productively onchain)
• Less than 50% of that (or ~104k only) are deployed somewhere
• BTCFi has two clear leaders $cbBTC, $wBTC and one small runner-up $tBTC
• The main use case is lending accounting for >80% of productive BTCs
• Only the minority of BTCs are deployed to DEXes (mainly BTC-BTC or BTC-ETH pairs)
We are not talking about that lending yield is <0.01% and all these BTCs are mainly used to borrow something else.
BTC staking is heavilly subsidized, and LPs struggle to deposit to LP pairs due to Impermanent Loss.
This report was covered by @BitcoinNews, @HTX_Global, and many others.
BTCFi is so early.