

ShitCo connoisseur | focus on biotech | long form stuff might end up on the stack | Why so serious it´s only money | NFA
Joined February 2021
- Tweets2.3K
- Following289
- Followers3.3K
- Likes1.5K





$RLYB crawling towards merger closing. Took another look at valuation. At PIPE price with Tier1 investors, company was valued at ~535mln Equity Value with ~297 mln in cash is my guess (PIPE + Avenzo bringing decent cash, >100 mln in June) -> 240 mln EV.
At current RLYB price of 15.6$ , NewCo is valued at 365mln market cap for an EV of only ~70 mln. 32% discount to market cap, 70% discount to EV compared to merger valuation. (All numbers ex div)
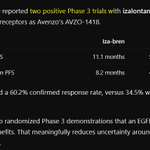
EGFR/Her3 bispecific (AVZO-1418) with updated Ph1 data on Nov 18. Just in October $BMY had pretty strong data for this MoA (see picture - maybe even too strong?).
Let´s see, will be interesting as the stock will be quite a low floater after dividend of 13.9$ is out of the stock. Think very decent risk/reward with large discount to PIPE. What´s the worst case here, losing 1 buck? With 1.3$ upside to just the price investors paid in PIPE to invest 215mln $


4) $RLYB the special div estimate came in a tiny smidge below my estimate (I was right on $ / lazy on ITM option treatment)
Other than that, I think the downside at/around 16 is very negligible with decent upside.
teapawt.org/AnotherBio/status/2087…
$XBI always amazing how biotech gets pulled into any high beta drawdown no matter how unrelated.
Even down more than $QQQ as I´m typing and that´s with all the pharma stocks in there. Pretty remarkable.
Anyway, buying a bit here or there, but lots of stocks didn´t move too much on a two-day-basis tbh.
Apart from the stuff I wrote about, like $NRIX here, $KYTX appears cheap to me, $BEAM now flat after great regulatory news. Also gambling a bit in more spec stuff ($LXEO $QURE & more stuff wating to gap down 50% into your face).
Reducing my $XBI hedges a bit but feel bad about that. Which might be a good sign?
$AVR Add $EW reaching 5B$ runrate and increasing guidance to the pile of bullish developments over last year

Nah. We´re still probably 5-8 months from full enrollment and then a further 12-14 from readout, still early. What I will say is that my enthusiasm for sure has not waned. I mean we had a huge M&A comp with MiRus, insider buying a nice chunk above 9$ and a pretty insane comp package with 21.5$ / 41 $ / 61.5$ stock VWAP as a necessity to trigger the PSUs.
teapawt.org/AnotherBio/status/2057…
teapawt.org/AnotherBio/status/2062…
teapawt.org/AnotherBio/status/2102…
AnotherBioInvestor retweeted

$FULC is ridiculously cheap.
Stock at $3.70. Special dividend of $3.52. That leaves just $0.18 for the remaining business.
The deal values that stub at ~$0.41 per share, including $20.3M net cash. That's a ~55% discount to the PIPE-backed transaction valuation after the special dividend.
And now there's potentially an additional asset sale on top. Even $5M would add another ~$0.07 per share.
Crazy pricing.

Second thread, companies that are going to RM in the forseaable future (mostly 0-6 months but not exclusively). Warning: SpecialShits, some with shitty liquidity.
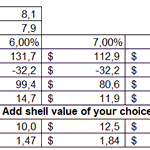
What´s important to note is that the value allocated to the shell recently rose to ~15-20 mln (see BOLT HOWL) from 7.5-12.5 earlier in the year. Means upside on small market caps can be huge, also means it is risky if you underwrite it before it happens. Draw your own conclusions.
Some of these companies are risky, but I´m 90% sure there are some 50-100% gainers in here. Given the above dynamics, some of these are quite small / illiquid, but OTOH if you get a 20mln shell premium on a 10-20mln market cap already trading sub net cash... Well if I have to explain that, this is not your thread ;-)
This is about getting into AEMD, TCRT, NXTC, BOLT, BOLD etc. before the RM happens.
As the $XBI continues its regular modus operandi of $MRNA and $TWST going up 7% a day, I wanted to share a bit of what I like currently and why. It´s a lot, so I will split it a bit. I think. I´m just making this up as I go.
Went from like 20% net long to 80 (kind of happened somehow, will try to lower a bit near term towards 60ish).
Starting with Reverse Mergers (RMs) with a signed DA. Will follow up with companies that I think will announce a DA soon.
In general I think the quality in RM-land is still very decent and we see few trash RMs (which used to be the norm until maybe 2-3 years ago).
Random order. You will be SHOCKED though to see what #7 does! (no you won´t, stupid clickbaits...)
6) $ARTV from yesterday. I guesstimate they will have 4.6$/share in net cash mid year 2027 but I might be very wrong on the cost of monitoring existing patients (to prevent further deaths). Still, it is a large cash shell so impact will not be that huge.
The very large caps though often don´t have that strong of a reaction (see FULC), so maybe you´re better off waiting for better prices or even buying after an announcement? Hope they will pay a large dividend as well, in which case the risk to buying this here sub 4.3$ is probably negligible.
Obv shell value has not that much of an impact on a ~235 mln$ market cap. Tend to think I´m a bit early too this, but I like to be involved early to get to know the stock / tape and we have seen some very quick transactions recently (sub 60 days from strategic alternatives announcement until DA)
As the $XBI continues its regular modus operandi of $MRNA and $TWST going up 7% a day, I wanted to share a bit of what I like currently and why. It´s a lot, so I will split it a bit. I think. I´m just making this up as I go.
Went from like 20% net long to 80 (kind of happened somehow, will try to lower a bit near term towards 60ish).
Starting with Reverse Mergers (RMs) with a signed DA. Will follow up with companies that I think will announce a DA soon.
In general I think the quality in RM-land is still very decent and we see few trash RMs (which used to be the norm until maybe 2-3 years ago).
Random order. You will be SHOCKED though to see what #7 does! (no you won´t, stupid clickbaits...)
10) $TCGX same approach, a "why the fuck not"-long around NAV
teapawt.org/AnotherBio/status/2113…
$TCGX bought a ton around 10$. AI says trust is ~10.07 so you make T-Bill +50 bps in a couple months and have a free call option on the deal receiving actual interest before closing.
I´m 90% sure we just saw someone from the IPO participate in the PIPE, sell their shares and taking some free money off the table.
Literally 0 reason to not be long this (sub trust) imo
11) Watching $TCRT but a lot of RMs trading below PIPE currently, don´t see the need to pay a premium here. PIPE 1.43$/share