



Auber retweeted

Today, we’re introducing the Aven Home Purchase Line. Go from open-house to owning a home in 7 days.
Buying a home with a mortgage used to mean finding the right place, then waiting weeks for financing to catch up - this process is broken.
At Aven, we’ve spent a lot of time thinking about how to build new financial products and make them an order of magnitude better for consumers. The mortgage has been one of the hardest and clunkiest products for decades, so we created a new way to buy a home.
We’ve already helped someone become a first-time homebuyer in Tucson in 67 hours. Thanks to @morganb , @nejatian , @BradBonney ,and our friends at @Opendoor for helping make this possible!
Read more in Forbes: forbes.com/sites/jeffkauflin…
Aven Financial, Inc. NMLS #2042345. Accounts are made by Coastal Community Bank, Member FDIC. NMLS #462289. Equal Housing Lender.
Auber retweeted

See you next week in Dallas for the @Opendoor Pickleball World Championships.


Auber retweeted

Many have tried to read the tea leaves this way.
Arizona tax records and recording will show you the purchase price, not the net.
For example - my wife and I bought our home for ~$720K in March. Topline price and that’s what records w/ county.
What it doesn’t show: (cont..)

Most $OPEN investors are waiting for November 5 earnings.
I'm looking at something else.
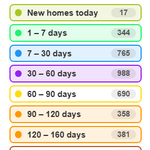
Actual homes Opendoor bought and resold in Maricopa County, Arizona.
We're matching property records to examine what OPEN paid, what it sold for, and what that might tell us about its unit economics.
The data arrives unevenly. It's only one county. And gross resale spreads aren't profits.
But it's an independent way to investigate whether the turnaround is showing up in real transactions.
I've published the research, preliminary findings and limitations for my paid subscribers.
The documents are the moat. The argument is the reach.
Subscribe to read it.
Auber retweeted

this is what I’ve been up to at Opendoor for the past month 👀
we are rolling this out gradually.
should be live on 3,000+ homes!


Auber retweeted
we made a fun little tool to make it easy to check your home value on opendoor at any time.
opendoor.com/home-value-esti…
Auber retweeted

Outside Opendoor, mortgage rates are above 7% for 30 year fixed loans. On select Opendoor homes, you can now get 4.99% on a 5/6 ARM (APR 5.849%).
We own the homes. We offer the mortgage. So we pay to bring the rate down to help families keep moving.
All mortgage services from Opendoor are provided by Opendoor Home Loans LLC; Company NMLS ID #2810193; 1295 West Washington Street, Suite 115, Tempe, AZ 85288; (480) 618-6760. Qualified buyers. Terms: opendoor.com/drop

Auber retweeted

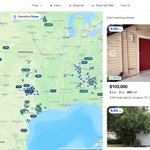
4.99% on a 5/6 ARM on select Opendoor homes for qualified buyers (APR 5.849%). Find them on Opendoor Drops, a new set of homes every Thursday.
🔹 See the rate and estimated payment on each home
🔹 Open the listing or start preapproval in one place
🔹 Each drop runs for one week only
See the drop: opendoor.com/drop
All mortgage services from Opendoor are provided by Opendoor Home Loans LLC; Company NMLS ID #2810193 (nmlsconsumeraccess.org); 1295 West Washington Street, Suite 115, Tempe, AZ 85288; (480) 618-6760. Qualified buyers. Terms: opendoor.com/drop
#Opendoor #HomeBuying
Auber retweeted
We’re building out the founding team for Opendoor Toronto.
If you work in engineering, data, ML, or infosec, come meet us on October 7. We’d love to hear what you’re working on. RSVP here:
docs.google.com/forms/d/e/1F…

Auber retweeted
There has been a lot of speculation lately about where Opendoor is on the path to ANI break-even, and I worry some folks think we are further ahead than we actually are. Rather than have you guess, I want to do two things. First, give you a direct update on how Q3 is tracking, and second, start releasing numbers more frequently so you can track our progress for yourself and hold us accountable.
To say the thing up front: we are not at ANI break-even yet. What we are seeing in the actual numbers of the business this week, the speed of underwriting, the accuracy of our models, the response from our users and the forward revenue created are all going very well. We’re making lots of progress, but rebuilds are bumpy.
TL;DR: The worsening housing market at the end of August pushed us roughly six to eight weeks behind on our Adjusted EBITDA guideposts, meaning the twelve-month window in which we expect to be adjusted EBITDA profitable now starts this quarter rather than last quarter. For Q3, we expect revenue to increase 10-15% year over year, Contribution Profit dollars to increase 70-75% year over year, and Contribution Margin to land between 3.2% and 3.5%. We still expect to exit 2026 ANI-positive on a twelve-month go-forward basis.
On our first earnings call I told you we would make the right long-term decisions for the business, not manage it around a quarterly number. August tested whether we meant it.
For most of its life as a public company, Opendoor sold homes slower than the market. Between our IPO and my start date, we cleared at roughly 85% of market pace and lagged the market two days out of every three. We held on to homes under the belief that waiting protected margins. Holding homes was our own version of bloodletting, the "cure" for weak margins. It did not work, and it made this company fragile.
Over my first year, we changed that. We now clear significantly faster than the market, beating it nearly nine days out of ten. This is our job: clear faster.
When we reported earnings in early August, July contribution margin was tracking ahead of our plans and the housing market looked like it might be stabilizing. Instead, the last two weeks of August were among the worst we have seen for housing in years. Clearance slowed further and delistings stayed high. That is not an excuse - it’s just what happened.
We had a choice. Slow sales, protect the margin number, and let homes age. Or price to clear. Old Opendoor chose the first option for years. It made the quarter look better, but it made the company worse. We are not doing that again. Time has a cost, and selling homes fast is the discipline this business requires. We are going to clear homes, even when that hurts margins.
Our job is to sell homes, not park inventory or pull listings offline when things get tough. The market got worse, but it did not break our resale engine. We are still clearing faster than the market. That is part of the business we rebuilt, and it held. Don’t confuse any of this with the business moving backwards. The business is in materially better condition today. Revenue and contribution margin will both be higher year over year. And as the rest of the rebuild catches up, a market like this will hurt us less going forward.
Nothing longer-term is changing. We expect Opendoor will be ANI-positive on a twelve-month go-forward basis exiting 2026. That depends on buying fast and selling fast. If margins were resetting permanently, that would change things. That is not what is happening. We are repricing one book of inventory and clearing it instead of rolling it into next year.
To help you follow all that we are doing better, both on sales and acquisitions, we are going to give you more to track every week on accountable.opendoor.com. Just as you should not have to wait until earnings to see what is happening on acquisitions, you should not have to wait to see how many homes we sold or how fast we cleared.
Last week, we sold 223 homes, and cleared 19% faster than the market, adjusted for delistings. The weekly numbers will be noisy, just as the acquisition numbers were when we first started publishing them. What matters is the trend: as we buy more homes, are we selling them at the pace we planned and staying ahead of the market or not? And when we are behind, you will see it for yourself.
I told you how we would manage this company: for years, not quarters. Twelve months from now, judge us based on that. Either we fixed the company or not. The core metrics say we are on track. For Q3, year over year, we expect margin to be up. Revenue up. Velocity up. The end of August was absolutely brutal for housing and pushed us back by roughly six to eight weeks. We’re not going to take that sitting down.
Kaz
(fyi, regular disclosures on this type of thing where we release weekly numbers etc are on our IR page, investor.opendoor.com)

Auber retweeted
Opendoor mortgage is out of beta. The most AI pilled mortgage product designed to help average Americans become homeowners. A fair and honest rate. Built to cost less.
opendoor.com/mortgage
Auber retweeted
Opendoor exists to tilt the world in favor of homeowners. And it’s not an easy time to be one if you’re looking to sell.
Days on market are high. 1 in 7 deals dies before closing. And a new report from Realtor.com shows the share of cash sales are fading. That’s why today, Opendoor is partnering with Realtor.com to bring the certainty of a cash sale to more sellers.
opendoor.com/articles/opendo…

Auber retweeted

Yesterday Kaz bought 27,625 shares of $OPEN for roughly $100K.
I see a lot of people write: "Pathetic sums".
Before you spit out things like that without thinking, you must understand that the world is bigger and far more complicated, than your limited mind seems able to process.
Even me, who am not American, who operates in a different stock market with different rules, know that things are sometimes more complicated than they seem.
So I did what every reasonable person would do: I tried to find information about this topic and I found this:
SEC Rule 10b-5 says it is illegal for a CEO to trade (buy or sell) when he/she possess material non public information that an investor would see as important and that this has not yet been published or disclosed for the market.
EVEN IF the CEO is not actively trading on that information, trading while aware, can create a legal risk.
This makes large positions difficult.
I also found that a $100,000 buy is the practical maximum that can be bought without future complications.
In Kaz case, the Form 4 filing said that the purchase was made “in accordance with the Issuer’s Insider Trading and Trading Window Policy,” which is the terminology US law use.
Thus confirming these restrictions were followed.
This is extra complicated for me, so if you know anything about this topic, or I am wrong, please elaborate.
Auber retweeted
Some news. Today, for the first time in Opendoor's history, we bought back our own stock.
Our share count is down 5%. We paid for this buyback with money borrowed at a 0% coupon and we still have hundreds of millions of dollars left to grow faster.
There are plenty of helpful details, along with a lot of legalese, in our press release and 8-K (linked below). But there are a few things I want to say directly and in plain English.
First, I *despise* dilution. On my first earnings call at Opendoor, I told you that if we issue a share, it has only one job: to make every other share worth more for our existing shareholders, not to extend runway for management. The flip side is just as simple: when our own stock is one of the best uses of capital, we should buy it back. Today, we did just that - by 5%.
Second, I run a publicly traded company. I don’t get to have feelings about the macro or the way Wall Street works. My job is to understand the rules of the game and use them to find an edge and build a better company.
One of those realities is that our stock price has lots of volatility.
People disagree - A LOT - about what Opendoor could be worth one day. Some think we're worth less. Some think we're worth dramatically more. I obviously have a view…
That disagreement isn’t just noise - it has economic value that Wall Street monetizes every single day.
Most companies would treat this as a headache, but we see it as an asset. If people are going to speculate about our future, I'd rather our shareholders get paid than anyone else. So instead of complaining about volatility, we used those dynamics to borrow $650M at a 0% coupon.
Then we turned around and used part of those proceeds to buy back our own stock. At today's prices, buying back our stock and call options was one of the best trades on the board. The rest stays on our balance sheet so we can buy more homes and grow faster.
As for dilution, we bought our stock where we thought it was cheap and pushed any future dilution far above today’s price. Not one net new Opendoor share will exist below $10.38. And if we buy back stock in the future, that floor goes higher.
But why raise now? Because the best time to raise capital is when you don’t need it. We’ve proven the business can reach ANI profitability, but profitability is just the starting point, not the finish line. And waiting could make the shares we are buying back today more expensive, and homes we could be buying don’t get bought. I’d rather move now.
Some people will call what we did today aggressive. They’re right. But being aggressive is how we fixed a company that spent years being careful. I’d make that trade again.
To our shareholders: You trusted us with your capital. Today, for the first time, Opendoor used its own capital to buy more of itself. The company is putting its money where its mouth is. Tomorrow, I will too.
After our lawyers allow, I’m personally buying $100K worth of shares. I'm all in, and I plan to keep buying.
Auber retweeted
Starting in March, the mortgage rate began rising from 6% to the current +6.6%.
If Opendoor continues to meet its guidance even under this macro environment, it would demonstrate over a full quarter that the business can not only survive in a context of increasingly higher rates, but actually grow.
Regardless of what happens in the upcoming earnings, whether the stock goes down, stays flat, or goes up.
It would still be a clear demonstration of strength in the company’s fundamentals.

Auber retweeted
It’s really difficult to define an approximation.
What you see in the latest week will always have some degree of decline, but we don’t know how far it will go.
The most important metric is the cumulative number, that one is the most reliable, since potential sales from two weeks ago usually don’t have many relistings.
Over time the number always stabilizes. I’ve seen a week hit 190 potential sales and later drop to 170, and I’ve also seen 220 potential sales fall to 170.
This variance depends heavily on the number of cancellations or any noise in the home’s status during that week.
All the data updates whenever a property changes its status, so any cumulative metric you see in the tracker is based on that. That’s why the total statistics are quite reliable.
Auber retweeted
UPDATE: A new CLARITY Act draft has been released, merging the Senate Banking and Agriculture Committee versions and adding an ethics provision for the first time.
A motion to proceed is expected Monday or Tuesday, with a possible floor vote the week of August 3.

Auber retweeted

Comps in the area (243 k)
Vs
$OPEN offer (241 k)
Realtor fee at 6% ($14,600)
Vs
$OPEN service fee ($12,088)
Repairs (can be viewed as “comps” IF house got full ask at $243 k)
Vs
$OPEN ($3,206)
Closing costs regular ($5-7 k in Florida)
Vs
$OPEN ($3,946)
No hassle, no waiting for offers, no “days on market.” Over all more cash at close. $OPEN is about to go parabolic. This is the all cash offer btw, not the “cash now more later option”
Do with this information what you will. $OPEN

Auber retweeted

Law enforcement recognizes that CLARITY strengthens the tools at their disposal (about 70 pages of the bill dedicated to this).
One more objection overturned.


Auber retweeted
Cash now, more later is really strong.
They pay you $100,000 or $250,000 upfront so you can cover the down payment on the next home you’re buying while your current one sells, and the reduction in the second payment is actually very small compared to the advance.
A smart seller is going to aim for this middle ground: a large guaranteed upfront payment and the rest in the second payout.
Auber retweeted
This gets even more interesting when someone who wants to move has already found a home they absolutely want to buy, they love it and don’t want to miss the opportunity, but they don’t yet have the cash to move forward.
Opendoor gives you that liquidity so you can buy it right away. Maybe the bank wouldn’t have approved the loan because you didn’t have enough cash on hand, but now they will.