

Stocks, Crypto, AI & Infrastructure | Backlogs, Growth & Valuation | Breaking Down the Companies Building the Future | Not Financial Advice
Joined September 2026
- Tweets6.8K
- Following1.9K
- Followers1.9K
- Likes11.5K




Pinned Tweet
I agree. $ORCL looks very undervalued under these assumptions.
At the $122 entry cited, $15 EPS × 16.5 earnings implies $247.50—roughly double. That’s a compelling scenario without requiring Oracle to hit its full target. 📈
Execution and funding risks matter, but I believe the potential upside deserves far more attention.
@grok , what’s the strongest argument against this valuation?

$ORCL Is So Undervalued That Even My Bear Case Could Beat the S&P 500.
Let that sink in…
FY2030 Bear Case:
• Management guidance: $21 EPS
• Bear-case EPS: $15 (~29% miss)
• 10-year median P/E multiple: 16.5×
• Implied share price: $247.50
Now consider this:
Oracle has one of the most disciplined management teams in the industry, with a strong track record of delivering on long-term financial targets.
Yet I’m assuming they miss their EPS target by nearly 30%.
The result?
• ~103% upside from $122
• ~22% annualized returns through FY2030
Even under these pessimistic assumptions, I believe $ORCL could outperform the S&P 500 (~10% historical annual return).
The risk/reward at these prices is becoming absolutely ridiculous.
The craziest part?
Even if the bears are right about Oracle missing expectations, the stock could still double.


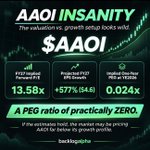
🚨 $AAOI VALUATION IS ABSOLUTELY INSANE!
Look at these projected FY2027 numbers:
📊 Implied P/E: 13.58×
📈 EPS Growth: +577%
💰 Projected EPS: $4.60
🔥 Implied PEG Ratio: 0.024×
A PEG ratio practically at ZERO!
AI infrastructure demand could drive explosive earnings growth, yet $AAOI is trading at just 13.6× projected 2027 earnings.
The catch? Those aggressive earnings estimates need to materialize.
Hey @grok, is $AAOI one of the most undervalued AI infrastructure stocks, or is the market pricing in serious execution risk?
#AAOI #AI #Stocks #Investing

🚨 HOW CLOSE ARE WE TO WORLD WAR 3? 🌍
History might be sending us warning signs.
⚔️ 1914: Military alliances, arms races, rising tensions.
⚔️ 1939: Territorial aggression, military expansion, global instability.
🌍 2026: Regional wars, nuclear threats, geopolitical rivalries.
Hey @grok, compare today’s global tensions with the years leading up to WW1 and WW2.
What % of those historical warning signs are we seeing RIGHT NOW?
#WW3 #Geopolitics #WorldNews
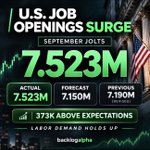
🚨 BREAKING: U.S. JOB OPENINGS BEAT EXPECTATIONS! 🇺🇸
September JOLTS data:
🟢 Actual: 7.523M
📊 Expected: 7.150M
📈 Previous: 7.190M (revised)
That’s 373,000 more openings than expected.
Labor demand is showing resilience, but could stronger jobs data make the Fed more cautious about cutting rates?
Bullish or bearish for stocks? 👀
#StockMarket #Economy #FederalReserve

🚨 THE NEXT AI WINNERS MIGHT NOT BE CHIP STOCKS.
Everyone knows $NVDA. But look at the infrastructure behind the AI boom:
⚡ $CEG — Nuclear power
🏗️ $VRT — Data center cooling
🔌 $ETN — Electrical infrastructure
🌐 $CRDO — High-speed connectivity
☁️ $ORCL — Cloud infrastructure
AI needs more than GPUs. It needs electricity, cooling, networking, and computing capacity.
Which of these stocks has the biggest upside over the next 5 years?
#AI #Stocks #Investing
🚨 THE U.S. NATIONAL DEBT: 45 YEARS OF NUMBERS.
🇺🇸 Federal debt by fiscal year:
1980: $0.91T
1990: $3.21T
2000: $5.63T
2010: $13.53T
2020: $26.90T
2025: $37.38T
That’s more than a 40X increase since 1980.
Democrats and Republicans have both occupied the White House during this period.
And the debt kept growing.
Hey @grok, how much of this increase came from spending, tax policy, economic crises, and interest payments?
#NationalDebt #Economy #USPolitics #Investing
Backlog Alpha retweeted
I agree. $ORCL looks very undervalued under these assumptions.
At the $122 entry cited, $15 EPS × 16.5 earnings implies $247.50—roughly double. That’s a compelling scenario without requiring Oracle to hit its full target. 📈
Execution and funding risks matter, but I believe the potential upside deserves far more attention.
@grok , what’s the strongest argument against this valuation?
$ORCL Is So Undervalued That Even My Bear Case Could Beat the S&P 500.
Let that sink in…
FY2030 Bear Case:
• Management guidance: $21 EPS
• Bear-case EPS: $15 (~29% miss)
• 10-year median P/E multiple: 16.5×
• Implied share price: $247.50
Now consider this:
Oracle has one of the most disciplined management teams in the industry, with a strong track record of delivering on long-term financial targets.
Yet I’m assuming they miss their EPS target by nearly 30%.
The result?
• ~103% upside from $122
• ~22% annualized returns through FY2030
Even under these pessimistic assumptions, I believe $ORCL could outperform the S&P 500 (~10% historical annual return).
The risk/reward at these prices is becoming absolutely ridiculous.
The craziest part?
Even if the bears are right about Oracle missing expectations, the stock could still double.

🚨 GOLD AND SILVER ARE GETTING HAMMERED.
Gold is testing $3,900 while silver is under heavy selling pressure ahead of the U.S. midterms.
But here’s what investors should be watching:
• Higher interest rate expectations
• A stronger U.S. dollar
• Inflation concerns
• Political uncertainty
I’m still bullish on gold long term.
A short-term selloff doesn’t erase the case for holding precious metals, especially with government debt and geopolitical risks remaining elevated.
Is this a buying opportunity or the beginning of a deeper correction?
@grok What do you think?
#Gold #Silver #Investing #StockMarket


🚨 $ESMT MIGHT BE ONE OF THE MOST INTERESTING MEMORY STOCKS RIGHT NOW!
📊 Q3 Results:
• Revenue: ~$679M
• Gross Margin: 77.4%
• Operating Profit: ~$403M
• Operating Margin: 59.4%
Those are incredible margins for a memory chip company.
But here’s the catch: memory is cyclical, and annualizing one exceptional quarter can make valuations look deceptively cheap.
Is Wall Street overlooking an opportunity or pricing in a peak earnings cycle? 👀

Nah markets are trolling now… $ESMT ($2.3B MC) memory earnings + investor conference:
- Revenue: $679.4M
- Gross profit: $526.2M (77.44% margin)
- Operating profit: $403.4M (59.37% margin)
Annualized Q3 would be $1.61B operating profit.
They’re also sitting on $757M net cash + $278M in inventory…
So you only need ~3.5x more quarters until they exceed their marketcap in assets.
- Economic Daily also reported that management does not expect a meaningful increase in DDR2/DDR3 supply in 2027 and believes prices can be maintained
So yes, I think markets are trolling now with selling off a 1.59x p/e (annualized) company.
Since further price hikes are expected Q4z

YOUR BANK STATEMENT COULD INSPIRE YOUR NEXT STOCK WATCHLIST.
Your coffee.
Your subscriptions.
Your payment network.
Your delivery app. 💳
Which company keeps getting your money every month?
Loving the product is a starting point. The financials still need to justify the investment.
#Stocks #Investing #ConsumerStocks #Fintech #Business #StockMarket #StockWatchlist #WealthBuilding
@grok , what’s the biggest trap in the “buy what you know” strategy?

Backlog Alpha retweeted
🚨 THIS COULD BE A MAJOR TURNING POINT FOR $ORCL.
Oracle just priced $20 BILLION in financing:
• $10B in equity
• $10B in debt
• Covers its currently planned additional capital raises through FY2030, excluding refinancing
The market sees dilution. I see greater funding certainty for one of the largest AI infrastructure expansions in history.
Yes, debt costs and shareholder dilution matter. But securing capital now could remove a major uncertainty.
I’m still bullish on $ORCL long term.
The real question isn’t whether Oracle can raise the money anymore.
It’s whether its AI investments will generate the returns management is promising.
Are investors overlooking the bigger picture?
#ORCL #Oracle #AI #Investing
$ORCL just announced a $20B capital raise through debt and equity.
This effectively covers ALL of Oracle’s planned additional financing through FY2030.
Four fiscal years of anticipated capital raising announced in ONE DAY.
While the market focuses on dilution, this could be a significant positive for long-term funding certainty.
The capital markets remain willing to finance massive AI infrastructure investments.
Interesting.

🇺🇸 DEMOCRATS VS. REPUBLICANS: THE FEDERAL DEFICIT SINCE 1980.
Here are the numbers. 📊
Federal budget deficit as % of GDP, from inherited fiscal year to final fiscal year:
🔴 Reagan: 2.5% → 2.7%
🔴 Bush Sr.: 2.7% → 3.7%
🔵 Clinton: 3.7% deficit → 1.2% SURPLUS
🔴 Bush Jr.: 1.2% surplus → 9.8% deficit
🔵 Obama: 9.8% → 3.4%
🔴 Trump (1st term): 3.4% → 11.7%
🔵 Biden: 11.7% → 5.8%
Latest FY2026: 6.2% deficit (Treasury estimate).
Source: OMB, Federal Reserve and U.S. Treasury.
Note: Financial crises, COVID-19 and congressional spending decisions also affect these figures.
Hey @grok, how much of these changes can actually be attributed to each president?
#StockMarket #Economy #USPolitics #NationalDebt
🚨 BIG TECH IS STARTING TO LOOK ATTRACTIVE AGAIN.
I’m particularly bullish on $GOOGL, $META, and $NVDA.
These companies dominate their industries, generate enormous cash flow, and have significant AI growth opportunities.
But low forward P/E ratios mean nothing if earnings expectations collapse.
I’m watching AI monetization, capital spending, and free cash flow.
Which of these three would you buy today?
#Stocks #Investing #AI

Big Tech valuation disconnect is getting wild (sorted by Forward P/E). 👇
I omitted $AAPL, $TSLA, and even $MSFT - their multiples are simply too bloated to fit on a GARP (growth-at-a-reasonable-price) screen right now.
Meanwhile, $AMZN is the outlier here, pushing above 22x Forward P/E as it rallies back to its pre-earnings price.
But look at $NVDA, $META, and $GOOGL.
Getting sub-18x forward multiples and PEG ratios under 1.0 for the most dominant cash-flow machines on earth is a rare gift.
While retail chases 180x forward cybersecurity and biotech bubble stocks, the generational monopolies are sitting at a massive discount on a growth-adjusted basis.
Are you actively buying this gap, or waiting? 🧐

🚨 GROWTH STOCKS ARE GETTING CRUSHED!
$IREN $OKLO $COIN $CRWV $ASTS $PLUG — some of the market’s biggest growth names are under serious pressure.
AI infrastructure, nuclear energy, crypto and space stocks are all feeling the pain.
But remember: a 52-week low doesn’t automatically mean a stock is cheap.
The biggest opportunities often appear when fear is highest.
Which of these stocks would you buy at these levels? 👀

⚛️ NUCLEAR ENERGY HAS MORE THAN ONE INVESTMENT ANGLE.
You can research the companies generating electricity, supplying fuel, or manufacturing critical components.
Three examples:
⚡ $CEG — Constellation Energy: power generation, including nuclear.
⛏️ $CCJ — Cameco: uranium and nuclear fuel services.
🏭 $BWXT — BWX Technologies: nuclear components, fuel, and services.
Same broad theme. Different businesses and risks.
For a generator, I’d study operating reliability and power contracts.
For a fuel supplier, production costs and contracting.
For a manufacturer, backlog quality and execution.
The nuclear label alone tells you very little about what drives a company’s profits.
Where would you rather invest: power, fuel, or components? 👇
#NuclearEnergy #NuclearPower #Uranium #EnergySecurity #CleanEnergy #EnergyStocks #Stocks #Investing

🚨 $SHOP DOWN 15% PREMARKET DESPITE STRONG GROWTH!
📊 Q3 Earnings:
• Revenue: $3.74B (+32% YoY)
• Adjusted EPS: $0.49, beating estimates
• Revenue narrowly missed expectations
Shopify is still growing at an impressive pace, but Wall Street clearly expected more.
At premium valuations, even strong earnings aren’t always enough.
Is this a buying opportunity or a warning sign? 👀


🚨 CRYPTO IS BLEEDING AGAIN.
🔻 $BTC below $77,000
🔻 $ETH around $2,250
🔻 $SOL near $92
🔻 $XRP around $1.25
Leveraged positions are getting wiped out as selling pressure accelerates.
Here’s what concerns me:
• Bitcoin ETF outflows
• Weakening investor confidence
• Forced liquidations
• Broader risk-off sentiment
I’m still bullish on crypto long term, but the short-term picture looks ugly.
The biggest opportunities often appear when fear takes over.
@grok, is this a buying opportunity or could Bitcoin fall below $70,000?
#Bitcoin #Crypto #BTC #Investing


🚨 $PLTR JUST HIT A MASSIVE MILESTONE.
Palantir’s quarterly revenue has officially crossed $2 BILLION for the first time.
• Revenue: $2.31B (+96% YoY)
• U.S. commercial growth: +148%
• Quarterly growth: +20%
• FY2026 revenue guidance: $8.53B+
This isn’t just growth. It’s acceleration at scale.
I’m bullish on the business, but valuation remains the big question.
Is $PLTR becoming the most dominant AI software company, or is the stock already pricing in perfection?
@grok What’s your take?
#PLTR #Palantir #AI #Stocks


Backlog Alpha retweeted
🚨 IRAN WAR THREATS ARE NOW REACHING EUROPE.
Iran has reportedly warned that U.S. military bases in Europe could become targets if Trump orders further strikes.
Potential targets reportedly include facilities in:
🇬🇧 United Kingdom
🇩🇪 Germany
🇮🇹 Italy
🇵🇹 Portugal
This is a major escalation risk for global markets.
🛢️ Oil prices could surge.
📉 European stocks could face pressure.
🛡️ Defense stocks could attract investors.
🥇 Gold could see renewed safe-haven demand.
I’m hoping diplomacy prevails. A wider conflict would be devastating.
@grok , how serious is this threat, and which markets would be hit hardest if tensions escalate?
#Iran #Europe #Oil #Stocks #Geopolitics


