

Defence and defence-related markets and equities. Not investment advice. Do your own due diligence.
Joined January 2025
- Tweets1.2K
- Following925
- Followers374
- Likes2.1K



Pinned Tweet
$RENK.DE presenting its maritime portfolio for the first time at Euronaval 2026.
Focus on propulsion solutions for USVs & targeted expansion of underwater expertise, also with a new order from $SAAB for a submarine program of a NATO state.
renk.com/en/newsroom/news/pr…

Challenging Defence Markets retweeted

Ben is one of the smartest / most experienced voices on this platform
Highly suggest following + paying attention

There is alot of interest in CUAS, RADA has done well in Ukraine & this sale cements that lead. For every $1 of sensor we are seeing $1-3 of integration and the explotation market is going to add $1+ to that when data fusion through AI becomes a thing.
leonardodrs.com/news/press-r…


We’re pleased to welcome Andrew Teich to our Board. Andrew brings more than 40 years of experience commercialising advanced technologies and nearly two decades of senior leadership at FLIR Systems, including as President and CEO from 2013 to 2017.
During his tenure, FLIR’s market capitalisation grew from approximately $60 million to more than $6 billion.
Andrew is the fourth senior aerospace and defence board appointment in recent weeks following former Airbus Commercial Aircraft CEO Fabrice Brégier as Board Chair and CEO of Helsing France Marc Fontaine and former Leonardo Helicopters U.S. CEO Clyde M. Woltman as directors.
We look forward to working with Andrew as we move towards certification and commercialisation of Valo.
#verticalaerospace #innovation #aviation

Challenging Defence Markets retweeted

Since $UMAC is basically my whole personality now, let me articulate how it fits oh so neatly into Maj's framework here:
"1. Spending heavily on capacity expansion. (One of my favorites)."
-> Square footage of manufacturing space has expanded from 53,000 sqft at the start of the year, to a current 105,000 sqft, with another 100,000 sqft to be acquired by years end. So ~50k -> 200k in one year. Headcount has gone from 81 to 330 in that time. Likely 400 by the end of the year.
"2. Inventory is increasing ahead of anticipated demand or new customer programs."
-> Inventory has been building, over the past 3 Qs:
--> Q3'25:
Raw materials: $717,907
Finished goods: $2,400,584
Prepaid deposits: $6,921,679
--> Q4'25:
Raw materials: $4,232,774
Finished goods: $1,083,874
Prepaid deposits: $9,748,483
--> Q1'26: $13,827,189
Raw materials: $12,193,535
Finished goods: $1,633,654
Prepaid deposits: $13,566,078
--> Q2'26:
Raw materials: $17,469,622
Finished goods: $4,444,710
Prepaid deposits: $20,543,732
Notably, raw materials and deposits are scaling way ahead of finished goods. Is that because they're just stockpiling materials?
No.
During that time, revenue has moved from:
--> Q3'25: $2,134,588
--> Q4'25: $4,898,359
--> Q1'26: $8,095,836
--> Q2'26: $16,722,467
This while maintaining gross margins in the mid 30's.
Based on "not guidance", I expect revenue to be flat to slightly down for Q3, finished inventory to be flatish, and raw materials to jump in anticipation of a flood of demand in the Q4/Q1 timeframe.
"3. Investing in a new product or entering a new market that could create a meaningful recurring revenue stream. (One of my favorites)."
-> UMAC just closed the acquisition of Upgrade Energy, putting them squarely in the drone battery supply chain. Known customers of Upgrade Energy include $AVAV, Anduril, Neros, and other Drone Gauntlet participants. Notably, batteries have a known replacement cycle, creating that recurring revenue component not seen in other drone hardware components.
"4. Accounts receivable are growing because sales are accelerating. (Cash flow may lag reported earnings as customers take time to pay)."
--> Accounts receivable have been growing in line with revenues and materials:
--> Q3'25: $309,544
--> Q4'25: $1,564,739
--> Q1'26: $3,128,885
--> Q2'26: $9,333,235
"5. Spending heavily on automation or equipment that could improve margins and reduce operating costs for years to come. (Could have put this in the capacity expansion bucket, but it’s a little more specific)."
-> UMAC is currently commissioning an automated motor line, which will increase their motor output by about 100,000 per month. This is an increase from their current capacity of 30,000/month, for a total capacity of 130,000/month once online. After gathering production and quality control data, management expects to order 8 to 10 more automated lines.
Of course, all this growth has not occurred without it's costs. In the time frame represented, share count has taken the following trajectory:
--> Q3'25: 30,002,179
--> Q4'25: 37,759,911
--> Q1'26: 46,708,842
--> Q2'26: 48,611,102
But operational inflection is near. Operational profits are expected in the Q1/Q2 timeframe, and I expect dilution to simmer down, relating primarily to compensation rather than funding operations.
DYODD not FA I'm obviously bullish.

Declining or negative free cash flow isn't always a sign of a deteriorating business. Sometimes it's the cost of building a better one, where the revenue and earnings may not show up until later.
1. Spending heavily on capacity expansion.
(One of my favorites).
2. Inventory is increasing ahead of anticipated demand or new customer programs.
3. Investing in a new product or entering a new market that could create a meaningful recurring revenue stream. (One of my favorites).
4. Accounts receivable are growing because sales are accelerating. (Cash flow may lag reported earnings as customers take time to pay).
5. Spending heavily on automation or equipment that could improve margins and reduce operating costs for years to come. (Could have put this in the capacity expansion bucket, but it’s a little more specific).
Of course, none of these automatically excuse a worsening cash flow. You still have to figure out whether the spending is creating value or just keeping a struggling business alive. Or, even bigger, will management execute?
However, the direction of cash flow matters less than understanding what's driving the change and whether it's temporary or a bigger issue.
Challenging Defence Markets retweeted

New article! Germany Is Building Tanks in Norway Again. This Time, Norway Invited Them
A new Leopard 2A8 production line in Levanger looks routine. But put it next to the submarines, sub-hunting planes, and a polar spaceport, and it looks like Berlin and Oslo quietly building a northern alliance.
Link in the comments:
#Germany #Norway #NATO

Challenging Defence Markets retweeted

"Here’s what many investors fail to understand. Your greatest advantage in a market crash isn’t having the courage to buy. It’s having structured your life and finances so that you aren’t forced to sell. That advantage must be built long before the crash arrives."

Every market crash I’ve lived through, someone has asked me the same question:
“Aren’t you scared?”
Of course I am. I’m human. I watch my wealth evaporate on paper just like everyone else. Fear doesn’t magically disappear because you’ve been investing for decades.
But experience has taught me something far more valuable than how to predict the next market crash. The people selling in a panic aren’t necessarily foolish or uninformed. Many are exceptionally intelligent. They simply have obligations that don’t care about market conditions. a mortgage, a nervous client, a boss demanding answers. They have a clock running.
I don’t have that clock. And I’ve come to realize just how extraordinary an advantage that is.
Not superior intelligence, faster information, or some brilliant forecasting model. Simply the financial freedom and emotional discipline to remain patient when others have no choice but to act.
Here’s what many investors fail to understand. Your greatest advantage in a market crash isn’t having the courage to buy. It’s having structured your life and finances so that you aren’t forced to sell. That advantage must be built long before the crash arrives.
Never borrow more than you can survive losing. Never invest money you’ll need in the foreseeable future. And never put yourself in a position where someone else’s timetable determines your investment decisions.
Because patience isn’t merely a psychological virtue. It’s a financial privilege you must deliberately create and fiercely protect.
The market may reward patience, but only those who can afford to be patient will ever collect that reward.
If you want to become a better investor, follow along and share my investing wisdom. 🙏🌹
Challenging Defence Markets retweeted

Farewell to the great Patrick Stewart. And farewell also, Captain Picard. In the greatest trek of all — our search for the possibilities of our better selves — you will always be our Captain.
noahpinion.blog/p/farewell-m…

Challenging Defence Markets retweeted

This is the most incredible exchange I have ever seen on an earnings call.
It represents the best of investing.
This kind of opportunity is accessible to everyone, including you and me. No PhD required.
Was there luck involved? Sure. But was it lucky? Absolutely not.
Being the type of investor who makes this kind of investment is the first step in capturing one.

Challenging Defence Markets retweeted

Proud to fly alongside @BETA_aircraft as we kick off @MyFDOT ’s eIPP, retracing the world’s first scheduled airline flight, flown by Tony Jannus in 1914.
From Jannus to electric flight, American aviation keeps moving forward. 🇺🇸


Makes sense.
Nature of the LEO market doesn't support lots of players.

🇪🇺🇨🇦 Kanada może dołączyć do europejskich programów satelitarnych Galileo i IRIS²!
Podczas szczytu UE–Kanada w Montrealu przygotowano propozycje pogłębienia współpracy w strategicznych technologiach kosmicznych.
➡️ Galileo – rozpoczęcie negocjacji dotyczących dostępu Kanady do chronionych usług europejskiego systemu nawigacji satelitarnej, będącego alternatywą dla amerykańskiego GPS.
➡️ IRIS² – rozważenie udziału Kanady w europejskim systemie bezpiecznej łączności satelitarnej, stanowiącym alternatywę dla amerykańskiego Starlinka. System ma służyć między innymi wojsku, administracji i użytkownikom komercyjnym.
Uniezależnienie się od nieobliczalnych Stanów Zjednoczonych jest niezwykle ważne zarówno dla Europy, jak i Kanady.

$ETL.PA Q1:
LEO on plan but from >30% to ~30% growth, Q1 27 was +30.1%.
Video -17.8%, should moderate but worse than my expectations.
Backlog now at €12.1b with €8.9b of IRIS2 added. Non-IRIS2 backlog declined, €3.4b to €3.2b.
eutelsat.com/media-press/med…


$THEON.AS has received all required approvals for the completion of the acquisition of an 80% stake in MERIO - French gimbal maker.
Already receiving of an order for ~€5 million for MERIO’s solutions for UAV applications (synergies).
theon.com/en/news/2026/theon…

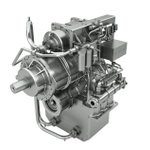
$RENK.DE is positioning itself as the preferred partner for propulsion systems for future Medium-sized USVs (MUSV) platforms and is actively shaping this development.
Their marine gear unit, the T2RECS (pictured), covers a power range of 500 to 5,000 kW.

$SAAB has released details of a new construct it has developed, and demonstrated, for protecting maritime borders, including particular sites and assets and/or broader at-sea areas: Ocean Barrier.
navalnews.com/event-news/eur…

Challenging Defence Markets retweeted
Foreign defence contractors will need to invest in UK under new rules bbc.in/3WUydqK
